
Interim Results for the Six Months to 30 June 2026

Bezant Resources PLC
30 September 2026
30 September 2026
Bezant Resources Plc
(“Bezant” or the “Company”)
Interim Results forthe Six Months Ended30 June 2026
Bezant (AIM: BZT), the copper-gold exploration and development company, announces its unaudited interim results for the six months ended 30 June 2026.
Chairman’s Statement
Dear Shareholder,
I am pleased to report that the period under review has seen considerable progress for Bezant Resources, most notably at our flagship Hope and Gorob copper-gold project in Namibia, which is now approaching the important transition from development into production.
Hope and Gorob, Namibia
Development of the Hope and Gorob project has continued to progress very well, with activities at both the mine and Tsoaxaub Metals Processing Plant advancing towards first production.
The modifications and upgrades to the Tsoaxaub Metals Processing Plant have been successfully implemented, and we currently expect first concentrate production during early October. Subject to commissioning and logistical arrangements proceeding as planned, concentrate is expected to be transported to Walvis Bay, Namibia towards the end of October, with the first shipment anticipated in early November.
Mining activities at Hope are already well-advanced. Initial mining has established a stockpile of approximately 10,000 tonnes of run-of-mine material (unprocessed ore), providing feedstock for the commencement of processing operations.All key labour required for the initial operating phase has also been recruited, allowing the project to move progressively from construction and commissioning into operations.
During the period, the Company has also substantially strengthened the financial and commercial framework surrounding the project. The financing and offtake arrangements with Hartree Metals are in place and provide an important foundation for the development and operation of Hope and Gorob. The accelerated arrangements relating to the Tsoaxaub Metals Processing Plant and financing thereof by Hartree have also been put in place post the period end, further simplifying the project financing and corporate structure as we approach production.
The Board is particularly encouraged by the progress made over a relatively short period. The successful plant modifications, commencement of mining, establishment of the initial ore stockpile and completion of the principal financing arrangements represent significant milestones for Bezant.
Our immediate priority is now the successful commissioning of the processing operation, followed by the establishment of steady-state production and concentrate shipments.
Botswana
In Botswana, we continue our desk-based technical work and evaluation of the Company’s manganese interests. This work is intended to further refine our geological understanding and assist in defining the most appropriate targets for the next phase of exploration.
Subject to the results of this work and the necessary operational planning, we expect drilling to commence during 2027.
While Namibia is naturally receiving considerable management attention as Hope and Gorob enters production, we remain conscious of the importance of maintaining a broader portfolio of opportunities capable of contributing to the Company’s future growth.
Copper Market
The underlying fundamentals for copper remain supportive. Copper continues to play an increasingly important role in global electrification, power transmission and distribution, renewable energy infrastructure, electric vehicles and the expansion of AI data centres and digital infrastructure.
At the same time, bringing new copper mines into production remains a very lengthy and capital-intensive process. Recent industry analysis continues to point towards constraints in future mine supply relative to anticipated demand, notwithstanding the advancement of a number of new projects globally.
Against this background, the Board believes that advancing Hope and Gorob into production is particularly timely. Our focus, however, remains firmly on those matters within our control: establishing reliable production, maintaining cost discipline and progressively demonstrating the operational and economic potential of our Namibian assets.
Outlook
The coming months represent an important period for Bezant. The transition of Hope and Gorob from development into production will mark a significant change in the Company’s profile.
We expect first concentrate production in early October, transport of concentrate to Walvis Bay towards the end of the month and, subject to shipping and logistical arrangements, the first shipment in early November.
Thereafter, our focus will be on achieving consistent production and evaluating opportunities to optimise and, where appropriate, expand the operation, while continuing to advance our wider portfolio.
I am not aware of any other AIM listed exploration company that in the last 10 years has acquired and taken a copper project from the exploration phase, to a mine with a processing plant and which is a credit to our highly committed management team who have shown exemplary planning, execution and delivery.I would like to thank our employees, contractors, partners and advisers in Namibia for their considerable efforts in bringing the project to this stage. Last but not least I would also like to thank our shareholders for their continued support as Bezant enters what we believe will be an important new phase in its development.
Colin Bird
Chairman
Operational, Corporate and Financial Summary
- Overview
The first half of 2026 was a transformational period for Bezant Resources Plc (“Bezant” or “the Company”), marked by substantial progress at and focus on the Company’s flagship project Hope and Gorob copper‑gold project in Namibia (“Hope and Gorob Project”), which has seen a consolidation of project ownership, significant advancement of mine and plant development, and strengthening of the Company’s financing position.
The Company remains on track to for first run-of-mine ("ROM") ore to be processed through the repurposed Tsoaxaub Metals Processing Plant during September 2026 which will generate the first concentrate from the Hope and Gorob mine. supported by a renewed processing licence, major contractor appointments, and a significantly upgraded Mineral Resource Estimate.
- Hope and Gorob Copper‑Gold Project – Development Progress mine development and construction and Tsoaxaub Metals Processing Plant upgrade
Throughout the Period, Bezant advanced mine development at Hope and Gorob following the acquisition of the Tsoaxaub Metals Processing Plant in December 2025.
The Project remains on schedule for first run-of-mine ("ROM") ore to be processed through the repurposed Tsoaxaub Metals Processing Plant during September 2026 which will generate the first concentrate from the Hope and Gorob mine
Key achievements during the Period included:
- Completion of 100% of engineering design for mine and plant upgrades.
- Award of major contracts to Unitrans Namibia, UMS Projects SA, and Weir Minerals.
- Procurement of long‑lead items, including the cone crusher for Tsoaxaub Metals.
- Commencement of civils and earthworks at the mine site.
- Removal of redundant equipment at Tsoaxaub Metals ahead of new installations.
- Progress on tailings dam rehabilitation and plant flow‑sheet redesign.
These activities collectively position the project for first concentrate production in early October.
Appointment of mining and logistics contractor: Bezant announced the signing of an exclusive Mining and Logistics Services Agreement with Unitrans Namibia Pty Ltd on 11 March 2026 and the services to be provided will include drilling, blasting, loading and hauling and material handling at the Tsoaxaub Metals Processing Plant. This long‑term agreement (initial 5‑year term) secures a critical operational partner for mining, haulage, and logistics.
Tsoaxaub Metals Mining Licence: On 10 March 2026, Tsoaxaub Metals mining licence ML185 was renewed for 10 years to 24 February 2036.This provides regulatory certainty for processing Hope and Gorob pre‑concentrate at the Tsoaxaub Metals Processing Plant.
- Mineral Resource Upgrade – Hope Deposit
On 8 April 2026, Bezant released a new JORC‑compliant Mineral Resource Estimate prepared by Sound Mining, for the Hope deposit showing a sevenfold increase in open‑pittable tonnes:
Key highlights:
- 3.0 Mt open‑pittable resource (gross basis).
- Measured: 1.1 Mt; Indicated: 0.5 Mt; Inferred: 1.4 Mt.
- Strip ratio reduced from 11:1 to 9:1, lowering mining costs.
- Open‑pit life extended from 1 year to 7.5 years at 0.4 Mtpa feed rate.
- Additional mineralisation identified outside the pit shell with potential to add 5+ years of production.
This upgrade materially enhances project economics and supports accelerated Phase 2 development planning.
- Hope and Gorob Project Ownership Consolidation
On 24 March 2026, Bezant acquired an additional 20% interest in Hope and Gorob Mining (Pty) Ltd, increasing its ownership from 70% to 90% which strengthened Bezant’s economic exposure to its flagship asset. The consideration comprised:
- £557,000 settled via 515,263,645 shares at 0.10810p per share.
- £577,000 in staged cash payments (now paid).
- Financing Activities
£2.07 million equity fundraising: On 31 March 2026, Bezant completed an oversubscribed fundraising of £2,070,000 at 0.065p per share.
Hartree Metals: On 11 June 2026 the Company announced a US$7 million secured prepayment facility and offtake agreements with Hartree Metals LLC (“Hartree Metals”) for the development of the Hope and Gorob Copper Project to support construction of the Hope and Gorob mine site and commissioning activities at the Tsoaxaub Metals Processing Plant in Namibia. Under the offtake agreement Hartree will purchase 100% of the copper concentrates produced for the life of the operation from Hope and Gorob Copper Project at market terms (“Offtake Agreement”).
During the period the Company received £722,900 from the exercise of warrants and share sale proceeds of £1.2 million from the sale of its Blackstone Minerals shares.
The above proceeds were used to pay the cash element of the additional 20% Hope and Gorob acquisition, fast‑tracking mine development and Tsoaxaub Metals Processing Plant upgrades and working capital and corporate overheads.
- Financial Summary
Net loss for H1 2026 of approximately £2.19m (H1 2025: profit £4.07m)
Total assets were £14.3m as at the half-year end (31 December 2025: £9.70m)
Cash position of £0.73m as at the half-year end (31 December 2025: £0.430m)
Total liabilities of £4.65m as at the half-year end (31 December 2025: £1.35m)
- Outlook
Bezant enters the second half of 2026 with:
- A 90% interest in its flagship project.
- Major contractors mobilised.
- A significantly upgraded Mineral Resource.
- Funding secured to progress development.
- First concentrate production targeted for October 2026.
The Board remains focused on completing commissioning, securing project financing, and delivering first production.
- Post‑Period Events
- Hope and Gorob Project Update
Bezant has achieved a major operational milestone with the first blast at the Hope open pit and ROM ore has been stock piled at the expanded ROM pad at the Tsoaxaub Metals Processing Plant.
Since the period end, the Group has continued to make significant progress at the Hope and Gorob Copper-Gold Project and the associated Tsoaxaub Metals Processing Plant in Namibia. Management has reported that development activities remain on schedule and, subject to completion of final commissioning activities, expects first run-of-mine ore to be processed during September 2026, generating the first concentrate from the project.
At the mine site, initial blasting activities have been completed, ore has been stockpiled for transportation to the processing plant and the mining and haulage fleet has been delivered to site.At the Tsoaxaub processing plant, major civil works have been completed, commissioning activities are advancing and key processing infrastructure has been installed and tested in preparation for production.
The Company has also commenced a review of a potential Phase II expansion based on the current mineral inventory and prevailing commodity prices. Management believes the project has the potential to support an estimated mine life of approximately 35 years based on current processing capacity, although technical and economic evaluations remain ongoing.
- Tsoaxaub Metals financing arrangements
In addition, subsequent to the period end the Company entered into accelerated payment arrangements in respect of the acquisition of the Tsoaxaub Metals Processing Plant and subsequently secured financing support from Hartree Metals LLC in relation to those arrangements. These developments are discussed further in Note 16, Subsequent Events
For further information, please contact:
|
Bezant Resources Plc Colin Bird Executive Chairman |
| |
|
Beaumont Cornish (Nominated Adviser) |
| |
|
Novum Securities Limited (Joint Broker) Jon Belliss |
+44 (0) 20 7399 9400 | |
|
Shard Capital Partners LLP (Joint Broker) Damon Heath |
+44 (0) 20 7186 9952 |
or visit http://www.bezantresources.com
The information contained within this announcement is deemed by the Company to constitute inside information as stipulated under the Market Abuse Regulations (EU) No. 596/2014 as it forms part of UK Domestic Law pursuant to the Market Abuse (Amendment) (EU Exit) regulations (SI 2019/310).
Beaumont Cornish Limited ("Beaumont Cornish") is the Company's Nominated Adviser and is authorised and regulated by the FCA. Beaumont Cornish's responsibilities as the Company's Nominated Adviser, including a responsibility to advise and guide the Company on its responsibilities under the AIM Rules for Companies and AIM Rules for Nominated Advisers, are owed solely to the London Stock Exchange. Beaumont Cornish is not acting for and will not be responsible to any other persons for providing protections afforded to customers of Beaumont Cornish nor for advising them in relation to the proposed arrangements described in this announcement or any matter referred to in it.
Distribution: This announcement has been notified via a Regulatory Information Service and it is not authorised for distribution into North America or any other jurisdiction where to do so would constitute a violation of the relevant laws or regulations of that jurisdiction.
Group Statement of Profit and Loss
For the six months ended 30 June 2026
|
|
Notes |
Unaudited Six months ended 30 June 2026 £’000 |
Unaudited Six months ended 30 June 2025 £’000 |
|
|
|
|
|
|
CONTINUING OPERATIONS |
|
|
|
|
|
|
|
|
|
Group revenue |
|
- |
- |
|
Cost of sales |
|
- |
- |
|
|
|
|
|
|
Gross profit |
|
- |
- |
|
|
|
|
|
|
Operating expenses |
4 |
(1,753) |
(344) |
|
Group operating loss |
|
(1,753) |
(344) |
|
|
|
|
|
|
Other gains/(losses) |
5 |
(346) |
4,348 |
|
Finance Costs |
|
(94) |
62 |
|
Impairment of assets |
|
- |
- |
|
|
|
|
|
|
Loss before taxation |
|
(2,193) |
4,066 |
|
Taxation |
|
- |
- |
|
|
|
|
|
|
Profit / (Loss) for the period |
|
(2,193) |
4,066 |
|
|
|
|
|
|
Attributable to: Owners of the Company |
|
(2,193) |
4,066 |
|
- Continuing operations |
|
(2,193) |
4,000 |
|
- Discontinued operations |
|
- |
66 |
|
Non-controlling interest |
|
- |
- |
|
|
|
(2,193) |
4,066 |
|
Profit / (Loss) per share (pence) |
|
|
|
|
Basic profit /(loss) per share from continuing operations |
6 |
(0.011) |
0.027 |
|
Diluted profit / (loss) per share from continuing operations |
6 |
(0.011) |
0.018 |
Group Statement of Other Comprehensive Income
For the six months ended 30 June 2026
|
|
|
Unaudited Six months ended 30 June 2026 £’000 |
Unaudited Six months ended 30 June 2025 £’000 |
|
Other comprehensive income: |
|
|
|
|
Profit /(loss) for the period |
|
(2,193) |
4,066 |
|
Items that may be reclassified to profit or loss: |
|
|
|
|
Foreign currency reserve movement |
|
301 |
(5) |
|
Total comprehensive profit /(loss) for the period |
|
(1,892) |
4,061 |
Group Statement of Changes in Equity
For the six months ended 30 June 2026
|
|
Share Capital £’000 |
Share Premium £’000 |
Other Reserves1 £’000 |
Retained Losses £’000 |
Total Equity £’000 |
|
Unaudited – six months ended 30 June 2026 |
|
|
|
|
|
|
Balance at 1 January 2026 |
2,326 |
42,711 |
3,601 |
(40,289) |
8,349 |
|
Current period profit |
- |
- |
- |
(2,193) |
(2,193) |
|
Foreign currency reserve |
- |
- |
301 |
- |
301 |
|
|
|
|
|
|
|
|
Total comprehensive loss for the period |
- |
- |
301 |
(2,193) |
(1,892) |
|
Proceeds from shares issued |
64 |
2,006 |
- |
- |
2,070 |
|
Shares issued - acquisition shares |
10 |
547 |
- |
- |
557 |
|
Shares issued – in lieu of fees |
- |
7 |
- |
- |
7 |
|
Share issue costs |
- |
(1,457) |
- |
- |
(1,457) |
|
Warrants issued |
- |
- |
1,334 |
- |
1,334 |
|
Warrants exercised |
24 |
699 |
- |
- |
723 |
|
Balance at 30 June 2026 |
2,424 |
44,513 |
5,236 |
(42,482) |
9,691 |
|
|
Share Capital £’000 |
Share Premium £’000 |
Other Reserves1 £’000 |
Retained Losses £’000 |
Total Equity £’000 |
|
Unaudited – six months ended 30 June 2025 |
|
|
|
|
|
|
Balance at 1 January 2025 |
2,224 |
41,663 |
3,659 |
(42,447) |
5,099 |
|
Current period profit |
- |
- |
- |
4,066 |
4,066 |
|
Foreign currency reserve |
- |
- |
(5) |
- |
(5) |
|
|
|
|
|
|
|
|
Total comprehensive loss for the period |
- |
- |
(5) |
4,066 |
4,061 |
|
Proceeds from shares issued |
56 |
504 |
- |
- |
560 |
|
Share issue costs |
- |
(275) |
- |
- |
(275) |
|
Shares issued – in lieu of fees |
16 |
223 |
- |
- |
239 |
|
Warrants issued |
- |
- |
249 |
- |
249 |
|
Warrants expired |
- |
- |
(20) |
20 |
- |
|
Equity component of borrowings |
- |
- |
2 |
- |
2 |
|
Balance at 30 June 2025 |
2,296 |
42,115 |
3,885 |
(38,361) |
9,935 |
1 Other reserves is made up of the share-based payment and foreign exchange reserve.
Group Balance Sheet
As at 30 June 2026
|
|
|
|
| |
|
|
|
|
Unaudited |
Audited |
|
|
|
|
30 June |
31 December |
|
|
|
|
2026 |
2025 |
|
|
Notes |
|
£’000 |
£’000 |
|
ASSETS
|
|
|
|
|
|
Non-current assets |
|
|
|
|
|
Processing plant |
10 |
|
4,798 |
1,768 |
|
Plant and equipment |
10 |
|
1,436 |
578 |
|
Mine Development |
9 |
|
5,512 |
3,952 |
|
Investments |
7 |
|
60 |
1,606 |
|
Exploration and evaluation assets |
8 |
|
1,308 |
1,232 |
|
Total non-current assets |
|
|
13,114 |
9,136 |
|
|
|
|
|
|
|
Current assets |
|
|
|
|
|
Inventories |
|
|
55 |
55 |
|
Trade and other receivables |
|
|
437 |
76 |
|
Cash and cash equivalents |
|
|
734 |
430 |
|
|
|
|
1,226 |
561 |
|
Total current assets |
|
|
1,226 |
561 |
|
|
|
|
|
|
|
TOTAL ASSETS |
|
|
14,340 |
9,697 |
|
|
|
|
|
|
|
LIABILITIES |
|
|
|
|
|
Current liabilities |
|
|
|
|
|
Trade and other payables |
11 |
|
2,624 |
464 |
|
Borrowings |
12 |
|
1,754 |
620 |
|
Total current liabilities |
|
|
4,385 |
1,084 |
|
|
|
|
|
|
|
Non-current liabilities |
|
|
|
|
|
Provisions |
|
|
271 |
264 |
|
Total non-current liabilities |
|
|
271 |
264 |
|
|
|
|
|
|
|
TOTAL LIABILITIES |
|
|
4,649 |
1,348 |
|
NET ASSETS |
|
|
9,691 |
8,349 |
|
EQUITY |
|
|
|
|
|
Share capital |
13 |
|
2,424 |
2,326 |
|
Share premium |
13 |
|
44,513 |
42,711 |
|
Share-based payment reserve |
|
|
2,777 |
1,443 |
|
Foreign exchange reserve |
|
|
434 |
133 |
|
Merger reserve |
|
|
1,831 |
1,831 |
|
Other reserves |
|
|
194 |
194 |
|
Retained losses |
|
|
(42,482) |
(40,289) |
|
|
|
|
9,691 |
8,349 |
|
TOTAL EQUITY |
|
|
9,691 |
8,349 |
Group Statement of Cash Flows
For the six months ended 30 June 2026
|
|
|
Unaudited |
Unaudited |
|
|
|
Six months ended 30 June 2026 |
Six months ended 30 June 2025 |
|
|
Notes |
£’000 |
£’000 |
|
|
|
|
|
|
Net cash outflow from operating activities |
15 |
263 |
(188) |
|
|
|
|
|
|
Cash flows from/(used) in investing activities |
|
|
|
|
Deferred exploration expenditure |
|
(71) |
(479) |
|
Mine Development & Processing Plant |
|
(4,033) |
- |
|
Payments for plant |
|
(858) |
- |
|
Proceeds from sale of equity investments |
|
1,199 |
181 |
|
|
|
(3,763) |
(479) |
|
Cash flows from financing activities |
|
|
|
|
Payments from disposal of subsidiaries |
|
- |
(23) |
|
Proceeds from issue of ordinary shares |
|
2,670 |
534 |
|
Borrowings |
|
1,134 |
- |
|
|
|
3,804 |
692 |
|
Increase/(decrease) in cash |
|
304 |
25 |
|
|
|
|
|
|
Cash and cash equivalents at beginning of period |
|
430 |
88 |
|
|
|
|
|
|
Cash and cash equivalents at end of period |
|
734 |
113 |
Notes to the interim financial information
For the six months ended 30 June 2026
|
1. |
Accounting Policies
Basis of preparation The unaudited interim financial information set out above, which incorporates the financial information of the Company and its subsidiary undertakings (the “Group”), has been prepared using the historical cost convention and in accordance with International Financial Reporting Standards (“IFRS”), including IFRS 6 ‘Exploration for and Evaluation of Mineral Resources’, as adopted by the European Union (“EU”) and with those parts of the Companies Act 2006 applicable to companies reporting under IFRS.
These interim results for the six months ended 30 June 2026 are unaudited and do not constitute statutory accounts as defined in section 434 of the Companies Act 2006.The financial statements for the year ended 31 December 2025 have been delivered to the Registrar of Companies and the auditors’ report on those financial statements was unqualified and contained a material uncertainty pertaining to going concern.
Going concern basis of accounting The Group made a loss from all operations for the six months ended 30 June 2026 after tax of £2.19million which included a provision of £967K in relation to a Company Share Price Award and a fair value adjustment loss of £346K (2025: profit of £4.07million), which included an a non cash gain and fair value adjustment profit of £4.28 million and had negative cash flows from operations and is currently not generating revenues. Cash and cash equivalents were £734K as at 30 June 2026 (December 2025 £430K).
On 31 March 2026, Bezant completed an oversubscribed fundraising of £2,070,000 at 0.065p per share. During the period the Company received £722,900 from the exercise of warrants and share sale proceeds of £1.2 million from the sale of its Blackstone Minerals shares.
On 11 June 2026 the Company announced a US$7 million secured prepayment facility and offtake agreements with Hartree Metals LLC (“Hartree Metals”) for the development of the Hope and Gorob Copper Project to support construction of the Hope and Gorob mine site and commissioning activities at the Tsoaxaub Metals Processing Plant in Namibia.Under the offtake agreement Hartree will purchase 100% of the copper concentrates produced for the life of the operation from Hope and Gorob Copper Project at market terms (“Offtake Agreement”).
Based on the Board's assessment that the Company will be able to raise additional funds, as and when required, to meet its working capital and capital expenditure requirements, the Board have concluded that they have a reasonable expectation that the Group can continue in operational existence for the foreseeable future. For these reasons the Group continues to adopt the going concern basis in preparing the annual report and financial statements.
There is a material uncertainty related to the conditions above that may cast significant doubt on the Group's ability to continue as a going concern and therefore the Group may be unable to realize its assets and discharge its liabilities in the normal course of business.
The financial report does not include any adjustments relating to the recoverability and classification of recorded asset amounts or liabilities that might be necessary should the entity not continue as a going concern.
Basis of preparation The financial information, which incorporates the financial information of the Company and its subsidiary undertakings (the “Group”), has been prepared using the historical cost convention and in accordance with UK adopted International Accounting Standards including IFRS6 ‘Exploration for and Evaluation of Mineral Resources’.
Basis of consolidation The consolidated financial statements incorporate the financial statements of the Company and its subsidiary undertakings and have been prepared using the principles of acquisition accounting, which includes the results of the subsidiaries from their dates of acquisition.
All intra-group transactions, income, expenses and balances are eliminated fully on consolidation.
A subsidiary undertaking is excluded from the consolidation where the interest in the subsidiary undertaking is held exclusively with a view to subsequent resale and the subsidiary undertaking has not previously been consolidated in the consolidated accounts prepared by the parent undertaking
Company Statement of Comprehensive Income The Company has taken advantage of the exemption allowed under section 408 of the Companies Act 2006 and has not presented its own Statement of Comprehensive Income in these financial statements.
Mine and processing plant properties and plant and equipment Initial recognition of mine properties and plant and equipment. Upon completion of the mine construction phase, the assets are transferred into “Plant and equipment” or “Mine and processing plant properties”. Items of plant and equipment and producing mine are stated at cost, less accumulated depreciation and accumulated impairment losses. The initial cost of an asset comprises its purchase price or construction cost, any costs directly attributable to bringing the asset into operation, the initial estimate of the decommissioning and rehabilitation obligation, and, for qualifying assets (where relevant), borrowing costs. The purchase price or construction cost is the aggregate amount paid and the fair value of any other consideration given to acquire the asset. The capitalised value of a finance lease is also included in plant and equipment.
Depreciation and amortisation, Depreciation is calculated to write off the cost of items of the assets less their estimated residual values using the straight-line method over their estimated useful lives, and is recognised in profit or loss. The average useful lives applied to the various categories of the assets are as follows:
An item of plant and equipment and any significant part initially recognised is derecognised upon disposal or when no future economic benefits are expected from its use or disposal. Any gain or loss arising on derecognition of the assetis included in statement of profit or loss and other comprehensive income when the asset is derecognised. The asset’s residual values, useful lives and methods of depreciation are reviewed at each reporting period and adjusted prospectively, if appropriate. An asset's carrying amount is written down to its recoverable amount if the asset's carrying amount exceeds the higher of the asset's fair value less costs to sell or value in use
Repairs and maintenance are generally expensed when incurred. However, major repairs and renovations are capitalised and included in the carrying amount of the asset, when it is probable that future economic benefits associated with the item will flow to the entity. Major repairs and renovations are depreciated over the remaining life of the related asset. Refer to note 2 for the Company’s policy in respect of exploration, evaluation and development expenditure.
Provisions Provisions are recognised when the Group has a present legal or constructive obligation as a result of past events, it is probable that an outflow of resources embodying economic benefits will be required to settle the obligation, and a reliable estimate of the amount can be made. Where these conditions are not met, no provision is recognised. Provisions are measured at the present value of management’s best estimate of the expenditure required to settle the obligation at the reporting date. The measurement of provisions reflects, current estimates of the costs required to settle the obligation, risks and uncertainties surrounding the obligation; and where material, the time value of money using a pre-tax discount rate that reflects current market assessments.
The Group recognises a provision for the future costs of rehabilitation, restoration and decommissioning of mining sites and related facilities in the period in which the disturbance giving rise to the obligation occurs. The provision is calculated based on, estimated future costs of rehabilitation, timing of expenditure; and applicable discount and inflation rates.A corresponding asset is recognised as part of the carrying amount of the related mining asset within property, plant and equipment.This asset is depreciated over the estimated useful life of the mine or asset.Changes in the estimated liability arising from revisions to discount rates, timing or cost estimates are adjusted against the carrying amount of the related asset, or recognised in profit or loss where the asset has been fully depreciated. InventoriesInventories for a mining company comprise, ore stockpiles (including run-of-mine ore), work-in-progress, finished goods (refined metals or concentrates) and consumables and spare parts. Inventories are stated at the lower of cost and net realisable value. Net realisable value represents the estimated selling price in the ordinary course of business less estimated costs of completion and costs necessary to make the sale.The cost of inventories includes all costs incurred in bringing the inventories to their present location and condition, including, direct costs of extraction, including drilling, blasting and hauling, processing costs such as crushing, milling and refining, an allocation of direct and indirect production overheads and depreciation of mining and processing assets. Costs are determined using the weighted average cost method.
| ||||||||||||||||||||||||
|
2 |
Significant accounting judgments, estimates and assumptions | ||||||||||||||||||||||||
|
|
The carrying amounts of certain assets and liabilities are often determined based on estimates and assumptions of future events. The key estimates and assumptions that have a significant risk of causing a material adjustment to the carrying amounts of certain assets and liabilities within the next annual reporting year are: |
|
|
Share-based payment transactions: |
|
|
The Group measures the cost of equity-settled transactions with directors, consultants and employees by reference to the fair value of the equity instruments at the date at which they are granted. The fair value is determined by using a Black and Scholes model which takes into account expected share volatility, strike price, term of the option and the dividend policy. The Company operates an annual incentive scheme for directors and employees approved at its 2024 Annual General Meeting under which awards are linked to movements in the Company’s share price over a defined 12‑month performance period. Where awards may be settled in cash or equity at the discretion of the Board, the awards are accounted for as cash‑settled share‑based payments in accordance with IFRS 2. Cash‑settled share‑based payment liabilities are measured at the fair value of the award at each reporting date, with changes in fair value recognised in profit or loss over the vesting period. The fair value of awards is based on the amount determined under the scheme rules, being the participation rate applied to the excess of the Year End Share Price over the Base Share Price multiplied by the number of shares in issue. Where the Board subsequently determines that settlement will be in equity instruments, the liability is reclassified to equity at the settlement date. |
|
|
Impairment of investments, options and deferred exploration expenditure: |
|
|
|
The Group determines whether investments (including those acquired during the period), options and deferred exploration expenditure are impaired when indicators, based on facts and circumstances, suggest that the carrying amount may exceed its recoverable amount. Such indicators include the point at which a determination is made as to whether or not commercial mining reserves exist in the subsidiary or associate in which the investment is held or whether exploration expenditure capitalised is recoverable by way of future exploitation or sale, obviously pending completion of the exploration activities associated with any specific project in each segment.
|
|
|
|
Fair value of assets and liabilities acquired on acquisition of subsidiaries |
|
|
|
The Group determines the fair value of assets and liabilities acquired on acquisition of subsidiaries by reference to the carrying value at the date of acquisition and by reference to exploration activities undertaken and/or information that the Directors become aware of post acquisition.
Mine decommissioning and rehabilitation The ultimate decommissioning and rehabilitation costs are uncertain, and cost estimates can vary in response to many factors, including estimates of the extent and costs of decommissioning and rehabilitation activities, technological changes, regulatory changes, cost increases as compared to the inflation rates, and changes in discount rates. These uncertainties may result in future actual expenditure differing from the amounts currently provided. Therefore, significant estimates and assumptions are made in determining the provision for mine decommissioning and rehabilitation. As a result, there could be significant adjustments to the provisions established which would affect future financial result. The provision at reporting date represents management’s best estimate of the present value of the future decommissioning and rehabilitation costs required.
|
|
|
|
Investments at fair value through profit and loss (‘Equity investments’) |
|
|
|
Equity investments are initially measured at cost, including transaction costs. At each reporting date, the fair value is assessed and any resultant gains and losses are included directly in the Consolidated Statement of Profit and Loss under IFRS 9.
Valuation of Equity Instruments Convertible Loan (Borrowings) Convertible instruments can be complex, containing a number of features which can have a significant impact on the accounting under IFRS 9 Financial Instruments and IAS 32 Presentation of Financial Instruments. The Company determined that the £700,000 convertible note drawn down announced on 30 June 2022 (“Facility”) (note 12) was an equity instrument as the conversion feature results in the conversion of a fixed amount of stated principal into a fixed number of shares, it satisfies the ‘fixed for fixed’ criterion and, therefore, it is classified as an equity instrument which requires the valuation of theliability component and the equity conversion component. The fair value of the liability component, included in current borrowings, at inception was calculated using a market interest rate for an equivalent instrument without conversion option. The discount rate applied was 25%.
As detailed in Note 12 there have been modifications to the Facility in 2023, 2024 and 2025 and on each occasion the Company has determined that the modifications were in accordance with IFRS 9 substantially different from the pre-existing terms of the Facility and that therefore the equity instrument comprising the pre-existing facility was deemed to be repaid on the date of the modifications.
Classification of acquisitions as asset acquisitions Management applies significant judgment in determining whether an acquisition constitutes a business combination or an asset acquisition under IFRS 3. Key considerations include; whether the acquired set includes substantive processes; the presence (or absence) of outputs; whether the acquired assets are concentrated in a single identifiable asset or group of similar assets; and the stage of development of the project (exploration vs development). In many cases within the mining sector, early-stage exploration entities or mine properties that have been in care and maintenance lack substantive processes and therefore acquisitions are often classified as asset acquisitions. Where treated as an asset acquisition management estimates the fair values of identifiable assets and liabilities to allocate purchase consideration this involves i) judgments in valuing physical assets acquired and there use in the business going forward mineral licences, exploration rights, and geological data, which often rely on limited market data based upon assumptions which may include future operational activities commodity prices, resource potential, and comparable transactions. Changes in these assumptions could result in different allocation of acquisition cost and affect future impairment assessments.
Management has determined that its acquisition of a 90% shareholding in Tsoaxaub Metals (Proprietary) Limited (previously called Namib Lead and Zinc (Proprietary) Limited) (“NLZM”) in December 2025 was an asset acquisition under IFRS 3.This assessment was made on the basis that as at the date of acquisition NLZM had two material assets previously used in relation to lead zinc mining namely the NLZM underground mine and the NLZM Processing Plant. and had been in long term care and maintenance since 2020.Further at acquisition NLZM had no workforce or substantive processes or outputs and the transaction rationale was to acquire and modify the NLZM Processing Plant so that it could be used to process pre-concentrate from the groups Hope and Gorob copper- gold project.The acquisition of NLZM was an arm’s length transaction with a third party for a consideration of £2,078,404 and this amount was allocated to the identifiable assets and liabilities of NLZM that will be used by the group post the acquisition.
Determination of consideration on acquisition of NLZM. As part of the transaction to acquire NLZM the vendor is entitled to Revenue Royalty Payments and Ore Processing payments as follows.The vendor shall be entitled to quarterly royalty payments equal to 1.5% of the Gross Revenue on Hope and Gorob project revenue (the "Revenue Royalty Payments") for each Quarter during the period beginning on the date of acquisitionand ending on, and inclusive of, the twelfth anniversary of the date immediately following the sixty (60)-day period during which the NLZM Plant processes, on an annualized basis, at least 98,000 tonnes of ore ("Commencement Date") (the "Revenue Royalty Period"). The Revenue Royalty Payment is capped at a copper price of US$12,000 per tonne and is due and payable to the Vendor even in an event if the ore from Hope and Gorob project is processed at another facility and not at the NLZM Plant.Once the NLZM Processing Plant is operating the Vendor will be paid a fixed amount for each tonne of ore processed by the NLZM Processing Plant (US$6.50 per tonne for years 1 to 8 after the Commencement Date, US$2.00 per tonne for years 9 to 12 after the Commencement Date and thereafter US$1.00 per tonne) (“Ore Processing Payments”). The ore processing payments are subject to a minimum of i) US$200,000 for the six months immediately following the Commencement Date; and ii) US$25,000 per year for years 1 to 12 after the Commencement Date
The Company assessed that the Revenue Royalty payments are i) contingent on future production; ii) not unavoidable at acquisition date; and iii) linked to future economic activity and the Minimum Ore Processing Payments are dependent upon plant operations. The Company therefore determined that the Revenue Royalty payments and Ore Processing Payments are executory / usage based arrangements dependent on future economic activity not past events so are contingent liabilities and did not form part of the consideration paid in relation to the acquisition of NLZM.
Impairment assessment of mining properties and plant and machinery on acquisition Given the change of purpose of NLZM on acquisition its asset values were assessed for impairment as at the acquisition date and again at subsequent period ends.As the future operation of the NLZM lead zinc mine is dependent on the future development of the Hope and Gorob Project it was fully impaired at the acquisition date.The carrying value of the NLZM Processing Plant and other moveable plant and machinery which will be used in the planned operations of NLZM has not been impaired as its carrying value is less than its assessed value based on a model of NLZM revenue from processing preconcentrate from the Hope and Gorob mine.
Determination of when exploration assets become development assets Determining when EandE assets should be reclassified to mine development assets requires significant judgment. Key factors considered include; completion and results of feasibility studies (pre-feasibility and definitive feasibility studies); evidence of proven and probable reserves; approval of a development plan by the Board; availability of financing to construct the mine; obtaining key regulatory approvals and permits. The timing of this decision is critical as it determines; when amortisation/depreciation begins and when the accounting treatment shifts from IFRS 6 to IAS 16/IAS 36. The assessment of technical feasibility and commercial viability involves significant estimates, including; forecasting commodity prices; estimating capital expenditures and operating costs; estimating expected production profiles and mine life; Discount rates used in economic evaluations; and regulatory and environmental considerations. These estimates directly impact whether development proceeds, the recoverability of capitalised costs and potential impairment charges. Changes in these assumptions could materially affect the carrying value of development assets and the timing of depreciation.
Management has determined that the exploration and evaluation asset in relation to the Hope and Gorob project should be reclassified as a mine development asset.The basis of this assessment was that the Hope and Gorob project has a mining licence, the acquisition of the NLZM Processing Plant for use in the Hope Copper Gold project by the acquisition of NLZM, the results of the Sound Mining Feasibility Study Report summary in relation to the Hope and Gorob project,the signing of a US$7 million financing facility term sheet announced in October 2025 and post year end the announcement on 11 June 2026 of the signing of definitive financing and offtake agreements with Hartree Metals LLC and the decision to commence the development of the Hope and Gorob mine. As at the year end the mine development assets previously recognised as an exploration and evaluation asset was £3,952,000 this asset will be amortised over the life of the mine once mining operations have commenced.No amortization change was recognised in these accounts as mining operations have not yet commenced.
|
|
|
|
|
|
|
Exploration, evaluation and development expenditure |
|
Exploration, evaluation and development expenditure incurred is accumulated in respect of each identifiable area of interest. These costs are only carried forward to the extent that they are expected to be recouped through the successful development of the area or where activities in the area have not yet reached a stage which permits reasonable assessment of the existence of economicallyrecoverable reserves. Accumulated costs in relation to an abandoned area are written off in full in the year in which the decision to abandon the area is made. When production commences, the accumulated costs for the relevant area of interest are transferred to development assets and amortised over the life of the area according to the rate of depletion of the economically recoverable reserves. A regular review is undertaken of each area of interest to determine the appropriateness of continuing to carry forward costs in relation to that area of interest. Costs of site restoration are provided when an obligating event occurs from when exploration commences and are included in the costs of that stage. Site restoration costs include the dismantling and removal of mining plant, equipment and building structures, waste removal and rehabilitation of the site in accordance with clauses of the mining permits. Such costs have been determined using estimates of future costs, current legal requirements and technology on a discounted basis.
|
|
Any changes in the estimates for the costs are accounted for on a prospective basis. In determining the costs of site restoration, there is uncertainty regarding the nature and extent of the restoration due to community expectations and future legislation. Accordingly, the costs have been determined on the basis that the restoration will be completed within one year of abandoning the site.
Reclassification from exploration and evaluation assets to mine development assets Exploration and evaluation (“EandE”) assets are initially capitalised in accordance with IFRS 6. EandE assets are reclassified to mine development assets (within property, plant and equipment or mine properties) when:
Upon reclassification:
Prior to reclassification, EandE assets are not amortised but are assessed for impairment when facts and circumstances suggest that the carrying amount may exceed recoverable amount in accordance with IFRS 6. Following reclassification, the assets are subject to IAS 36 impairment testing. |
|
|
| |
|
3. |
Segment reporting For the purposes of segmental information, the operations of the Group are focused in geographical segments, namely the UK, Namibia, and Botswana, which comprise one class of business: the exploration, evaluation and development of mineral resources and Argentina which is discontinued. The UK is used for the administration of the Group and assessing new projects and includes equity investments in non-group companies. The Group’s loss before tax from continuing operation arose from its operations in the UK, Namibia, and Botswana.
The Group’s loss before tax arose from its operations in the UK, Argentina Namibia and Botswana. | |
|
|
|
|
|
|
|
|
|
| ||||
|
For the six months ended 30 June 2026 - unaudited |
Continuing operations |
Total |
| |||||
|
|
UK |
Botswana |
Namibia |
|
| |||
|
|
£’000 |
£’000 |
£’000 |
£’000 |
| |||
|
Consolidated (loss) / profit before tax |
(1,810) |
- |
(383) |
(2,193) |
| |||
|
Included in the consolidated profit before tax are the following income/(expense) items: |
|
|
|
|
| |||
|
Foreign currency loss |
- |
- |
- |
- |
| |||
|
At 30 June 2026 |
|
|
|
|
| |||
|
Total Assets |
808 |
1,308 |
12,224 |
14,340 |
| |||
|
Total Liabilities |
(4,288) |
- |
(361) |
(4,649) |
| |||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| |||||
|
For the six months ended 30 June 2025 - unaudited |
Continuing operations |
Discontinued |
Total |
| |||||||
|
|
UK |
Botswana |
Namibia |
Argentina |
|
| |||||
|
|
£’000 |
£’000 |
£’000 |
£’000 |
£’000 |
| |||||
|
Consolidated profit before tax |
4,000 |
- |
- |
66 |
4,066 |
| |||||
|
Included in the consolidated profit before tax are the following income/(expense) items: |
|
|
|
|
|
| |||||
|
Foreign currency loss |
- |
- |
- |
- |
- |
| |||||
|
At 30 June 2025 |
|
|
|
|
|
| |||||
|
Total Assets |
6,240 |
1,172 |
3,430 |
- |
10,842 |
| |||||
|
Total Liabilities |
(907) |
- |
- |
- |
(907) |
| |||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
4. |
Operating expenses |
|
|
| ||
|
|
|
Unaudited 6 mths ended 30 June 2026 |
Unaudited 6 mths ended 30 June 2025
| |||
|
|
|
£’000 |
£’000 | |||
|
|
|
|
| |||
|
|
Other operating expenses ** |
1,753 |
344 | |||
|
|
|
|
| |||
|
|
|
1,753 |
344 | |||
|
|
|
|
|
|
|
|
** As detailed in the 2025 Annual Report at the 2024 Annual General Meeting, shareholders approved the establishment of an annual incentive scheme for directors and employees, effective from 30 June 2024, based on improvements in the Company's share price over a 12‑month performance period ending 30 June each year. For the period ended 30 June 2026, a total award of £977K arose under the scheme and has been recognised as a cash-settled share-based payment liability in accordance with IFRS 2.The allocation of this amount among Eligible Participants and the method of settlement (cash or equity) will be determined by the Remuneration Committee and the Board.
|
5. |
Other gains / (losses) |
|
|
|
|
|
Unaudited 6 mths ended 30 June 2026 |
Unaudited 6 mths ended 30 June 2025
|
|
|
|
£’000 |
£’000 |
|
|
Realised (loss) / gain on sale of quoted investments |
(346) |
4,348 |
|
|
|
(346) |
4,348 |
|
|
The fair value gain on the shareholding in ASX listed Blackstone Minerals was based on the market value of Blackstone Mineral shares as at the date of sale and / or the period end compared to their carrying value. The Blackstone Minerals shares were acquired in 2025 as a result of IDM Merger which resulted in the sale of IDM International Ltd to Blackstone Minerals limited (note 7). | ||
|
6. |
Loss per share |
|
|
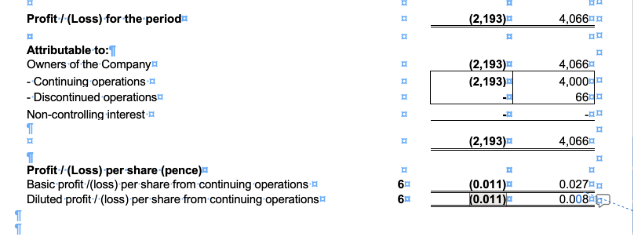
The basic and diluted loss per share for the six months ended 30 June 2026 was 0.011 pence per shares (2025: profit 0.027 pence) and has been calculated using the loss attributable to equity holders of the Company for the sixmonths ended 30 June 2026 of £2,193,000 (2025: profit of £4,066,000).The basic and diluted loss per share was calculated using a weighted average number of shares in issue of 19,238,041,830 (2025: 14,953,536,025).
The diluted loss per share for the six months ended 30 June 2026 was 0.008 pence per share (2025: profit 0.018 pence) and has been calculated using a weighted average number of shares in issue and to be issued of 26,358,695,420 (2025:22,566,802,250). Use of the weighted average number of shares in issue in the period recognises the variations in the number of shares throughout the period and is in accordance with IAS 33 as is the fact that the diluted earnings per share should not show a more favourable position than the basic earnings per share which is why for the six months ended 30 June 2026 the diluted loss per share was (0.011) pence.
|
|
7 |
Investments | ||
|
|
|
Unaudited |
Audited |
|
|
|
30 June 2026 |
31 December 2025 |
|
|
|
£’000 |
£’000 |
|
|
Investments under fair value through profit and loss |
|
|
|
|
Quoted investments at beginning of period |
1,546 |
- |
|
|
Blackstone Minerals shares acquired on IDM Merger |
- |
5,834 |
|
|
Disposals |
(1,199) |
(2,430) |
|
|
(Decrease)/Increase in fair value during period1 |
(347) |
(1,858) |
|
|
Quoted investments at end of period |
- |
1,546 |
|
|
Blackstone Minerals Ltd - Options |
60 |
60 |
|
|
Unquoted investments at end of period |
60 |
60 |
|
|
|
60 |
1,606 |
7.1Acquisition of Tsoaxaub Metals (Proprietary) Limited
On 16 December 2026 completed the acquisition of a 90% shareholding in Tsoaxaub Metals (Proprietary) Limited (previously called Namib Lead and Zinc (Proprietary) Limited) (“NLZM”) and shareholder loans owed by NLZM and the Company has assessed this was an asset acquisition under IFRS 3.This assessment was made on the basis that as at the date of acquisition NLZM had two material assets previously used in relation to lead zinc mining namely the NLZM underground mine and the NLZM Processing Plant. and had been in long term care and maintenance since 2020.Further at acquisition NLZM had no workforce or substantive processes or outputs and the transaction rationale was to acquire and modify the NLZM Processing Plant so that it could be used to process pre-concentrate from the groups Hope and Gorob copper- gold project.The acquisition of NLZM and the shareholder loans was an arm’s length transaction with a third party for a consideration of £2,078,402 and this amount was allocated to the identifiable assets and liabilities of NLZM that will be used by the group post the acquisition.
The consideration of £2,078,402 was allocated to the identifiable assets acquired and liabilities of NLZM assumed based on their relative fair values at the acquisition date:
|
Asset category |
Fair value at acquisition |
|
|
£’000 |
|
Mine and Processing Plant properties |
1,687 |
|
Plant and equipment |
534 |
|
Inventories - Consumables ** |
54 |
|
VAT Refund ** |
18 |
|
Prepayments ** |
4 |
|
Cash ** |
128 |
|
Rehabilitation & Closure provision |
(236) |
|
Decommissioning provision |
(24) |
|
Trade Payables ** |
(2) |
|
Other Payables ** |
(82) |
|
Leave Provision ** |
(3) |
|
Identifiable Assets less liabilities |
2,078 |
|
|
|
** Current assets and liabilities acquired were allocated on their actual value and the balance of the consideration was allocated to the other assets pro rata to this values
|
8. |
Exploration and evaluation assets |
|
|
|
|
|
Unaudited |
Audited |
|
|
|
30 June 2026 |
31 December 2025 |
|
|
|
£’000 |
£’000 |
|
|
|
|
|
|
|
Balance at beginning of period |
1,232 |
4,192 |
|
|
Exploration expenditure |
76 |
992 |
|
|
To Mine Development (see Note 9) |
- |
(3,952) |
|
|
Carried forward at end of period |
1,308 |
1,232 |
|
|
Botswana On 12 February 2021 the Company further to its announcement on 22 December 2020 announced the completion of the acquisition of 100% of Metrock Resources Ltd (“Metrock”) and its manganese mineral exploration licences in Southern Botswana comprising the Kanye Manganese Project (the “Kanye Manganese Project”). The Kanye Manganese Project had historical trenching results thatyielded high grademanganese oxide ("MnO") in boulders. The project area is near the ground of a TSX listed public company, Giyani Metals, which is aiming to become a low-carbon producer of high-purity manganese sulphate monohydrate (HPMSM), a precursor material used by lithium-ion battery manufacturers for the expanding electric vehicle (EV) market. Mineralisation discovered at Kanye occurs at the same stratigraphic level as at the main Giyani Metals K-Hill deposit.
By far the most prospective licence on acquisition was PL 129/2019 and the other licences were acquired as they were available at no additional cost.. The Kanye Manganese Project currently comprises PL 129/2019, as PL 424/2018 has not been renewed (the "Project Licence"), located in south-central Botswana south of the town of Jwaneng and west of the town of Kanye and 150 km by road from the capital Gaborone. The Project License covers a total area of 276 sq. km and provide the holder with the right to prospect for Metals. PL 129/2019 has been renewed to 30 September 2027 and is held by Coastal Minerals Pty Ltd which is 100% owned by Coastal Resources Pty Ltd. itself a 100% owned subsidiary of Bezant Resources.
On 27 August 2024 the Company announced the positive outcome of geophysical surveying at PL 129/2019 which is the main licence at the Kanye manganese project in Botswana. The survey was planned to assist in extending the potential footprint of the deposit discovered by earlier Bezant Resources exploration. Highlights were that:
Previously on 9 February 2023 the Company announced the results of its maiden drilling programme at the Kanye Manganese project the highlights of which were:
Maiden Kanye drilling programme – 11 mainly shallow, angled RC holes totaling 682m at Moshaneng prospect as well as one short diamond drill hole at Loltware prospect. Moshaneng drilling intersected a zone of flat-lying detrital, supergene manganese-iron mineralisation which appears to infill an irregular karst surface over a minimum strike length of 400m. Among assay intervals encountered were: a.6m @ 28.64% MnO from 6m depth in hole MS-RC-12 i.Including 4m @ 35.38% MnO from 8m depth b.3m @ 21.85% MnO from 4m depth in hole MS-RC-06 c.3m @ 21.20% MnO from 2m depth in hole MS-RC-07 Potential for at least another 100m of strike extension to the southeast of holes MS-RC-07 and MS-RC-012 would extend the total strike length to a minimum of 500m Less than 25% of the more than 2km potential extent of the target defined by soil geochemistry has been drill tested. |
|
|
Grades compare favourably with reported grades on neighbouring more advanced manganese projects and therefore the Kanye project warrants detailed evaluation and drilling with a view to establishing the mineral resource potential Drilling at Loltware encountered encouraging manganese enhancement in core, warranting further investigation.
On 24 July 2023 and 6 September 2023 the Company announced the results of a two phase metallurgical testing programme undertaken by Wardell Armstrong International, the highlights of which were:
Phase 2 work followed on from previous metallurgical testing reported in July 2023, aiming to optimise manganese recovery from the ‘Moshaneng’ sample whilst minimising the reagent consumption rates to improve process economics. Sulphuric acid leaching optimisation testwork found that manganese recoveries of 99.5% were achievable at moderate process conditions, specifically 60°C leaching temperature, 300kg/t of sulphur dioxide addition, and 284kg/t of sulphuric acid consumption.
Grind size had minimal influence on the final manganese recovery with 88.0% and 88.3% manganese recovery achieved for feed material particle size distributions of 80% passing 200µm and 80% passing 150µm respectively. Leaching temperature had negligible effect on the final manganese recovery with 88.0% and 89.5% manganese recovery achieved for leach temperatures of 60°C and 90°C respectively. Leach kinetics of manganese recovery were dependent on the sulphur dioxide addition rate. Sulphur dioxide introduced incrementally, demonstrated a staged manganese recovery. A Benchmark Project Review was carried out on three recent manganese projects which were identified as having a similar geographical location and/or producing final products of a similar specification. a.Giyani Metals K.Hill Project Botswana; b.Manganese X Energy Corp. Battery Hill Project Canada; c.Euro Manganese Inc. Chvaletice Project Czech Republic; The Kanye manganese deposit demonstrates an excellent overall manganese recovery using moderate leaching conditions compared with benchmarked projects. The Kanye deposit composite showed a negligible increase in manganese leaching performance at elevated temperatures, which is a favourable outcome from an OPEX perspective. Having established that the Kanye mineralisation is potentially suitable for processing to high purity manganese, the Company will now press on with planning for further exploration at the project to expand the footprint of the deposit and advance towards resource definition. Further metallurgical test work will be considered at a later stage of project advancement.
Post-acquisition acquisition the company’s exploration activities and exploration activities have been very much focused on PL 129/2019and there have been no indications that any impairment provisions are required in relation to the carrying value of the Kanye Manganese Project. During the period the Company continued desk-based technical work and evaluation of the Company’s manganese interests. This work is intended to further refine our geological understanding and assist in defining the most appropriate targets for the next phase of exploration.
Subject to the results of this work and the necessary operational planning, we expect drilling to commence during 2027.
The capitalised cost at 30 June 2026 was £1,308,000 (31 December 2025 was £1,232,000).
|
|
9. |
Mine Development Asset | ||||
|
|
|
Unaudited |
Audited |
| |
|
|
|
30 June 2026 |
31 December 2025 |
| |
|
|
|
£’000 |
£’000 |
| |
|
|
|
|
|
| |
|
|
Brought Forward |
3,952 |
- |
| |
|
|
Additions |
1,560 |
|
| |
|
|
Transferred from exploration and evaluation asset |
- |
3,952 |
| |
|
|
|
5,512 |
3,952 |
| |
|
|
|
|
|
|
|
Management determined that as at 31 December 2025 the exploration and evaluation asset in relation to the Hope and Gorob project should be reclassified as a mine development asset.The basis of this assessment was that the Hope and Gorob project has a mining licence, the acquisition of the Tsoaxaub Metals Processing Plant for use in the Hope Copper Gold project by the acquisition of Tsoaxaub Metals, the results of the Sound Mining Feasibility Study Report summary in relation to the Hope and Gorob project,the signing of a US$7 million financing facility term sheet announced in October 2025 and the announcement on 11 June 2026 of the signing of definitive financing and offtake agreements with Hartree Metals LLC and the decision to commence the development of the Hope and Gorob mine. As at 31 December 2025 the mine development assets previously recognised as an exploration and evaluation asset was £3,952,000 this asset will be amortised over the life of the mine once mining operations have commenced.No amortization change was recognised in these accounts as mining operations have not yet commenced
At 31 December 2025, the Hope and Gorob copper-gold project remained in the development stage and had not yet commenced commercial operations. In accordance with IAS 36, management assessed whether there were any indicators of impairment.Given the project has not yet achieved operational status, a full impairment assessment was performed using a value-in-use model.
The recoverable amount of the mine development assets was determined using a discounted cash flow (DCF) model based on the life-of-mine financial model.
Key assumptions applied in the impairment test include:
- Commodity price (copper): USD 11,500 per tonne, (gold) US$3,500 per oz
- Discount rate (pre-tax): 10%
- Mine operations life: 12 years
- Run of Mine 480,000 tonners per year
- Processing capacity: 180,000 tonnes per annum of pre-concentrate
- Production profile: Based on the current mine plan and processing assumptions
- Operating and capital costs: Based on approved budgets and feasibility studies
The model incorporates management’s best estimates of future economic conditions, production levels, and costs, consistent with externally available market data where applicable. The value-in-use calculation resulted in a positive net present value (NPV) of approximately USD 65 million.
As the recoverable amount exceeds the carrying value of the mine development assets, no impairment charge has been recognised as at 30 June 2026 (31 December 2025 Nil).
Sensitivity Analysis: the impairment assessment is sensitive to changes in key assumptions, particularly:
- Commodity prices (copper and gold)
- Discount rate
- Operating and capital expenditure
- Production volumes and recovery rates
Management performed sensitivity analyses and noted that:
- A decrease in copper or gold prices or increase in discount rate could reduce the headroom.
- There remains sufficient headroom under reasonably possible changes in assumptions, and no reasonably foreseeable scenario results in impairment at the reporting date.
10.Mine and Processing Plant Properties
|
10.1 |
Fixed Mining and Processing Plant |
| |||
|
|
|
Unaudited |
Audited | ||
|
|
|
30 June 2026 |
31 December 2025 | ||
|
|
|
£’000 |
£’000 | ||
|
|
|
|
| ||
|
|
Balance at beginning of year |
1,768 |
- | ||
|
|
Acquired on acquisition of Tsoaxaub Metals (Note 7.1) |
- |
1,687 | ||
|
|
FX gain |
361 |
78 | ||
|
|
Additions post-acquisition |
- |
3 | ||
|
|
Additions during period |
2,669 |
- | ||
|
|
At cost |
4,798 |
1,768 | ||
|
|
Accumulated depreciation |
- |
- | ||
|
|
Carrying value at period end |
4,798 |
1,768 | ||
|
|
|
|
|
|
|
|
10.2 |
Plant and equipment |
| |||
|
|
|
Unaudited |
Audited | ||
|
|
|
30 June 2026 |
31 December 2025 | ||
|
|
|
£’000 |
£’000 | ||
|
|
|
|
| ||
|
|
Balance at beginning of year |
578 |
- | ||
|
|
Acquired on acquisition of Tsoaxaub Metals (Note 7.1) |
- |
534 | ||
|
|
FX gain |
|
26 | ||
|
|
Additions during year |
860 |
19 | ||
|
|
At cost |
1,438 |
579 | ||
|
|
Accumulated depreciation |
(2) |
(1) | ||
|
|
Carrying value at period end |
1,436 |
578 | ||
|
|
|
|
|
|
|
|
11 |
Trade and Other Receivables
| ||
|
|
|
Unaudited |
Audited |
|
|
|
30 June 2026 |
31 December 2025 |
|
|
|
£’000 |
£’000 |
|
|
|
|
|
|
|
Trade Creditors |
1,643 |
417 |
|
|
Other Accruals |
- |
47 |
|
|
Other Creditors |
4 |
- |
|
|
Provision for cash-settled share-based payment liability (Note 4 ) |
977 |
- |
|
|
Balance at period end |
2,624 |
464 |
|
12 |
Borrowings
| ||
|
|
|
Unaudited |
Audited |
|
|
|
30 June 2026 |
31 December 2025 |
|
|
|
£’000 |
£’000 |
|
|
|
|
|
|
|
Convertible loan (Note 12.1) |
620 |
620 |
|
|
Loan (Note 12.2) |
1,139 |
- |
|
|
|
1,759 |
620 |
|
12.1 |
Convertible loan
|
| ||
|
|
|
Unaudited |
Audited | |
|
|
|
30 June 2026 |
31 December 2025 | |
|
|
|
£’000 |
£’000 | |
|
|
|
|
| |
|
|
Balance at beginning of period |
620 |
616 | |
|
|
Convertible loan repaid |
- |
(616) | |
|
|
Borrowings |
- |
700 | |
|
|
Equity allocation |
- |
(193) | |
|
|
Finance charge accrued |
- |
113 | |
|
|
|
620 |
620 | |
|
|
|
|
|
|
As announced on 30 June 2022 the Company further to its announcement of 23 November 2021 confirmed that it had issued two drawdown notices of £350,000 each (“Tranche 1” and “Tranche 2”) for a total amount of £700,000 (the “Drawdowns”) under its £1,000,000 interest free unsecured convertible loan funding facility with Sanderson Capital Partners Ltd (the “Lender”), a long-term shareholder in the Company (the “Facility”). The amount drawdown was interest free and repayable in 12 months or can be converted at any time at the Lender’s option into Bezant shares at fixed prices for Tranche 1 of£350,000, at 0.19 pence per share and for Tranche 2 of £350,000 at 0.225 pence per share. As the conversion feature results in the conversion of a fixed amount of stated principal into a fixed number of shares, it satisfies the ‘fixed for fixed’ criterion and, therefore, it is classified as an equity instrument. The value of the liability component of £546,000 and the equity conversion component of £154,000 were determined at the date of the Drawdowns. The fair value of the liability component, included in current borrowings, at inception was calculated using a market interest rate for an equivalent instrument without conversion option. The discount rate applied was 25%.
Under the terms of the Facility the Lender was due;
i) a drawdown fee of £14,000 being 2% of the amount drawdown which was settled by the issue of 12,522,361 new ordinary shares of £0.00002 each (“Shares”) credited as fully paid at 0.1118 pence per share being the five-day VWAP on 28 June 2022 (the “Drawdown Fee Shares”); and
ii) £350,000 of three year warrants over Shares (the “Warrants”). The exercise price for the Warrants was as follows:
- £175,000 at 0.25 pence per share for the drawdown of Tranche 1; and
- £175,000 at 0.30 pence per share for the drawdown of Tranche 2.
On 15 June 2023, the Company announced, it had by an agreement dated 14 June 2023 agreed with the Lender to;
i)extend the repayment date for the Drawdowns to 23 December 2024 (the “New Repayment Date”);
ii)adjusted the conversion prices of Tranche 1 and Tranche 2 to 0.08 pence per share (the “New Conversion Price”);
iii)the Company has an option to convert all or part of the £700,000 drawdown if the Company’s share price exceeds 0.14 pence (the “Target Conversion Price”) for 10 or more business days; and
iv)the Company as a loan extension fee
a.paid the Lender a £70,000 facility extension and documentation fee equivalent to 6.67% per year which was settled by the issue of 87,500,000 new ordinary shares of 0.002p each (“Shares”) at the New Conversion Price (“Facility Extension Fee Shares”); and
b.issued the Lender 437,500,000 warrants over Shares exercisable at 0.12 pence per Share (the “Warrant Exercise Price”) exercisable for two years from the date of the Agreement (the “Facility Warrants”) (the “Facility Extension Fees”).
(the “2023 Modified Terms”) (the “2023 Modified Facility”) .
The Company determined that the2023Modified Facility was in accordance with IFRS 9 substantially different from the terms of the Facility and that therefore the equity instrument comprising the Facility was deemed to be repaid on 14 June 2023.
On 5 March 2024, the Company announced, it had by an agreement dated 4 March 2024 agreed with the Lender to;
i)extend the repayment date for the Drawdowns to 31 July 2025 (the “2024 FurtherRevised Repayment Date”); and
ii) and adjusted the conversion prices of Tranche 1 and Tranche 2 to 0.06 pence per share (the “2024 Further Revised Conversion Price”)
(the “2024 Modified Terms”) (the “2024 Modified Facility”).
The Company determined that the2024Modified Facility was in accordance with IFRS 9 substantially different from the terms of the 2023 Modified Facility and that therefore the equity instrument comprising the 2023 Modified Facility was deemed to be repaid on 5 March 2024. There was a gain of £28,000 on the settlement of borrowings.
On 27 February 2025 the Company announced that by an agreement dated 26 February 2025 it had agreed with the Lender;
- to extend the repayment date for the Drawdowns to 31 July 2026;
- to reduce the conversion prices of Tranche 1 and Tranche 2 to 0.025 pence per share;
- to extend the expiry date of the Facility Warrants by one year to 14 June 2026; and
- reduce the Target Conversion Price to 0.05 pence per share; and
- the Company may at its sole election prepay the whole or part of the Loan on any day prior to its maturity date upon giving not less than 20 days’ prior written notice to the Lender (“Prepayment Notice”) and paying the Lender a cash premium equal to X where X =25%multiplied by ((the number of daysfrom date of receipt of the Loan to the repayment date) divided by 360).The Company may issue more than one Prepayment Notice. Once a Prepayment Notice has been given the Lender cannot convert that portion of the Loan that the Prepayment Notice relates to.
(the “2025 Modified Terms”) (the “2025 Modified Facility”) .
The Company determined that the2025Modified Facility was in accordance with IFRS 9 substantially different from the terms of the 2024 Modified Facility and that therefore the equity instrument comprising the 2024 Modified Facility was deemed to be repaid on 25 February 2025.
The 2025 Modified Facility is an equity instrument as the conversion feature results in the conversion of a fixed amount of stated principal into a fixed number of shares, so it satisfies the ‘fixed for fixed’ criterion and, therefore, it is classified as an equity instrument which requires the valuation of the liability component and the equity conversion component. The fair value of the liability component, included in current borrowings, at inception was calculated using a market interest rate for an equivalent instrument without conversion option. The discount rate applied was 25%.
On 11 June 2026 the Company announced that by an agreement dated 10 June 2026 it had agreed with the Lender to extend the repayment date for the Drawdowns to 30 September 2027 and to extend the expiry date of the Facility Warrants to 30 June 2028 (the “2026 Modified Facility”).
|
12.2 |
Loan
|
|
| ||
|
|
|
|
| ||
|
|
|
| |||
|
|
|
Unaudited |
Audited |
| |
|
|
|
30 June 2026 |
31 December 2025 |
| |
|
|
|
£’000 |
£’000 |
| |
|
|
|
|
|
| |
|
|
Balance at beginning of period |
- |
- |
| |
|
|
Borrowings ** |
1,126 |
- |
| |
|
|
Finance charge accrued |
5 |
- |
| |
|
|
FX movement |
8 |
- |
| |
|
|
|
1,139 |
- |
| |
|
|
|
|
|
|
|
** On 11 June 2026 the Company announced a US$7 million secured prepayment facility agreement with Hartree Metals LLC (“Hartree Metals”) for the development of the Hope and Gorob Copper Project to support construction of the Hope and Gorob mine site and commissioning activities at the Tsoaxaub Metals Processing Plant in Namibia (“Facility Agreement”).
The Facility Agreement is being made available in five tranches totalling up to US$ 7 million the last of which is payable on pre-production commissioning of the NLZM Processing Plant.The loan is for 4 years, including a 12-month principal and interest repayment grace period, before a straight-line repayment structure. The interest rate is the Secured Overnight Financing Rate and a margin of 4.5% and there is an establishment fee of 1% of the Facility amount.Hartree Metals have the option to elect for all or part of the facility amount to be settled by the issue of Bezant shares at a conversion price of £0.0016 per share. The facility is secured over certain assets of the Hope and Gorob Project including the mine site assets and the Company’s shareholdings in the Hope and Gorob project companies and the Company has given customary warranties for an agreement of this nature.Hartree Metals has also be issued a 4 year warrant with a subscription value of US$1,750,000 with a warrant exercise price of £0.0011 per share which was the closing share price on 30 October 2025 when the financing term sheet was announced, these warrants were issued post the period end but have been included in the warrants in issue at 30 June 2026 in note 13 as the liability to issue them arose during the period.If Hartree Metal’s percentage shareholding increases to 10% then it will have the right to nominate a director to the Board of Bezant for as long as its shareholding equals 10% or more whose appointment would be subject to customary due diligence prior to their appointment.
|
13. |
Share capital |
|
|
|
|
|
Unaudited |
Audited |
|
|
|
30 June 2026 |
31 December 2025 |
|
|
|
£’000 |
£’000 |
|
|
Number |
|
|
|
|
Authorised |
|
|
|
|
5,000,000,000 ordinary shares of 0.002p each |
100 |
100 |
|
|
5,000,000,000 deferred shares of 0.198p each 1 |
9,900 |
9,900 |
|
|
|
10,000 |
10,000 |
|
|
|
|
|
|
|
1The Deferred Shares have very limited rights and are effectively valueless as they have no voting rights and have no rights as to dividends and only very limited rights on a return of capital. The Deferred Shares are not admitted to trading or listed on any stock exchange and are not freely transferable.
| ||
|
|
Allotted ordinary shares, called up and fully paid |
|
|
|
|
As at beginning of the period |
348 |
246 |
|
|
Share subscription for cash |
64 |
56 |
|
|
Shares issued in lieu of directors’ fees |
- |
8 |
|
|
Shares issued on acquisition of 20% of Hope and Gorob |
10 |
- |
|
|
Shares issued to settle consultants fees |
- |
9 |
|
|
Shares issued on exercise of options |
24 |
29 |
|
|
Total ordinary shares at end of period |
446 |
348 |
|
|
|
|
|
|
|
Allotted deferred shares, called up and fully paid (2) |
|
|
|
|
As at beginning of the period |
1,978 |
1,978 |
|
|
Total deferred shares at end of period |
1,978 |
1,978 |
|
|
Ordinary and deferred as at end of period |
2,424 |
2,224 |
|
|
|
Number of shares 30 June 2026 |
Number of shares 31 December 2025 |
|
|
|
Ordinary share capital is summarised below: |
|
|
|
|
|
As at beginning of the year |
17,426,654,126 |
12,304,059,682 |
|
|
|
Share subscription for cash (1) |
3,184,615,386 |
2,800,000,000 |
|
|
|
Shares issued to settle Directors’ and PDMR fees |
- |
410,719,998 |
|
|
|
Shares issued on acquisition of 20% of Hope and Gorob (2) |
515,263,645 |
- |
|
|
|
Shares issued to settle consultants’ fees (3) |
11,024,015 |
440,874,446 |
|
|
|
Shares issued on exercise of warrants |
1,201,115,385 |
1,471,000,000 |
|
|
|
As at end of period |
22,338,672,557 |
17,426,654,126 | |
|
|
|
|
| |
|
|
Deferred share capital is summarised below: |
|
|
|
|
|
As at beginning of the year (1) |
998,773,038 |
998,773,038 |
|
|
|
As at end of period |
998,773,038 |
998,773,038 |
|
|
|
|
|
|
|
|
|
Notes re shares issued during the year (1) On 31 March 2026 the Company issued 3,184,615,386 shares in relation to a placement raising £2,070,000. (2) On 24 March 2026 the Company issued 515,263,645 shares to settle £557,000 related to the acquisition of 20% of Hope and Gorob. (3) On 31 March 2026 the Company issued 11,024,015 shares to settle fees due to Consultants of £7,166.
|
| ||
|
|
|
|
|
|
|
|
|
Unaudited |
Audited |
|
|
|
30 June 2026 |
31 December 2025 |
|
|
|
£’000 |
£’000 |
|
|
The share premium was as follows: |
|
|
|
|
As at beginning of period |
42,711 |
41,663 |
|
|
Share subscription for cash |
2,006 |
504 |
|
|
Shares issued to settle consultants fees |
7 |
116 |
|
|
Shares issued on acquisition of 20% of Hope and Gorob |
547 |
- |
|
|
Shares issued to settle Directors’ and PDMR fees |
- |
115 |
|
|
Share issue costs |
(1,457) |
(275) |
|
|
Warrants exercised during the period |
699 |
588 |
|
|
As at end of year |
44,513 |
42,711 |
|
|
Each fully paid ordinary share carries the right to one vote at a meeting of the Company. Holders of ordinary shares also have the right to receive dividends and to participate in the proceeds from sale of all surplus assets in proportion to the total shares issued in the event of the Company winding up. |
|
14. |
Share-based payments
|
|
At the period end, the Company had the following share-based payment plans involving equity settled share options and warrants in existence:
Share Options
|
Number |
Date granted |
Exercise price |
Maximum term |
Vesting dates |
|
35,000,000 |
23/08/2018 |
0.500p |
Expire on 21/06/2028 |
23 August 2018 |
|
25,000,000 |
23/08/2018 |
1.000p |
Expire on 21/06/2028 |
31 January 2019 |
|
110,000,000 |
06/11/2020 |
0.425p |
Expire on 21/06/2028 |
Upon being granted |
|
110,000,000 |
06/11/2020 |
0.565p |
Expire on 21/06/2028 |
31 March 2021 |
|
223,750,000 |
15/03/2024 |
0.060p |
Expire on 21/06/2028 |
15 March 2024 |
|
223,750,000 |
15/03/2024 |
0.080p |
Expire on 21/06/2028 |
15 March 2024 |
|
385,500,000 |
3/03/20260 |
0.165p |
Expire on 21/06/2028 |
24 June 2026 |
|
385,500,000 |
3/03/2026 |
0.165p |
Expire on 21/06/2028 |
** |
|
1,498,500,000 |
|
|
|
|
** Vest upon the first sale of concentrate from ore mined at the Hope and Gorob mine or on a
change of control and / or sale of the Hope and Gorob project
Warrants
|
Number |
Date granted |
Exercise price |
Maximum term |
Vesting dates |
|
31,600,000 |
18/12/2023 |
0.025p |
Expire on 18/12/2026 |
Upon being granted |
|
1,878,500,000 |
18/12/2023 |
0.060p |
Expire on 18/12/2026 |
Upon being granted |
|
1,859,000,000 |
03/01/2025 |
0.040p |
Expire on 03/01/2028 |
Upon being granted |
|
437,500,000 |
24/06/2023 |
0.120p |
Expire on 30/06/2028 |
Upon being granted |
|
350,000,000 |
16/12/2025 |
0.058p |
Expire on 30/11/2026 |
Upon being granted |
|
3,184,615,386 |
8/04/2026 |
0.165p |
Expire on 08/04/2029 |
Upon being granted |
|
1,189,286,904 |
10/06/2026 |
0.110p |
Expire on 11/06/ 2030 |
Upon being granted |
|
8,930,502,290 |
|
|
|
|
The number and weighted average exercise prices of the above options and warrants are as follows:
|
|
30 June 2026 |
31 December 2025 |
| |||
|
|
Number |
Weighted average exercise price |
Number |
Weighted average exercise price | ||
|
Outstanding at beginning of period |
6,300,600,000 |
0.083p |
5,214,308,333 |
0.15p | ||
|
Share options issued (1) |
771,000,000 |
0.165p |
- |
- | ||
|
Lapsed/exercised warrants |
(1,201,115,385) |
0.060p |
(2,606,208,333) |
0.038p | ||
|
Warrants issued |
4,558,517,675 |
0.147p |
3,692,500,000 |
0.043p | ||
|
Outstanding at end of year |
10,429,002,290 |
0.115p |
6,300,600,000 |
0.083p | ||
|
|
|
|
|
|
|
|
|
15. |
Reconciliation of operating loss to net cash outflow from operating activities |
|
|
|
|
|
Unaudited |
Unaudited |
|
|
|
Six months ended 30 June 2026 |
Six months ended 30 June 2025 |
|
|
|
£’000 |
£’000 |
|
|
|
|
|
|
|
Operating profit/(loss) from all operations |
(1,753) |
(343) |
|
|
|
|
|
|
|
|
|
|
|
|
Share based payment liability (note 4) |
977 |
- |
|
|
Foreign exchange movement |
50 |
(21) |
|
|
Shares issued – Directors fees |
- |
87 |
|
|
Share issued - Consultants |
7 |
153 |
|
|
(Increase)/decrease in receivables |
(361) |
22 |
|
|
Increase/(decrease) in payables |
1,343 |
(78) |
|
|
Net cash outflow from operating activities |
263 |
(188) |
|
16. |
Subsequent events |
|
|
Subsequent to 30 June 2026, the Group has reported significant progress in the development and commissioning of the Hope and Gorob mine and Tsaoxaub Metals processing plant, including successful blasting operations, ore stockpiling, ongoing plant commissioning and management's expectation that first run-of-mine ore would be processed and first concentrate produced during September 2026. Management also announced that it was reviewing a Phase II expansion strategy and believes the project has the potential to support an estimated mine life of approximately 35 years, although no revised economic model has yet been published.
On 27 August 2026, the Group entered into revised arrangements relating to the acquisition of the Tsaoxaub Metals Processing Plant (formerly the NLZM Processing Plant). Under the accelerated purchase arrangement, a payment of US$5.0 million is due by 31 October 2026, following which the vendor's security over the asset will be released. A further US$4.98 million is payable in quarterly instalments from March 2029 to December 2031 which the Company plans to pay from operating cashflow. The vendor has also been granted an option to convert up to £2.0 million of the deferred consideration into ordinary shares of the Company at a fixed conversion price of £0.0013145 per share. The amount of the Deferred Consideration being settled will be based on the present value of the Deferred Consideration being settled discounted at 12.5% per year from its original payment date (the “Discount”). Any Conversion Shares, when issued, will be subject to a two month lock up.
On 2 September 2026, the Group announced that it had entered into a co-investment agreement with Hartree Metals LLC under which Hartree will provide the US$5.0 million funding required under the accelerated purchase arrangement. In consideration, Hartree will receive security together with royalty and ore-processing payment rights based on the terms of the security arrangements and Revenue Royalty granted to CL US Minerals LLC in accordance with the terms and conditions of the Share Purchase Agreement details of which were announced on 14 August 2025
Subsequent to the reporting date, the Company issued additional ordinary shares following the exercise of warrants and share options and the settlement of certain consultancy fees through the issue of equity. From 1st July 2026 to and 28 September 2026, the Company has announced the issue of a total of 500,852,531 new ordinary share, following these share issued, the Company's issued share capital will have increased to 22,839,525,088 ordinary shares
The Directors have considered the above events and concluded that they are non-adjusting events under IAS 10 as they relate to conditions arising after 30 June 2026. Accordingly, no adjustment has been made to the amounts recognised in these interim financial statement
|
|
17. |
Availability of Interim Report |
|
|
A copy of these interim results will be available from the Company’s registered office during normal business hours on any weekday at Floor 6, Quadrant House, 4 Thomas More Square, London E1W 1YW and can also be downloaded from the Company’s website at www.bezantresources.com. Bezant Resources Plc is registered in England and Wales with company number 02918391. |
This information is provided by RNS, the news service of the London Stock Exchange. RNS is approved by the Financial Conduct Authority to act as a Primary Information Provider in the United Kingdom. Terms and conditions relating to the use and distribution of this information may apply. For further information, please contact rns@lseg.com or visit www.rns.com.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.
ENDRNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.