
Interim Results for the six months ended 30 June

Princes Group PLC
15 September 2026
NOT FOR RELEASE, PUBLICATION OR DISTRIBUTION, IN WHOLE OR PART, DIRECTLY OR INDIRECTLY, IN OR INTO OR FROM ANY JURISDICTION WHERE SUCH DISTRIBUTION WOULD BE UNLAWFUL.
15 September 2026
PRINCES GROUP PLC
("Princes Group", the "Group" or the "Company")
Interim results for the six months ended 30 June 2026
Princes Group plc (LSE: PRN), a leading international platform in the United Kingdom and European food and beverage sector, today announces its interim results for the six months ended 30 June 2026.
Financial summary:
|
KPI |
H1 2026 |
H1 2025 |
Change (%) |
|
Revenue |
£999.4 million |
£933.3 million |
+7% |
|
Adjusted EBITDA |
£79.3 million |
£73.8 million |
+7% |
|
Adjusted EBITDA margin |
7.9% |
7.9% |
Unchanged |
|
Profit before taxation |
£39.2 million |
£24.2 million |
+62% |
|
Underlying Free Cash Flow |
£90.1 million |
£75.3 million |
+20% |
|
Free Cash Flow Conversion |
115.3% |
105.5% |
+9.8% |
|
ROCE |
12.2% |
11.6% |
+60bps |
|
Net cash |
£374 million |
£311 million |
+20% |
Financial highlights
· Revenue growth of 7%
o Reflecting contribution from recent acquisition
o Strong double digit percentage revenue growth in Italian and Oils business units, along with moderate growth achieved in Foods
· Adjusted EBITDA margins were resilient, unchanged at 7.9%
· Free cash flow conversion of 115.3%, reflecting improved strong generation of £90.1m
· ROCE remained strong at 12.2%
· Net cash position grew to £374m, driven by the company's strong FCF generation
Strategic & Operational highlights
· Commercial momentum remained strong during the first half, with the Group securing new customer wins and expanding distribution across a number of key markets and categories.
· Continued investment in brands and innovation pipeline, while increasingly leveraging its broader commercial and manufacturing platform to unlock new growth opportunities.
· Immediate integration benefits from Plasmon acquisition - successfully insourced baby and medical pasta production at Ozzano, which will deliver a 30% reduction in Cost of Goods Sold and over €1.5 million of fixed-cost absorption, with further insourcing initiatives planned for H2.
· Leveraging the Group's expanded route-to-market, with 11 Princes Tuna SKUs launched across the Carrefour Italia retail network
· Further international customer wins and distribution expansion, including a doubling of customer own-brand tuna business with Carrefour France, a new Princes branded listing with Lidl Netherlands and new tomato business with Rewe Poland
· Identified c.£2 million of additional operational efficiencies, with implementation underway. Delivery of the synergy programme remains on track.
Giuseppe Mastrolia, Interim CEO of Princes Group, commented:
"I am pleased with the performance delivered by Princes Group during the first half of the year. Against a challenging macroeconomic backdrop and significant inflationary pressures across a number of our key input costs, we have demonstrated the resilience of our business model and, importantly, our ability to protect profitability through disciplined commercial management and continued focus on operational efficiency.
Since taking on the role of Interim CEO in July 2026, I have been working closely with the leadership team to identify opportunities to further strengthen performance across the Group. Our focus is on faster execution, greater accountability and commercial ownership, alongside improving the efficiency of our manufacturing network and disciplined allocation of capital and resources. Our objective is clear: to translate Princes' considerable capabilities into stronger growth, profitability and cash generation.
At the same time, M&A remains a fundamental pillar of our growth strategy. Our strong balance sheet, extensive manufacturing footprint and proven ability to integrate businesses position Princes exceptionally well to participate in the consolidation of the European food and beverage sector. We continue to actively evaluate a strong pipeline of opportunities and will remain disciplined in our approach, while being prepared to move decisively where we see the right strategic and financial fit.
We enter the second half with a clear plan and a strong sense of urgency. There is considerably more value to unlock across Princes and I am confident in our ability to deliver it. Our priority is not simply to set ambitious targets, but to achieve them - through disciplined execution, faster decision-making and an unwavering focus on delivering tangible results for our customers and shareholders."
M&A and Capital allocation
The Group continues to actively assess a broad and expanding range of M&A opportunities, applying a disciplined approach focused on strategic fit and value creation. The Group has made significant progress on a number of opportunities within its pipeline and is currently in advanced negotiations in relation to two potential acquisitions. Based on the current pipeline, Management anticipates completing at least one transaction over the coming months, subject to the successful conclusion of negotiations, execution of definitive agreements and any required approvals. With a strong balance sheet and net cash position, the Group is well positioned to fund attractive acquisition opportunities from existing resources while maintaining financial flexibility.
Outlook
Trading momentum strengthened during the second quarter, with performance ahead of Q1. Fish continues to deliver positive volume momentum, although revenues were impacted by lower raw tuna prices. The drinks segment was impacted by a focus on maintenance and reorganisation activities. The Group continued to demonstrate strong margin resilience despite ongoing inflationary pressures, alongside good cash generation.
The first half was impacted by the timing of CPI pass-through, with the majority of agreed price increases effective from 1 July and the resulting benefit expected to be reflected in Q3 and Q4. The increased flexibility embedded across the business over the past year has enabled the Group to manage the timing lag without a significant impact on margins. Princes remains well positioned for the remainder of the year and continues to trade in line with Management's expectations for FY26. The Group benefits from a strong financial position, a diversified portfolio of leading brands and customer own-brand products, and long-standing relationships with major customers across its markets.
Looking ahead, Management remains firmly focused on delivering tangible results through disciplined execution of its strategic priorities, while continuing to pursue opportunities for organic growth and actively evaluating value-accretive M&A opportunities.
Results presentation live webcast - today, 15 September at 8:30 a.m. BST
A live webcast of the presentation including Q&A will be held today at 8:30am BST for investors and analysts and will be available via our website at https://www.princesgroupinvestors.com/ or on https://brrmedia.news/PRN_HY26. This will be available for playback after the event.
The supporting presentation will be made available on the Group's website ahead of the webcast.
Enquiries
For further information, please contact:
|
Princes Group plc |
|
|
Benedetta Mastrolia, Investor Relations Director |
|
|
Barabino and Partners UK (Financial PR communications) |
+44 (0) 7542846844 |
|
Georgia Colkin / Caroline Merrell |
+44 (0)7852 210329 |
Princes Group plc
Princes Group is a leading international platform in the United Kingdom and European food and beverage sector. The Group operates across five business units: Foods, Fish, Italian, Oils, and Drinks and holds leading positions in both branded and customer own brand products.
The Group's branded portfolio includes well-known, trusted brands such as Princes, Napolina, Branston, Batchelors, Flora, Crisp 'N Dry, Delverde, Plasmon, Naked Noodle, and Vier Diamanten.
By combining industrial expertise with long-standing supply partnerships, Princes Group is a trusted partner to a diverse range of blue-chip customers, including major food retailers, B2B partners, and the foodservice industry, reaching over 8,000 clients globally and exporting to more than 60 countries.
Headquartered in Liverpool, UK, Princes Group generated £1.92 bn pro forma revenues in the year ended 31 December 2025, employs approximately 7,800 people and operates 24 production facilities across the United Kingdom, continental Europe, and Mauritius, supported by 21 warehouses and distribution centres and three offices in the UK, Poland, and the Netherlands.
With a strong production network, the Group is well-positioned for future growth, consistently delivering quality, innovation, and reliable supply across multiple categories, while upholding its commitment to excellence and long-term customer relationships.
For more information, visit www.princesgroup.com.
Financial Review
The Group continued to execute its strategy focusing on margin-accretive growth, operational discipline and cash generation.
Reported revenue increased 7% versus H1 2025 to £999.4 million, reflecting the contribution from recent acquisitions, including Princes France S.A.S., Newlat GmbH and Plasmon.
The Group's H1 topline performance reflected the normal seasonal profile of the food and beverage sector, with softer volumes in the early part of the year following the festive period, alongside typical retailer inventory optimisation dynamics.
The Group delivered resilient trading across the majority of its core categories during the period, with positive momentum in Oils and particularly strong growth in Italian Products, supported by the integration of additional businesses, including Plasmon. Fish continues to deliver positive volume momentum, although revenues were impacted by lower raw tuna prices. The drinks segment was impacted by a focus on maintenance and reorganisation activities.
Performance in Foods has been impacted by reduced trading across some of the product categories but we continue to review the portfolio to ensure commercial, operational and procurement initiatives improve the long term profitability of this segment.
Adj. EBITDA increased 7.5% to £79.3 million against H1 2025, driven by improved operational leverage, synergy delivery and continued cost discipline.
Adj. EBITDA margin remained at 7.9%, in line with H1 2025. The underlying expansion was largely driven by the Italian segment, reflecting continued operational discipline as well as the contribution of recent acquisitions. This improvement was primarily offset by the phasing impact of the timing of inflationary cost movements and volume phasing to deliver a static margin compared to H1 2025.
Underlying Free Cash Flow generation remained strong at £90.1 million, implying an outstanding FCF conversion of 115.3% and reflecting sustained working capital discipline, procurement optimisation and continued focus on cash conversion across the Group.
The Group further strengthened its balance sheet and liquidity profile during the quarter, reporting a Net cash position of £374m (£481m excluding IFRS 16 liabilities), compared with net cash of £311m on 31 December 2025 (£395m excluding IFRS 16 liabilities). The continued increase in net cash reflects the Group's highly cash generative operating model, disciplined capital allocation and resilient underlying trading performance.
|
6M 2026 Revenue by Business Unit |
|
||||||
|
6 months ended 30 June 2026 |
6 months ended 30 June 2025 |
YoY change (%) |
|||||
|
|
£'000 |
£'000 |
£'000 |
||||
|
|
|||||||
|
Foods |
305,074 |
303,249 |
0.6% |
||||
|
Drinks |
142,997 |
157,178 |
-9.0% |
||||
|
Fish |
178,346 |
183,511 |
-2.8% |
||||
|
Italian Products |
227,304 |
153,498 |
48.1% |
||||
|
Oils |
145,701 |
135,912 |
7.2% |
||||
|
Group total |
999,422 |
933,348 |
7.1% |
||||
|
|
|||||||
|
6M 2026 Revenue by Country |
|
6 months ended 30 June 2026 |
6 months ended 30 June 2025 |
YoY change (%) |
|||||
|
|
£'000 |
£'000 |
£'000 |
||||
|
|
|||||||
|
UK |
665,718 |
681,126 |
-2.3% |
||||
|
Italy |
103,432 |
50,618 |
104.3% |
||||
|
Germany |
59,928 |
39,475 |
51.8% |
||||
|
Other countries |
170,344 |
162,129 |
5.1% |
||||
|
999,422 |
933,348 |
7.1% |
|||||
|
|
|
|
|||||
|
6M 2026 Revenue by Channel |
|
6 months ended 30 June 2026 |
6 months ended 30 June 2025 |
YoY change (%) |
||||||
|
|
£'000 |
£'000 |
£'000 |
|||||
|
|
||||||||
|
Large food retailers |
809,983 |
754,855 |
7.3% |
|||||
|
B2B partners |
119,567 |
111,805 |
6.9% |
|||||
|
Food services |
69,872 |
66,688 |
4.8% |
|||||
|
999,422 |
933,348 |
7.1% |
||||||
|
6M 2026 Adj. EBITDA and Adj. EBITDA margin by Business Unit |
||||||||
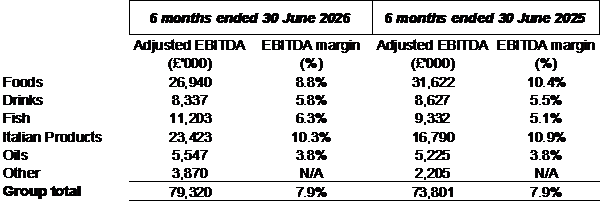
In line with the parent company reporting, Adjusted EBITDA has been updated in H1 2026 to align by including non-controlling interests.
Foods
Revenue has increased year on year by 0.6% to £305 million, driven by the inclusion of perimeter acquisitions. Adjusted EBITDA decreased by 14.8% to £26.9 million and EBITDA percentage reduced by 160 bps. This is due to lower trading in core UK categories, along with increased input costs, that had not been fully passed onto customers in the period.
Drinks
Revenue has decreased year on year by 9.0% which reflects deflationary price fluctuation on key commodities. Adjusted EBITDA however year on year is broadly flat, reporting a 3.4% decrease due to input costs, that had not been fully passed onto customers in the period.
Fish
Revenue has decreased year on year by 2.8% driven by a phasing variation for Frozen fish sales. Adjusted EBITDA increased by 20.0% delivered mainly through factory operational optimisation year on year.
Italian Products
Revenue has increased year on year by 48.1%, driven by the inclusion of perimeter acquisition sales. This has also resulted in a 39.5% increase in Adjusted EBITDA. On a like-for-like basis, revenue reflected lower raw material costs, particularly durum wheat, which resulted in lower average selling prices for pasta.
Oils
Revenue has increased year on year by 7.2% driven by improved sales in the Polish market. Adjusted EBITDA has increased by 6.2% year on year, due to the improved sales. On a like-for-like basis, revenue reflected lower oil costs and the resulting reduction in average selling prices.
Operating Review
Recent and upcoming commercial and new product development initiatives launched in H1 include:
· Continued commercial momentum across the UK portfolio, with new distribution gains for Princes fruit and meat across Tesco and Asda, Branston across Sainsbury's, and Princes Jack Mackerel across Morrisons and Asda. Princes also launched its new Ocean Select tuna range in Tesco, alongside the transition of Princes branded tuna to 100% MSC-certified products.
· Successful relaunch of the Mug Shot sachet range, supported by new positioning, refreshed packaging, product optimisation and a high-impact consumer campaign reaching approximately 4 million consumers. Early performance has been encouraging, with an average 9% uplift in rate of sale across key lines and purchase intent of 83%.
· Continued investment behind Napolina, including the launch of flavoured oils, increased promotional support for the oils portfolio and new listings for Napolina sauces in Tesco and pasta in Asda. The innovation pipeline includes new flavour boosters, Polpa and black beans, alongside further launches across pasta and sauces.
· Strong innovation pipeline for H2, including a major relaunch of the Naked core range following extensive product development and consumer testing. The improved range features enhanced recipes, longer noodles and new flavour sachets, with testing showing significant improvements across purchase intent, taste and consumer appeal.
· Good progress in Baby and Medical Food, with Plasmon regaining category leadership against its main competitor and a new promotional strategy driving market share gains across wet baby food and biscuits. The Group also successfully insourced baby and medical pasta production at Ozzano, which will deliver a 30% reduction in COGS and over €1.5 million of fixed-cost absorption, with further insourcing initiatives planned for H2.
· Leveraging the Group's expanded route-to-market, with 11 Princes Tuna SKUs launched across the Carrefour Italia retail network in Italy from the end of June, supported by dedicated retail media. Further activity is planned to support the development of Princes within the Italian market.
· Continued innovation across the Italian bakery portfolio, with Princes bread substitutes delivering strong performance and the relaunch of Delverde Crostino Dorato supported by advertising and promotional investment. Growth in rusks was supported by the launch of Granfetta Benefit, with further distribution expansion and six new Delverde snack SKUs planned for H2.
· Further international customer wins and distribution expansion, including a doubling of customer own-brand tuna business with a major French retailer, a new Princes branded listing with Lidl Netherlands and new tomato business in Poland. The H2 pipeline includes successful customer own-brand tuna tenders with a major retailer in the Netherlands and in Poland, as well as further tomato wins with several German retailers and discounters.
From an operations standpoint, the Group has identified c.£2 million of additional operational efficiencies, with implementation underway. Delivery of the synergy programme remains on track, although benefits achieved during the period were partially offset by commodity price volatility and higher transportation costs.
Our Principal Risks and Uncertainties
The delivery of our strategic objectives is dependent on effective risk management. Details of the principal risks facing the Group at an operational level were included on pages 50 to 55 of the Group's Annual Report and Accounts for the year ended 31 December 2025, as part of the Strategic Report.
We have reassessed our principal risks for the remaining 6 months of the financial year as the world continues to face political and economic turmoil.
Volatile commodity prices continue to create financial pressure and operational complexity across our portfolio. In response, the Group have strengthened risk monitoring and maintained robust procurement strategies.
Cyber-attack threats have also increased amid geopolitical tensions, and the Group remain alert to the heightened risk of IT security breaches and cyber-based attacks.
Going Concern
After making enquiries, the directors have a reasonable expectation that the Group has adequate resources to continue in operational existence to the end of the 2027 financial year. For this reason, they continue to adopt the going concern basis in preparing the Condensed Consolidated Interim Financial Statements.
Statement of directors' responsibilities
The half year results announcement complies with the Disclosure and Transparency Rules ('the DTR') and the UK's Financial Conduct Authority in respect of the requirement to produce a half yearly financial report.
The directors confirm that to the best of their knowledge:
· this financial information has been prepared in accordance with UK adopted International Accounting Standard 34 'Interim Financial Reporting';
· the Half Year Results Announcement includes a fair review of the important events that have occurred during the 6 months to 30 June 2026 and their impact on the financial information, and a description of the principal risks and uncertainties for the remaining 6 month period of the financial year as required by DTR4.2.7;
· the Half Year Results Announcement includes a fair review of material related party transactions and changes therein since the last annual report as required by DTR4.2.8.
On behalf of the Board
Fabio Fazzari
Chief Financial Officer
14 September 2026
Independent Review Report to Princes Group Plc
Report on the condensed consolidated interim financial statements
Our conclusion
We have reviewed Princes Group Plc's condensed consolidated interim financial statements (the "interim financial statements") in the Half Year Results Announcement of Princes Group Plc for the 6 month period ended 30 June 2026 (the "period").
Based on our review, nothing has come to our attention that causes us to believe that the interim financial statements are not prepared, in all material respects, in accordance with UK adopted International Accounting Standard 34, 'Interim Financial Reporting' and the Disclosure Guidance and Transparency Rules sourcebook of the United Kingdom's Financial Conduct Authority.
The interim financial statements comprise:
● the Condensed Consolidated Statement of Financial Position as at 30 June 2026;
● the Condensed Consolidated Income Statement for the period then ended;
● the Condensed Consolidated Statement of Comprehensive Income for the period then ended;
● the Condensed Consolidated Cash Flow Statement for the period then ended;
● the Condensed Consolidated Statement of Changes in Equity for the period then ended; and
● the explanatory notes to the interim financial statements.
The interim financial statements included in the Half Year Results Announcement of Princes Group Plc have been prepared in accordance with UK adopted International Accounting Standard 34, 'Interim Financial Reporting' and the Disclosure Guidance and Transparency Rules sourcebook of the United Kingdom's Financial Conduct Authority.
Basis for conclusion
We conducted our review in accordance with International Standard on Review Engagements (UK) 2410, 'Review of Interim Financial Information Performed by the Independent Auditor of the Entity' issued by the Financial Reporting Council for use in the United Kingdom ("ISRE (UK) 2410"). A review of interim financial information consists of making enquiries, primarily of persons responsible for financial and accounting matters, and applying analytical and other review procedures.
A review is substantially less in scope than an audit conducted in accordance with International Standards on Auditing (UK) and, consequently, does not enable us to obtain assurance that we would become aware of all significant matters that might be identified in an audit. Accordingly, we do not express an audit opinion.
We have read the other information contained in the Half Year Results Announcement and considered whether it contains any apparent misstatements or material inconsistencies with the information in the interim financial statements.
Conclusions relating to going concern
Based on our review procedures, which are less extensive than those performed in an audit as described in the Basis for conclusion section of this report, nothing has come to our attention to suggest that the directors have inappropriately adopted the going concern basis of accounting or that the directors have identified material uncertainties relating to going concern that are not appropriately disclosed. This conclusion is based on the review procedures performed in accordance with ISRE (UK) 2410. However, future events or conditions may cause the group to cease to continue as a going concern.
Responsibilities for the interim financial statements and the review
Our responsibilities and those of the directors
The Half Year Results Announcement, including the interim financial statements, is the responsibility of, and has been approved by the directors. The directors are responsible for preparing the Half Year Results Announcement in accordance with the Disclosure Guidance and Transparency Rules sourcebook of the United Kingdom's Financial Conduct Authority. In preparing the Half Year Results Announcement, including the interim financial statements, the directors are responsible for assessing the group's ability to continue as a going concern, disclosing, as applicable, matters related to going concern and using the going concern basis of accounting unless the directors either intend to liquidate the group or to cease operations, or have no realistic alternative but to do so.
Our responsibility is to express a conclusion on the interim financial statements in the Half Year Results Announcement based on our review. Our conclusion, including our Conclusions relating to going concern, is based on procedures that are less extensive than audit procedures, as described in the Basis for conclusion paragraph of this report.
Use of this report
This report, including the conclusion, has been prepared for and only for the company for the purpose of complying with the Disclosure Guidance and Transparency Rules sourcebook of the United Kingdom's Financial Conduct Authority and for no other purpose. We do not, in giving this conclusion, accept or assume responsibility for any other purpose or to any other person to whom this report is shown or into whose hands it may come save where expressly agreed by our prior consent in writing.
PricewaterhouseCoopers LLP
Chartered Accountants
Manchester
14 September 2026
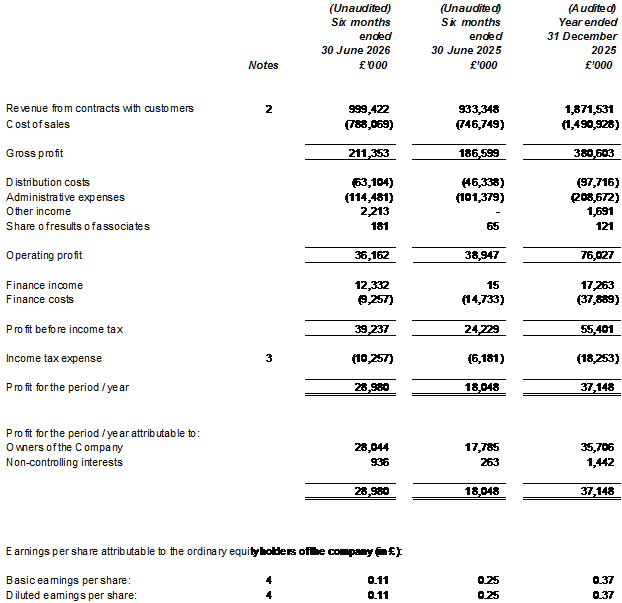
Condensed Consolidated Income Statement
For the six-month period ended 30 June 2026
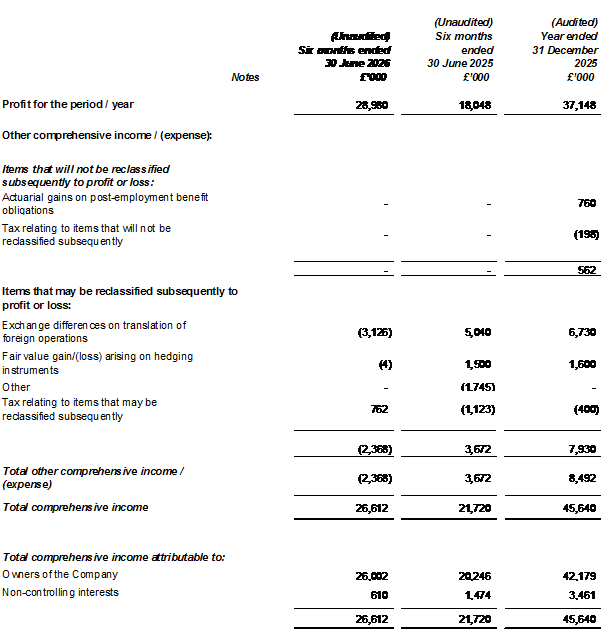
Condensed Consolidated Statement of Comprehensive Income
Condensed Consolidated Statement of Financial Position
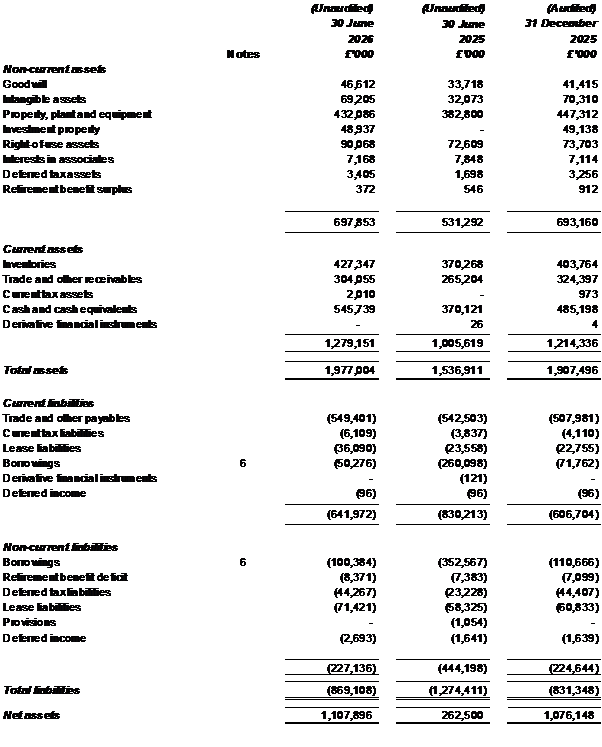
Condensed Consolidated Statement of Financial Position (continued)
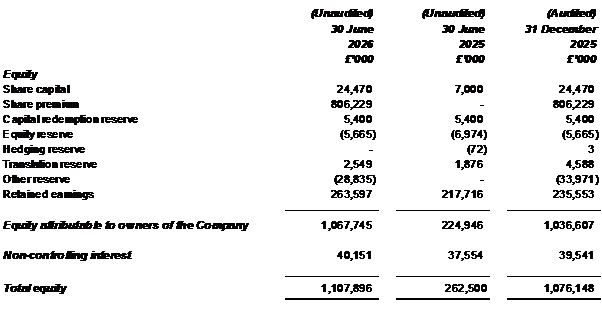
Condensed Consolidated Statement of Changes in Equity
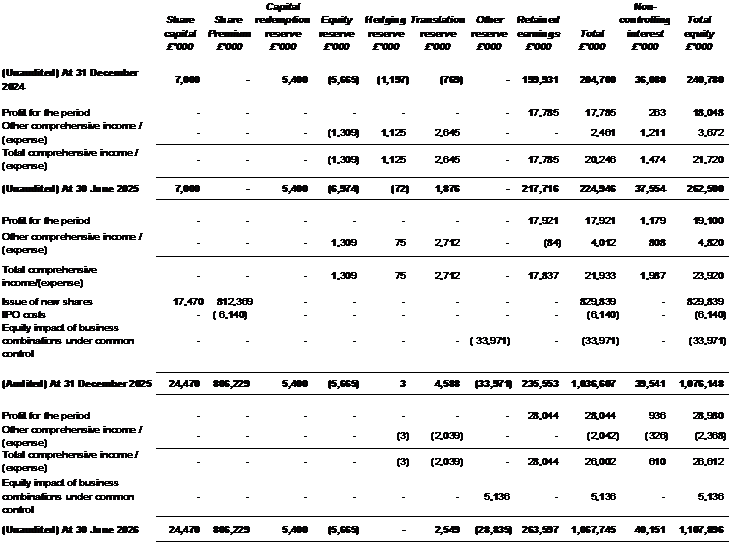
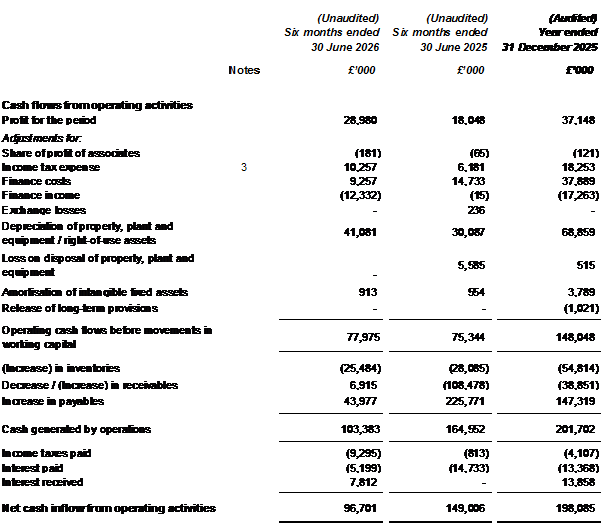
Condensed Consolidated Cash Flow Statement.
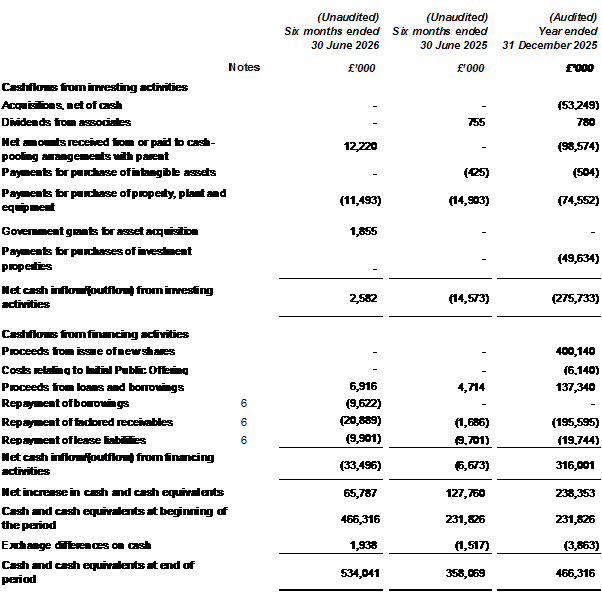
Condensed Consolidated Cash Flow Statement (continued)
Notes to the half-year condensed financial statements
1. Basis of preparation and accounting policies
Princes Group plc (the "Company") is a public company limited by shares, incorporated and domiciled in the United Kingdom and registered in England and Wales under the Companies Act 2006 as company number 02328824. The address of the registered office is Royal Liver Building, Pier Head, Liverpool, L3 1NX.
The condensed consolidated half year financial report for the six months ended 30 June 2026 have been prepared in accordance with UK-adopted International Accounting Standard 34 - Interim Financial reporting. They do not include all of the information required for full annual financial statements and should be read in conjunction with the Annual Report for the year ended 31 December 2025, which have been prepared in accordance with UK adopted international accounting standards. The Annual Report was approved by the Board of Directors on 24 April 2026 and has since been delivered to the Registrar of Companies. The audit report was unqualified, did not draw attention to any matters by way of emphasis and did not include a statement under Section 498(2) or 498(3) of the Companies Act 2006.
The condensed financial statements are unaudited and were approved by the Board of Directors on 14 September 2026. The condensed financial statements have been reviewed by the auditors and independent review report is set out above. There was no interim dividend declared for the six months ended 30 June 2026.
Going concern assumption
After making enquiries, the directors have a reasonable expectation that the Group has adequate resources to continue in operational existence to the end of the 2027 financial year. For this reason, they continue to adopt the going concern basis in preparing the consolidated half year financial statements.
The directors have reviewed the cash flow forecast, together with the availability of the committed borrowing facilities, to the end of the 2027 financial year. The Directors have also considered the headroom against covenants under the Group's borrowing facilities.
Accounting policies
The accounting policies applied by the Group in these condensed consolidated half year financial statements are the same as those applied by the Group in its Annual Report for the year ended 31 December 2025.
There have been no changes in economic conditions, since the signing of the financial statements in the most recent annual report, that the directors deem to have had a material impact on the fair value of financial assets or liabilities in the accounts.
Accounting estimates and judgements
The preparation of condensed half-year financial statements requires management to make judgments, estimates and assumptions that affect the application of accounting policies and the reported amounts of assets, liabilities, income and expenses. Actual results may differ from these estimates.
In preparing the condensed half-year financial statements, the significant judgements made by management in applying the Group's accounting policies and the key areas of estimation uncertainty are consistent with those applied in the Princes Group plc annual report for the year ended 31 December 2025 except for the basis of calculating pension costs on the defined benefits schemes owned by group.
The measurement of the defined benefit pension scheme requires the estimation of future changes in salaries, inflation, longevity of current and deferred members and the selection of a suitable discount rate. For the financial statements for the year ended 31 December 2025, management engaged Mercer Limited (a global professional services company whose specialisms include actuarial advice) to support in the process of establishing reasonable bases for all these estimates. Pension costs for the half-year period are calculated on a year‑to‑date basis by using the actuarially determined pension cost rate at the end of the prior financial year, in accordance with IAS 34 paragraph B9. Management deem this approach appropriate given the absence of any significant events that would materially impact relevant assumptions during the half-year period.
Seasonality of operations
Within the individual operating segments there is some seasonality within the trading results. However, seasonality within operating segments is largely offset, meaning for the Group as a whole there is no significant seasonality within the half year results presented.
2. Operating segments
The operating segment is a part of the group that undertakes business activities that generate revenue and costs, whose operating results are periodically reviewed by the Chairman, in his role as Chief Operating Decision Maker (CODM), for the purpose of taking decisions on the resources to be allocated to the segment and evaluating results, and for which financial information is available.
For the purposes of IFRS8, the Group's activity is identifiable in the following business segments: Foods, Fish, Italian, Oils, and Drinks.
Food: The Group supplies a large variety of foods such as baked beans, soups, ready meals, peas and pulses through the large food retailer and foodservice sales channels, which are predominantly manufactured in UK.
Fish: The Group supplies ambient tuna, mackerel, salmon and other fish in the UK and the EEA. The business unit is primarily served through the two production facilities in Mauritius.
Italian Products: The Group supplies canned and other tomato products, pasta, pulses,oil and other speciality products, through the large food retailer channel, which are primarily manufactured in Italy. Following the acquisition of Plasmon, baby food is also included in this segment.
Oil: The Group's oils business unit consists of a joint arrangement with Archer Daniels Midland (UK) Limited called Edible Oils Limited, established in 2005. The oils business unit predominantly operates out of the Group's production facilities located in UK, along with a facility in Poland. Products supplied are seed olive and speciality oils and compound fats.
Drinks: The Group's drinks business unit supplies a range of customer own brand juices, squash and carbonates, operating out of three production facilities in the UK.
The Chairman uses a measure of earnings before interest, tax, depreciation and amortisation to assess the performance of the operating segments.
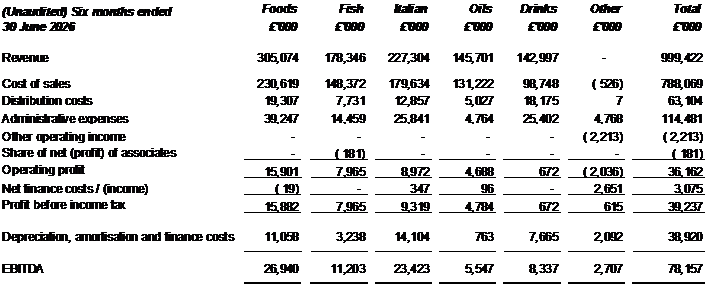
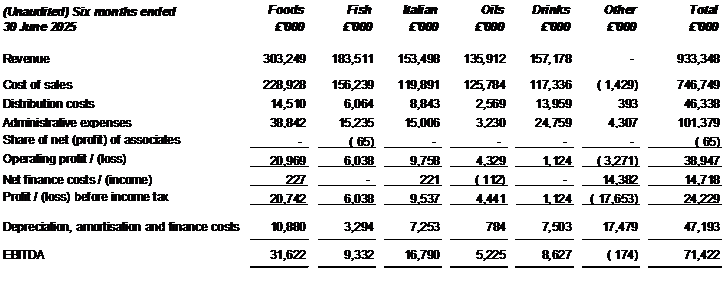
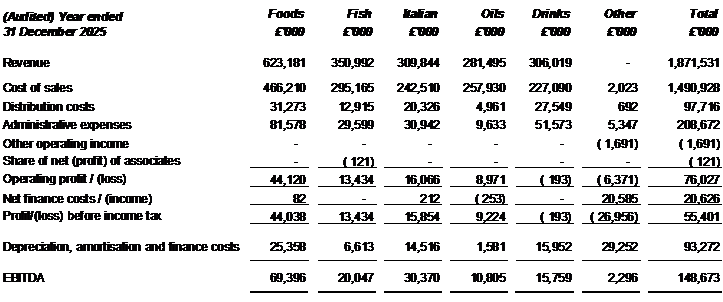
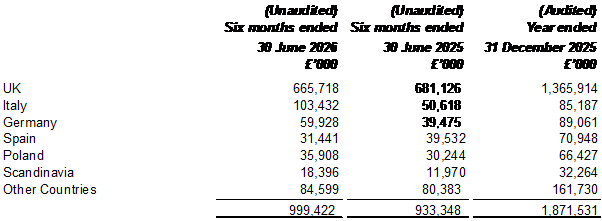
The following table provides a breakdown of revenue from continuing operations in the geographical area as monitored by management:
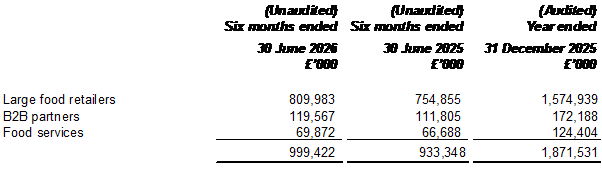
The following table provides a breakdown of revenue from continuing operations by distribution channel as monitored by management:
3. Income tax expense
Income tax expense within the half-year figures is recognised based on management's estimate of the weighted average effective annual income tax rate expected for the full financial year. Taxation for other jurisdictions is calculated at the rates prevailing in the respective jurisdiction. The estimated average annual tax rate used for the six months ended 30 June 2026 is 26.1% (30 June 2025: 25.5%). The Group's Annual report includes detail on the income tax calculation for 31 December 2025.
4. Earnings per share
The calculation of earnings per ordinary share is based on earnings after tax attributable to equity shareholders of the Company and the weighted average number of ordinary shares in issue during the year.
The calculation of the basic and diluted earnings per share is based on the following data:
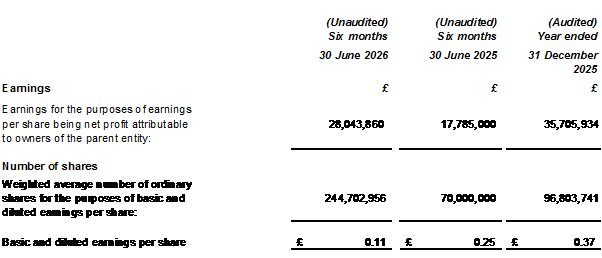
There are no potential ordinary shares that could be dilutive or anti-dilutive to the earnings per share measure. The weighted average number of shares used to calculate the earnings per share for the six-months ended 30 June 2025 has been adjusted retrospectively, in line with IAS 33, for the sub-division of shares that reduced the nominal value of share capital from £1 to £0.10 on 21 October 2025.
5. Cash and cash equivalents
Cash and cash equivalents presented in the statement of cashflows includes overdrafts of £11.7m (31 December 2025: £18.9m, 30 June 2025: £12.1m). These amounts are presented within borrowings in the statement of financial position.
6. Borrowings
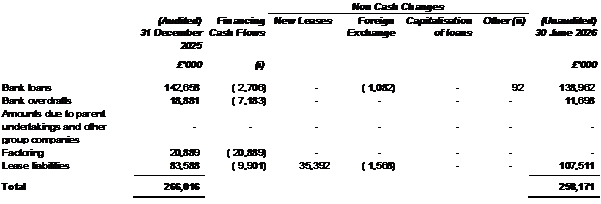
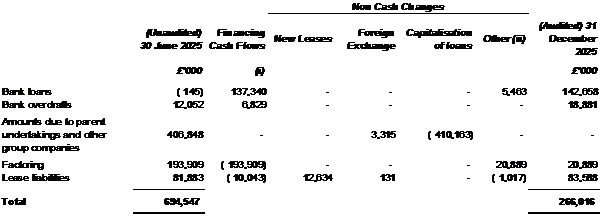
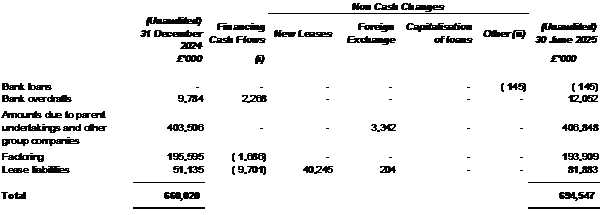
(i) The cashflows make up the net amount of proceeds from borrowings and repayments of borrowings in the statement of cashflows. Note, bank overdrafts are included within cash and cash equivalents in the cashflow statement.
(ii) Other changes include lease modifications and lease terminations and any cash movements due to investing/operating activities.
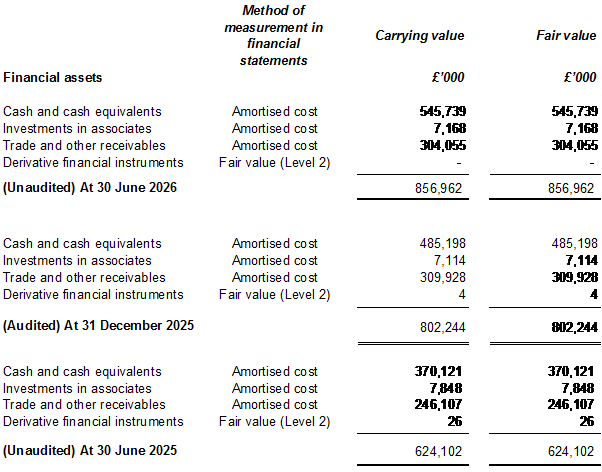
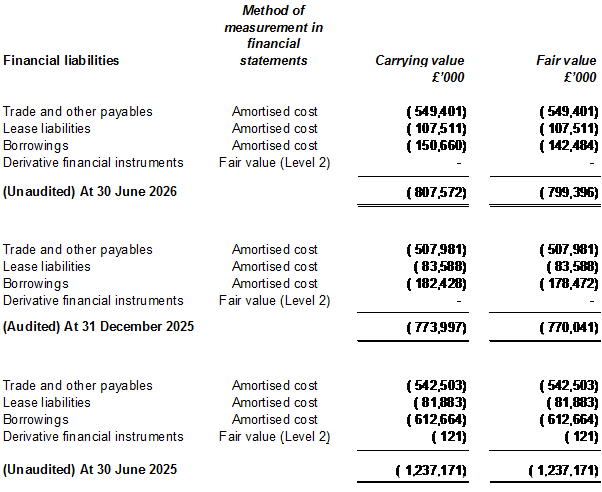
7. Financial instruments
The following table shows the carrying amounts of the Group's financial assets and financial liabilities. Fair value is the price that would be received to sell an asset or paid to transfer a liability through an arms-length transaction between average market participants.
8. Commitments
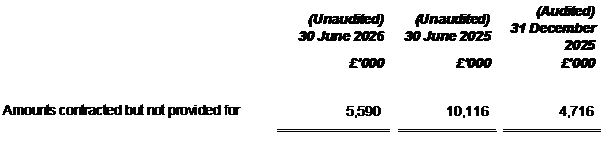
All capital commitments relate to the acquisition of property, plant and equipment.
9. Contingent liabilities
The Group may from time to time, and in the normal course of business, be subject to claims from customers and counterparties. The Group regularly reviews all these claims to determine any possible financial loss to the Group. No provision was considered necessary in the financial Information.
The Group have issued general indemnities in the normal course of business; however, none are considered material for disclosure in the financial statements.
10. Related party transactions
The Group's related party transactions and relationships for the year ended 31 December 2025 were disclosed in the Group's Annual Report. Other than as per the business combination as disclosed below, there have been no material changes in these relationships in the six months ended 30 June 2026 or up to the date of this report.
11. Business combinations
On 1 January 2026 the Group entered into an agreement with NewPrinces S.p.A subsidiary Plasmon Srl which gave the Group the right to conduct and operate the Plasmon business for a three-year term. Plasmon specialises in the production and sale of baby food, infant formula and speciality nutritional products. The agreement gives the Group the right to use Plasmon's contractual and employment relationships as well as the tangible and intangible assets which are required to carry out the business.
The accounting for the agreement is reflected in the group's accounts as a business combination under common control using predecessor accounting with assets and liabilities recognised at their existing carrying values from NewPrinces S.p.A accounts. This includes goodwill totalling £5.2m.
12. Subsequent events
On 29 May 2026 the Group approved a share buy-back programme to purchase up to 6,200,000 of its own ordinary shares. The purpose of the Share Buyback Programme is to fulfil several corporate purposes, including, but not limited to, the satisfaction of its Employee SAYE scheme which will be rolled out later this year.
On 22 July 2026 the Group entered into a loan agreement with Lloyds Bank plc for a principal amount of EUR 60m. The loan carries an interest rate of 4.39% and has a final maturity date of 22 July 2031.
13. Alternative performance measures
When reporting financial information, the board uses various Alternative Performance Measures (APM's) which it believes provide useful additional information for understanding the financial performance of the group.
The APMs should be considered in addition to IFRS measures and are not intended to be a substitute for them. Since IFRS does not define APMs, they may not be directly comparable to similar measures used by other companies.
The board uses selected Key Performance Indicators (KPIs), which are a mixture of IFRS measures and APMs, for performance analysis, planning and reporting. The table below defines any non-IFRS measures and reconciles them to their closest IFRS equivalent.
|
Performance measure |
Definition |
Reconciliation |
|
EBITDA |
IFRS earnings before interest, tax, depreciation and amortisation |
Table A |
|
EBITDA margin |
EBITDA (as defined above) divided by Total revenues calculated as a percentage. |
Table A |
|
Adjusted EBITDA |
EBITDA (as defined above) adjusted to exclude non-recurring items, i.e unusual, infrequent, one-off transactions (eg. asset disposal gains/losses, litigation settlements, restructuring costs, impairment charges) that distort underlying operational performance. |
Table A |
|
Adjusted EBITDA margin |
Adjusted EBITDA (as defined above) divided by Total Revenues calculated as a percentage. |
Table A |
|
Underlying free cash flow |
EBITDA adjusted for changes in working capital, capex, lease liabilities, tax and financing cashflows. |
Table B |
|
Free cash flow conversion rate |
This measure represents the efficiency of the business in translating earnings into actual cash. It is calculated as Underlying free cash flow (as defined above) divided by EBITDA (as defined above) shown as a percentage. |
Table B |
|
Net cash/debt position |
Cash & cash equivalents (including cash-pooling), less current and non-current borrowings. |
Table C |
|
Net cash/debt excluding IFRS 16 lease liabilities |
Cash & cash equivalents (including cash-pooling), less current and non-current borrowings. Excludes current and non-current lease liabilities (IFRS 16). |
Table C |
|
Equity ratio |
Total equity divided by total assets |
Table D |
|
Debt to assets |
Total liabilities divided by total assets |
Table D |
|
Current ratio |
Current assets divided by current liabilities |
Table D |
|
Quick ratio ROCE |
Cash & cash equivalents less inventories divided by current liabilities. Return on capital employed. It is calculated using 12 month rolling operating profit divided by total capital employed. Total capital employed is calculated as Total shareholder equity minus Net cash (excluding IFRS16 lease liabilities). |
Table D Table E |
Table A
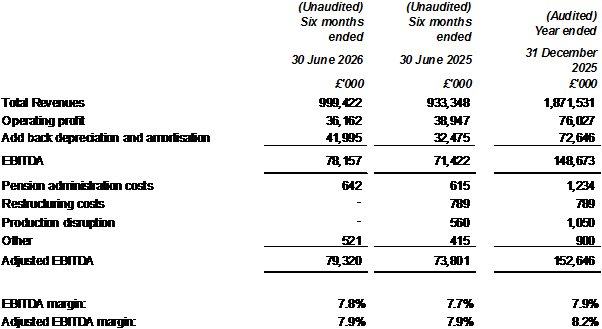
Table B
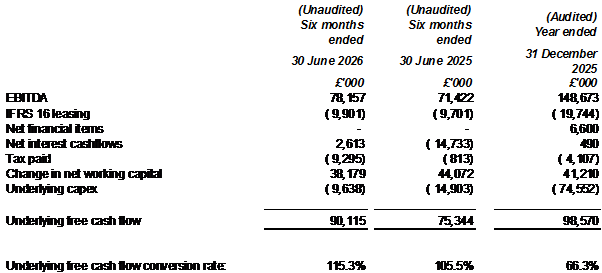
Table C
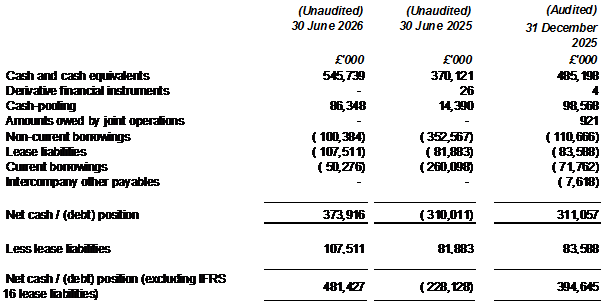
Table D
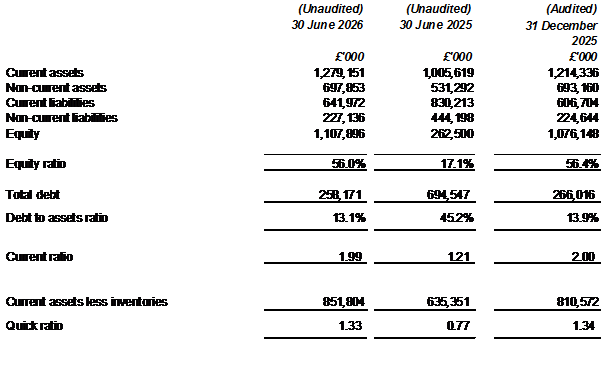
Table E
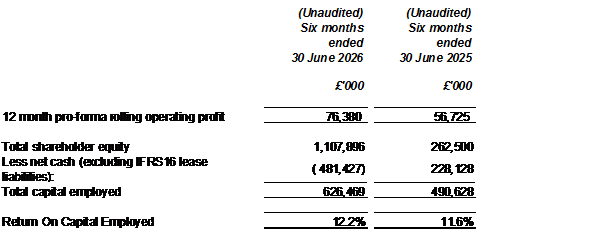
The 12-month pro-forma rolling operating profit is the latest 12 month consolidated operating profit adjusted for exceptional items (defined table A) and proforma adjustments consistent with those presented in the IPO prospectus dated 22 October 2025.
END
This information is provided by RNS, the news service of the London Stock Exchange. RNS is approved by the Financial Conduct Authority to act as a Primary Information Provider in the United Kingdom. Terms and conditions relating to the use and distribution of this information may apply. For further information, please contact rns@lseg.com or visit www.rns.com.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.
ENDRNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.