
Annual Results for the year ended 30 June 2026

Supermarket Income REIT PLC
16 September 2026
16 September 2026
SUPERMARKET INCOME REIT PLC
(the "Company", "SUPR" or together with its subsidiaries the "Group")
ANNUAL RESULTS FOR THE YEAR ENDED 30 JUNE 2026
ESTABLISHED A COMPELLING GROWTH PLATFORM UNDERPINNED BY STRONG GROCERY SECTOR DYNAMICS
Supermarket Income REIT plc (LSE: SUPR, JSE: SRI), the leading grocery real estate business that invests in high-quality, inflation-linked, grocery assets, reports its audited results for the year ended 30 June 2026 (the "Year").
• Continued growth in the resilient, non-discretionary grocery sector provides shareholders with a sustainable and attractive dividend yield
• Acquired £454 million of accretive properties in the year, diversifying the portfolio and scaling the JV with Blue Owl to £855 million
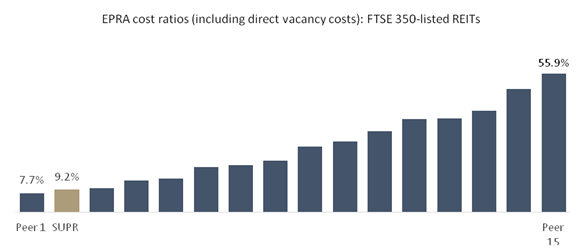
• Delivering value for shareholders with an EPRA cost ratio of 9.2% and targeting sustainable minimum dividend growth of 2% per annum from FY27
• Total shareholder return of 27.5% since internalisation
• Well-positioned for future growth, leveraging deep sector knowledge and relationships to execute on a pipeline of grocery property opportunities
FINANCIAL HIGHLIGHTS
|
Year ended 30-June-26 |
Year ended 30-June-25 |
Change in Year |
|
|
EPRA earnings per share[1] |
5.7 pence |
6.0 pence |
-4.1% |
|
IFRS earnings per share |
6.9 pence |
4.9 pence |
+39.4% |
|
Dividend per share declared |
6.2 pence |
6.1 pence |
+1.0% |
|
Dividend cover1,[2] |
93% |
98% |
-5.0ppts |
|
EPRA cost ratio1 |
9.2% |
13.0% |
-3.8ppts |
|
30-June-26 |
30-June-25 |
Change in Year |
|
|
Portfolio valuation1,[3] |
£2,010m |
£1,625m |
+23.7% |
|
Portfolio net initial yield1,3 |
6.0% |
5.9% |
+0.1ppts |
|
EPRA NTA per share1 |
87.5 pence |
87.1 pence |
+0.4% |
|
IFRS NAV per share (diluted) |
89.2 pence |
88.4 pence |
+0.9% |
|
Total accounting return |
7.5% |
7.2% |
+0.3ppts |
|
Loan to value1,3 |
43.9% |
31.1% |
+12.8ppts |
Rob Abraham, CEO of Supermarket Income REIT plc, commented:
"Over the past 18 months, we have transformed SUPR into a more efficient, scalable platform that is fully aligned with our shareholders and built to achieve long-term sustainable growth. In the year, we acquired £454 million of earnings enhancing assets, further diversified our portfolio, achieved one of the lowest EPRA cost ratios in the sector and introduced a minimum dividend growth target of 2% per annum from FY27."
"Since year-end, we have continued to execute our strategy at pace. Following our successful equity raise in July 2026; we have already made £222 million of accretive acquisitions and have ambitions to grow the portfolio to £4 billion and beyond. The fundamentals of the grocery market remain compelling and, as the leading landlord in the sector, we believe we are best placed to deliver on our clear strategy and the significant opportunities that exist."
Continued strategic progress to create an efficient and scalable growth platform to deliver shareholder returns
· Grew the Company's real estate portfolio from £1.6 billion as at 30 June 2025 to £2.0 billion as at 30 June 2026, including expanding the joint venture with funds managed by Blue Owl Capital (the "JV") to £855 million from £403 million at inception
· The reduction in earnings primarily reflects the timing of the redeployment of proceeds received following completion of the JV, together with the one-off increase in interest costs associated with our proactive decision to refinance and extend the term of our debt
· Acquired £454 million of assets during the period to support increases in future dividends, including:
o 10 high-performing Asda omnichannel supermarkets through the JV
o Further expansion into France with 20 additional Carrefour supermarkets
o Diversification into convenience with 10 Sainsbury's foodstores
o Nine high-quality foodstores through secondary market acquisitions
· Portfolio valuation increased by 2.5% on a like-for-like basis vs. MSCI All Property Capital Growth Index which was up 0.1%
· Post year-end renewed two large format store leases, resulting in improved terms and extended duration of income
· Continued to reduce the Company's operational costs achieving one of the lowest EPRA cost ratios in the sector of 9.2%, and on track to achieve below 9% in the near-term
· Targeting minimum dividend growth of 2% per annum from FY27
Delivering on ambitions to grow the portfolio
· Completed a £100 million equity raise in July 2026, which together with leverage, has funded £222 million of grocery acquisitions
· These funds have been fully deployed post year-end into nine grocery assets[4], at an average net initial yield of 6.6%[5]:
o Acquired five strong trading foodstores
o Further diversification with first acquisition of a grocery distribution centre, let to Sainsbury's
o Exchanged contracts to acquire an attractive portfolio of three supermarkets for £118 million
Proactively strengthening the balance sheet
· Fitch BBB+ investment grade rating reaffirmed providing access to attractively priced long-dated debt
· Debut £250 million unsecured bond issuance in July 2025 with a six-year duration and a fixed interest coupon of 5.125%
· £445 million debt refinancing in July 2026, delivering lower borrowing costs and increasing average debt maturity
· LTV of 43.9% and a Net Debt / EBITDA of 7.8x for the 12 months to 30 June 2026
Operating in a growing and resilient, non-discretionary sector
· Grocery spend reached £256 billion in 2025[6]
· Demonstrating volume growth, with grocery sales increasing by 3.2% in the 12 months to June 2026[7], ahead of food inflation at 1.7% for the same period[8]
· Mission critical omnichannel stores are capturing double digit growth in the online market, which now accounts for 12.6% of total grocery market[9]
Progress on ESG initiatives
· Became an accredited Living Wage Employer, certified by the Living Wage Foundation
· Joined the UN Global Compact, reflecting the Company's commitment to a principles-based approach to business
· Achieved a 'Prime' Corporate ESG performance rating by ISS STOXX and a second consecutive European Public Real Estate Association ("EPRA") Sustainability Best Practices Recommendations ("sBPR") Gold Award for sustainability reporting
Diverse pipeline of opportunities to assist in delivering future growth ambitions
· Actionable pipeline of over £500 million high-quality grocery assets
· Disciplined approach to capital allocation focused on attractive risk-adjusted returns and sustainable earnings growth for shareholders
· With its established position in UK grocery real estate, specialist market knowledge and unique sector relationships, SUPR is well-positioned to deliver its growth plans
FULL UNEDITED TEXT
The information contained in this announcement is an extract of information from SUPR's Annual Report for the year ended 30 June 2026 (the "Annual Report"). In accordance with DTR 6.3.5 (1A), the Annual Report will shortly be available to download from the National Storage Mechanism. In accordance with DTR 6.3.5 (3), a copy is also available on the Company's website: Results & Presentations - Supermarket Income REIT Plc.
PRESENTATION TO ANALYSTS
The Company will be holding an in-person presentation for analysts at 08.30am today at Peel Hunt LLP's offices at 100 Liverpool Street, London, EC2M 2AT. To register to attend in-person, please contact Headland Consultancy: SUPR@headlandconsultancy.com. There will also be a webcast available. To join the presentation via the webcast, please register using the following link: https://brrmedia.news/SUPR_FY26
The results presentation will also be available in the Investor Centre section of the Group's website.
|
Supermarket Income REIT plc |
|
|
Rob Abraham / Mike Perkins / Chris McMahon |
|
|
Headland Consultancy |
+44 (0)20 3805 4885 |
|
Susanna Voyle / Jack Gault / Dan Mahoney |
NOTES TO EDITORS:
Supermarket Income REIT plc (LSE: SUPR, JSE: SRI), a FTSE 250 company, is the only LSE listed company dedicated to investing in grocery properties which are an essential part of national food infrastructure. The Company focuses on grocery stores which are predominantly omnichannel, fulfilling online and in-person sales and are let to leading supermarket operators in the UK and Europe. The portfolio was valued at £2.0 billion as at 30 June 2026.
The Company's properties earn long-dated, secure, inflation-linked, growing rental income. SUPR targets a progressive dividend and the potential for long term capital growth.
The Company's shares are traded on the LSE's Main Market and on the Main Board of the JSE Limited in South Africa.
Further information is available on the Company's website www.supermarketincomereit.com
LEI: 2138007FOINJKAM7L537
CHAIR'S STATEMENT
Dear Shareholder,
I am pleased to present SUPR's results for the year ended 30 June 2026, its first full year with an internalised management structure that has transformed the Company into a highly efficient, scalable company to deliver growing returns for you, our shareholders. It was particularly encouraging to see shareholders' support for SUPR in July 2026, through a successful £100 million equity raise.
During the year, the team has made substantial strategic progress focused on driving long-term value for shareholders. The net proceeds realised from the transfer of assets to the Company's strategic joint venture with funds managed by Blue Owl Capital (the "JV") have been efficiently recycled into earnings-enhancing acquisitions, supporting our sustainable dividend, with a growth target of at least 2% per annum from FY27.
Alongside this, the Company enhanced its capital structure through its debut bond issuance in July 2025 and continues its disciplined approach to managing leverage prudently, completing a £445 million debt refinancing post-year end in July 2026.
The market has also increasingly recognised the progress made by the Company, with shares more recently trading broadly in line with NTA, up from a discount that peaked at 25%[10] a little over a year earlier. This positive share price response reflects our consistent delivery against the strategic initiatives first set out in November 2024, namely reducing the cost base, recycling capital and enhancing earnings for shareholders. Since internalisation, the Company has delivered a total shareholder return of 27.5%[11], reflecting the benefits of the enhanced alignment, efficiency and strategic flexibility of the internalised management platform.
A defining feature of the year has been the Company's ability to identify and execute attractive acquisition opportunities while maintaining investment discipline. During the year, SUPR completed £454 million of acquisitions, and a further £222 million4 post-year end having successfully deployed the proceeds of the July 2026 equity raise.
We continue to see supportive tailwinds for rental growth across the portfolio, with the major supermarket groups again benefiting from resilient consumer demand, rising sales and robust profitability, while their stores remain the backbone of their operating models.
The internalisation of the management function was a key milestone for the Company and has delivered meaningful benefits for shareholders. It has enabled significant cost reductions, with the EPRA cost ratio falling from 13.6% prior to internalisation to 9.2% today. The benefits of the new structure have continued to come through during FY26 with the Company on track to deliver an EPRA cost ratio below 9% in the near term.
Dividend
The Board remains focused on delivering sustainable and growing dividends for shareholders. The Company's investment activity, combined with operational efficiencies and the successful deployment of the new equity proceeds, has strengthened the earnings base. On behalf of the Board, I am pleased to recommend a target dividend of 6.30p for the year ending 30 June 2027, a 2% increase which is in line with our minimum annual growth target communicated at our interim results.
Governance and Board
During FY26, the Nomination Committee, led by Sapna Shah, has continued its succession planning. Vince Prior will step down following this year's AGM, having come to the end of his nine-year period on the Board. Vince has been with the Company from its inception and has played a significant role in the evolution, growth and success of the business and on behalf of the Board I would like to extend my sincere thanks to him.
Following a period of very positive but intensive change for the Company over the last 18 months, the Nomination Committee has, following consultation with key shareholders, asked me to extend my tenure as Chair for up to two years until the 2028 AGM, subject to annual shareholder approval.
During the year, the Remuneration Committee reviewed Executive Director salaries with a view to moving them towards market over time. Further details of the review, shareholder consultation exercise and conclusions are provided in the Directors' Remuneration Report in the Annual Report.
Outlook
The grocery sector remains an attractive and growing market, and we continue to see opportunities to deliver meaningful growth. The Company enters the new financial year with a more efficient cost structure, an enhanced operating platform and a compelling pipeline of opportunities. The recent equity raise, now successfully deployed, also demonstrates investor support for the Company's growth strategy and further broadens the shareholder base.
I would like to thank our shareholders for their continued support, and our team for their commitment and hard work during another active year. I look forward to updating the market on our progress as we continue to execute our strategy and deliver long-term value for shareholders.
Nick Hewson
Chair
15 September 2026
CHIEF EXECUTIVE'S REVIEW
FY26 has been a year of strong strategic delivery. Building on last year's transformation, we have used our established and scalable platform to grow our property portfolio, improve the quality of our earnings and cement our position as the leading specialist investor in grocery real estate.
Our ambition and strong alignment with shareholders is reflected in our focus on delivering a sustainable and growing dividend, underpinned by a minimum growth target of 2% per annum.
The strength of SUPR's proposition was further recognised by investors' support for a £100 million equity raise, completed shortly after the year end, and representing a real vote of confidence in our team and the successful execution of our strategy.
A growing, resilient sector
The success of our model is underpinned by the fact that grocery is a growth sector. Food is a non-discretionary, everyday essential, and demand has proven remarkably resilient through inflationary pressures and geopolitical uncertainty. With operators able to adjust pricing to help offset increased costs, the sector has continued to perform strongly. UK grocery sales grew by 3.2% in the 12 months to June 20267, ahead of the food inflation rate of 1.7% for the same period8. It is a market that is very difficult to disrupt, and our high-quality, mission-critical stores sit at the very heart of our tenants' business models.
Large format stores continue to be the dominant sales channel, offering consumers both a much wider product range but also much better value. Our focus on omnichannel stores ensures our portfolio continues to capture the growth in online sales, which now accounts for 12.6%9 of the total grocery market. The majority of online sales growth continues to be delivered from retailers' existing store estates, rather than from dedicated fulfilment centres. For example, Tesco grew online sales by 11% in FY25/26, including growth of 51% for its quick commerce offering, Tesco Whoosh[12].
These mission-critical stores deliver highly secure income. Our long-dated, predominantly triple-net, inflation-linked leases place responsibility for property costs and maintenance with tenants, giving us reliable and growing cashflows.
A low-cost, efficient platform
Our efficient platform continues to deliver one of the lowest cost ratios in the sector. Internalisation has allowed us to bring our EPRA cost ratio down to 9.2% from 13.6% in December 2024, and we remain on track to achieve our goal of a ratio below 9%. As a highly efficient, low-cost model, we expect this ratio to fall further as the business grows, benefiting from operational leverage and directly enhancing shareholder returns.
An established platform for growth
Our sector specialism and robust balance sheet give us the capacity and flexibility to grow. We scaled our JV with Blue Owl to £855 million and completed £454 million of earnings-enhancing acquisitions at a blended net initial yield of 6.5%. The team's deep grocery expertise allows us to identify attractive opportunities where the quality of the underlying real estate, store performance and lease structure support long-term value. Our investment in 10 Asda stores is indicative of this disciplined approach, adding high-quality grocery assets let to an operator with significant scale.
We have also continued to diversify the portfolio, both by format with the acquisition of 10 Sainsbury's convenience stores, and by geography as we further expanded into France with 20 additional Carrefour supermarkets.
Shortly after the year end, we successfully completed a £100 million equity raise, which is a clear endorsement of shareholder trust in our team and the continued attraction of the grocery real estate sector. The proceeds facilitated the acquisition of a highly attractive pipeline of £222 million across nine assets in the UK, including our first grocery distribution facility, strengthening our position as we deliver enhanced earnings growth.
Looking forward, while UK omnichannel supermarkets remain the core driver of the business, we continue to explore further geographies and grocery distribution warehousing, using our specialism and tenant relationships to access the wider grocery real estate universe.
Active asset management
Beyond acquisitions, our team creates further value through active asset management. Post year-end, we renewed the leases on two stores, extending terms to 15 years from an average of seven, with a modest 7% average rent reduction putting them broadly in-line with ERV, and the introduction of inflation-linked reviews on one of the sites. These renewals helped to maintain our portfolio WAULT and yet again prove the importance of large format stores to the operators.
Our grocery-anchored sites are increasingly sought after by a broad range of retailers wanting to locate alongside our strong-trading supermarkets, drawn to the footfall our stores generate. The Company is working in partnership with Lidl, delivering a 12,000 sq ft extension to create a new 22,000 sq ft store. Construction commenced in March 2026 and is expected to complete in December 2026. This reflects the quality of our locations and illustrates the embedded value we can unlock across the portfolio estate.
Delivering on our sustainability priorities
The Company remains committed to responsible investment and long-term value creation. During the year, the Company continued to enhance its sustainability strategy and related disclosures. This included the publication of its annual Sustainability Report, outlining performance over the period and achieving an EPRA Sustainability Best Practices Recommendations ("sBPR") Gold Award for the second consecutive year.
Progress included strengthening our engagement with tenants on energy performance and enhancing ESG data collection processes to improve the completeness and accuracy of the Company's GHG inventory and support the continued implementation of its Climate Transition Plan.
The Company's approach continues to be underpinned by transparency and external validation, including the third year of external assurance over its reported location-based Scope 1, 2 and 3 GHG emissions. The Assurance Report is available on the Sustainability section of the Company's website.
Further details are provided in the Company's standalone Sustainability Report.
Outlook
SUPR is now in a stronger position than ever to deliver long-term sustainable growth in a way that is fully aligned with shareholders.
Our scalable and efficient operating platform leverages the deep grocery sector expertise and industry relationships within our team to unlock attractive, earnings-enhancing investment opportunities in a growing and highly resilient sector.
We have a pipeline in excess of £500 million, access to capital and the right team to deliver it, supporting a sustainable targeted minimum dividend growth of 2% per annum from FY27. With the joint venture scaled to £855 million and the size of opportunity ahead, we remain focused on growing at pace. I am confident that we will achieve on our ambition of doubling the portfolio to at least £4 billion, and continue to deliver sustainable, long-term returns to shareholders.
Rob Abraham
Chief Executive Officer
15 September 2026
RESPONSIBILITY STATEMENT OF THE DIRECTORS IN RESPECT OF THE ANNUAL REPORT
The Directors confirm to the best of their knowledge:
· The Group financial statements prepared in accordance with UK adopted international accounting standards and the Company financial statements prepared in accordance with applicable law and United Kingdom Accounting Standards (United Kingdom Generally Accepted Accounting Practice), including Financial Reporting Standard 102 "The Financial Reporting Standard applicable in the UK and Republic of Ireland", give a true and fair view of the assets, liabilities, financial position and profit or loss of the Group
· The Annual Report and Accounts include a fair review of the development and performance of the business and the position of the Group and Company, together with a description of the principal risks and uncertainties that they face
· The Annual Report and Accounts taken as whole, is fair, balanced and understandable and the information provided to shareholders is sufficient to allow them to assess the Group's performance, business model and strategy
On behalf of the Board of Directors of SUPR
Nick Hewson
15 September 2026
AUDIT OPINION
The financial information set out in this announcement is derived from the audited consolidated financial statements of the Group for the year ended 30 June 2026 which have been prepared in accordance with UK-adopted international accounting standards, and the audited financial statements of the Company for the year ended 30 June 2026 which have been prepared in accordance with the United Kingdom Generally Accepted Accounting Practice. The independent auditors have issued an unqualified audit opinion on the consolidated financial statements for the year ended 30 June 2026 and their report contained no statement under section 498(2) or (3) of the Companies Act 2006. The financial information contained in this announcement does not constitute statutory accounts within the meaning of section 434 of the Companies Act 2006. The statutory accounts for the year ended 30 June 2026 will be delivered to the Registrar of Companies in due course.
Forward-Looking Statements
This announcement contains forward-looking statements which are made in good faith based on information available to the Directors at the date of this announcement. Such forward-looking statements include, without limitation, statements regarding the Company's plans, objectives, expectations, intentions, targets, estimates, projections and anticipated financial and operational performance. These forward-looking statements can be identified by the use of words such as "expects", "anticipates", "intends", "plans", "believes", "targets", "estimates", "projects", "aims", "may", "will", "should", "could" or similar expressions. By their nature, forward-looking statements involve risks and uncertainties because they relate to events and depend on circumstances that may or may not occur in the future. Forward-looking statements are not guarantees of future performance and actual results may differ materially from those expressed or implied by such statements. Factors that could cause actual results to differ materially from those expressed or implied by forward-looking statements include, but are not limited to: changes in general economic, business or market conditions in the UK and internationally; changes in property valuations, rental income and tenant covenant strength; changes in interest rates and the availability of financing; regulatory changes affecting the UK real estate investment trust regime; and other factors outside the Company's control. Except as required by the UK Listing Rules, the Disclosure Guidance and Transparency Rules, the Market Abuse Regulation (UK MAR) or applicable law, the Company expressly disclaims any obligation or undertaking to update, review or revise any forward-looking statement contained in this announcement, whether as a result of new information, future developments or otherwise.
[1] The alternative performance measures used by the Group have been defined and reconciled to the IFRS financial statements within the Annual Report
[2] Calculated as EPRA earnings divided by dividend paid in the year
[3] Including share of joint venture portfolio and the fair value of financial assets held at amortised cost
[4] Including five assets for which the Company has exchanged contracts to acquire
[5] Based on respective transaction costs
[6] IGD: UK grocery market value
[7] Kantar: UK grocery market sales growth for the 52 weeks to 14 June 2026
[8] CPIH food and non-alcoholic beverages inflation rate for the 12 months to June 2026
[9] Kantar: UK grocery market online share for the 12 weeks to 14 June 2026
[10] Based on a share price of 65.5p as at 24 January 2025
[11] Total shareholder return from 26 March 2025 to 30 June 2026
[12] Tesco Preliminary Results 2025/26 published 16 April 2026.
This information is provided by RNS, the news service of the London Stock Exchange. RNS is approved by the Financial Conduct Authority to act as a Primary Information Provider in the United Kingdom. Terms and conditions relating to the use and distribution of this information may apply. For further information, please contact rns@lseg.com or visit www.rns.com.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.
ENDRNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.