

Sovereign Metals Limited
25 September 2026
NEWS RELEASE I 25 SEPTEMBER 2026
2026 annual report
Sovereign Metals Limited (ASX:SVM; AIM:SVML; OTCQX:SVMLF) (Sovereign or the Company) advises its 2026 Annual Report has been published today at https://api.investi.com.au/api/announcements/svm/4ff1a2bb-c5f.pdf with the results provided below.
The Company has also published an Appendix 4G (Key to Disclosures: Corporate Governance Council Principles and Recommendations) and its 2026 Corporate Governance Statement today which are available at https://api.investi.com.au/api/announcements/svm/b73d2b86-882.pdf.
|
Enquiries |
|
Frank Eagar, Managing Director & CEO South Africa / Malawi +27 21 140 3190 Sapan Ghai, CCO London +44 207 478 3900 |
|
Nominated Adviser on AIM and Joint Broker |
|
|
SP Angel Corporate Finance LLP |
+44 20 3470 0470 |
|
Ewan Leggat Charlie Bouverat |
|
|
|
|
|
Joint Broker |
|
|
Stifel |
+44 20 7710 7600 |
|
Varun Talwar |
|
|
Ashton Clanfield |
|
DIRECTORS' REPORT
The Directors of Sovereign Metals Limited present their report on the Group consisting of Sovereign Metals Limited (the Company or Sovereign or Parent) and the entities it controlled at the end of, or during, the year ended 30 June 2026 (Group).
OPERATING AND FINANCIAL REVIEW
KASIYA CRITICAL MINERALS PROJECT
Sovereign is focused on the development of its Kasiya critical minerals project (Kasiya or the Project). Kasiya is the world's largest known natural rutile deposit and one of the largest flake graphite deposits in the world, with the potential to produce a heavy rare earth concentrate (REC) as a by-product.
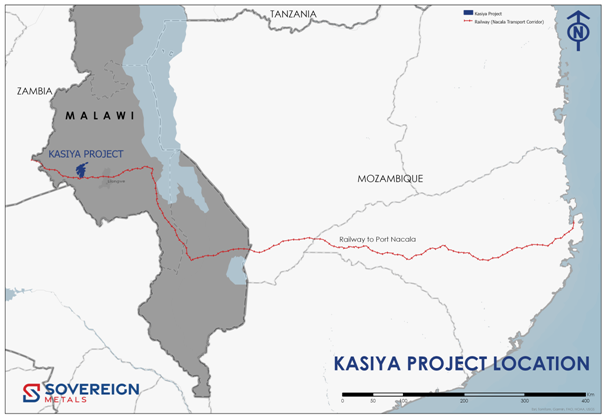
Figure 1: Kasiya Regional Project Location
The Definitive Feasibility Study (DFS), completed during the year with oversight from the Sovereign-Rio Tinto Technical Committee, reaffirmed Kasiya's potential to become a large, low-cost producer of strategic minerals. Following the completion of the DFS, an evaluation of a REC by-product from rutile tailings stream was completed with the announcement of scoping study (Scoping Study) which confirmed Kasiya's potential as globally significant and strategic source of critical rare earths.
HIGHLIGHTS DURING AND SUBSEQUENT TO YEAR END
Kasiya Definitive Feasibility Study Delivers Outstanding Results
· Pre-tax NPV8 of US$2.2 billion on capital expenditure to first production of US$727 million - an NPV to capex ratio of 3.0x
· Steady state annual EBITDA of US$476 million and pre-tax, unlevered free cash flow of US$452 million; total revenue of US$16.2 billion initial 25-year mine life with potential for multi-generational mine life extensions
· Operating cost of just US$450/t product (FOB Nacala) - underpinning strong margin resilience across commodity cycles
· Positioned to become the world's largest producer of both natural rutile (222ktpa) and natural flake graphite (275ktpa) - two commodities designated as Critical Minerals by the United States and the European Union
· DFS completed under the oversight of the Sovereign-Rio Tinto Technical Committee, with workstreams aligned with IFC Performance Standards; World Bank/IFC Collaboration Agreement in place as potential co-lead mandated lead arranger for project financing
· Data obtained from Pilot Mining Program, completed with technical input from Rio Tinto, provided real-world inputs and validation across key DFS workstreams
· Heavy rare earth evaluation not included in DFS
Kasiya - A Rare Earths Project With No Mine Of Its Own To Build
· Since the completion of the DFS, Sovereign has had deepening engagement with the U.S. Government, major U.S. companies, and industry stakeholders
· Scarce dysprosium (Dy), terbium (Tb), yttrium (Y), samarium (Sm) and gadolinium (Gd) oxides in elevated levels - all under Chinese export controls since April 2025
· Neodymium-praseodymium (NdPr), the primary input to Neodymium-Iron-Boron (NdFeB) permanent magnets, also present in levels similar to other Western rare earths mines
· 310tpa of NdPr and 36tpa DyTb - sufficient for the magnets in ~7 million humanoid robots over LOM; DyTb alone equivalent to ~18% of nameplate feed of America's first DyTb separation plant
· 193tpa Y - military radar and jet-engine thermal-barrier coatings; equivalent to ~35% of average annual U.S. consumption, which is 100% import-reliant
· 82tpa Sm + Gd - samarium used to steer Patriot, Tomahawk and AMRAAM missiles depleted to 2-3-year supply; gadolinium equivalent to 70% of the world's annual MRI supply. U.S. defence demand for both: classified
· Base Case ~US$722M Pre-Tax NPV8 uplift to Kasiya from incremental capital to first production of ~US$29M with potential upside NPV8 of US$883M
· Incremental Base Case Pre-Tax IRR of ~151% and payback of approximately 1.5 years
· ~90% operating margin with incremental site operating costs of ~US$0.90/kg REC
· ~US$84M incremental steady state annual EBITDA lifts Kasiya profitability and cash flow generation
· Pre-tax, unlevered free cash flow of ~US$1.8B over potential 23-year initial life of mine (LOM)
· Total Integrated Kasiya Pre-Tax NPV of US$2.9Bn
Sovereign to Advance Kasiya with US-Focused Critical Minerals Strategy
· During the year, Sovereign has had deepening engagement with the U.S. Government, major U.S. companies, and industry stakeholders
· Sovereign will now prioritise a U.S.-focused critical-minerals strategy, positioning Kasiya as a secure, non-Chinese source of titanium feedstock and natural graphite for the U.S. and allied supply chains
· Commercial workstreams will include:
o advancing rutile and graphite offtake discussions toward binding agreements with Mitsui, Traxys and other strategic U.S. and U.S.-allied counterparties
o continued engagement with potential offtake partners and U.S. government stakeholders in relation to the REC by-product opportunity
· Kasiya potentially provides exposure to three minerals designated critical by the U.S. - titanium (via natural rutile), graphite and heavy rare earths (via a REC by-product) - each feeding U.S. and allied supply chains, including Japan, being the dominant supplier of titanium metal to the U.S.
Successful Rehabilitation Trials and Community Partnerships
· Second year of rehabilitation trials at the Pilot Mining site neared completion ahead of the mid-2026 harvest, with crop yields expected to reach the first-year benchmark of 5.2 tonnes of maize per hectare - around five times the regional average
· Diversified multi-cropping system expanded, combining maize with bamboo, winter beans, grass fodder and groundnuts on rehabilitated post-mining land
· The 28 local farmers involved in the trials formally requested that Sovereign remain at the trial site and support the establishment of a farming co-operative - a strong community endorsement and a central pillar of Kasiya's post-closure social transition strategy
· Empirical trial data integrated into the Mine Closure and Mine Rehabilitation Plans - critical components for project bankability and alignment with the standards required by development finance institutions
Next Steps
· Advance offtake discussions and progress towards binding definitive agreements
· Variability testwork on Total Rare Earth Oxide (TREO) distribution within REC product with REC marketing and offtake discussions commencing immediately
· Pre-Feasibility Study: rare earths integrated into Kasiya's definitive development case; completion targeted 2027
· Commence offtake discussions for the rare earth by-product
OPERATIONS
KASIYA DEFINITIVE FEASIBILITY STUDY RESULTS
During the year, the Company announced the results of the DFS for Kasiya. The DFS built on the outcomes of the Optimised Pre-feasibility Study announced in January 2025 and on empirical data from the Pilot Mining and Rehabilitation Program (Pilot Mining) completed in 2024. The DFS was undertaken in accordance with a scope of work approved by, and with technical input and oversight from, the Sovereign-Rio Tinto Technical Committee and, where applicable, conforms to the World Bank Group's International Finance Corporation (IFC) Performance Standards to enhance bankability of the Project.
Following input from world-class consultancies, Sovereign's highly experienced owners' team, and subject matter experts from Rio Tinto, the DFS has reconfirmed that Kasiya will be a leading future supplier to two distinct strategic critical minerals supply chains and outside of Chinese control - natural rutile for the titanium industry and natural flake graphite.
Outstanding Financial Returns
The key financial metrics from the DFS (steady state, all on a 100% project basis) are set out below:
TABLE 1: Key DFS Metrics (Steady State)
|
OPERATING METRICS |
Units |
Results |
|
Initial Life of Mine (LOM) |
Yrs |
25 |
|
Total Ore Mined |
Mt |
536 |
|
Phase 1 Plant Throughput (Yrs 1-4) |
Mtpa |
12 |
|
Phase 2 Plant Throughput (Yrs 5-25) |
Mtpa |
24 |
|
Annual Rutile Production (95%+ TiO2) |
ktpa |
222 |
|
Annual Graphite Production (96% TGC) |
ktpa |
275 |
|
FINANCIAL PERFORMANCE |
||
|
Total Revenue |
US$M |
16,210 |
|
Annual Revenue |
US$M |
728 |
|
Annual EBITDA |
US$M |
476 |
|
Annual Free Cash Flow (pre-tax, unlevered) |
US$M |
452 |
|
NPV8 (real, pre-tax) |
US$M |
2,204 |
|
IRR (pre-tax) |
% |
23% |
|
OPERATING AND CAPITAL EXPENDITURE |
||
|
Capex to First Production |
US$M |
727 |
|
Total LOM Development Capex |
US$M |
1,239 |
|
Total LOM Sustaining Capex |
US$M |
431 |
|
Operating Costs (FOB Nacala) |
US$/t product |
450 |
Note: Steady State is defined as years of operation during which total run-of-mine is at full capacity of 24 Mtpa (i.e., years 5 to 23). All results are presented on a 100% project basis.
Summary of Key DFS Workstreams
Dry Mining Method Confirmed
Using real-world data collected from the Pilot Mining, the DFS confirms a dry mechanical mining method using draglines and 100t rigid dump trucks. The soft, free-dig saprolite orebody requires no drilling, blasting, crushing or milling. A two-bench approach (5m top cut, up to 15m bottom cut) keeps the draglines above the water table, eliminating the need for production equipment below groundwater level. This represents a significant de-risking step from the hydro-mining method originally considered in the original Pre-feasibility Study.
No Conventional Tailings Storage Facility
A major advancement in the DFS is the elimination of the conventional Tailings Storage Facility, leading to a significant reduction in the mining footprint and providing a flexible, lower-risk tailings management solution. All tailings will be stored via hydraulic co-disposal backfilling of mined-out pits, designed in compliance with the Global Industry Standard on Tailings Management. The 50:50 fines-to-sand backfill ratio closely matches the existing soil profile, supporting progressive rehabilitation.
Hydropower-Sourced Grid Electricity
The DFS is based on connection to Malawi's national hydropower grid via a 132kV overhead line to the Nkhoma substation. Electricity Supply Corporation of Malawi Limited has confirmed significant grid expansion is underway, including a 400kV Mozambique interconnector and the 375MW IFC/World Bank-funded Mpatamanga hydropower station. Grid connection delivers substantially lower power costs and a favourable emissions profile.
Dual Plant Configuration and Processing Flowsheet
The DFS confirms a staged development with two 12Mtpa processing plants - South Plant from Year 1 and North Plant from Year 5 - positioned at the respective resource centres of gravity to minimise haulage distances and costs. The Wet Concentration Plant employs a low-energy gravity separation process to produce a Heavy Mineral Concentrate, which is then fed to the Mineral Separation Plant for electrostatic and magnetic separation to yield premium-quality rutile (+95% TiO₂). Graphite-rich concentrate recovered from the spirals is processed in a dedicated flotation plant, producing a high-purity, high-crystallinity, coarse-flake graphite product.
Logistics and Export Infrastructure
Kasiya's products will be railed directly from a purpose-built dry port at the mine site eastward along the Nacala Logistics Corridor to the container terminal at the Port of Nacala on the Indian Ocean. The existing heavy-haul rail line and deep-water port provide a proven, operational export route - a significant infrastructure advantage over comparable undeveloped projects. Product transport cost is estimated at US$117/t product (FOB Nacala).
IFC Performance Standards Integrated into Design
The DFS has been prepared in alignment with IFC Performance Standards, with a comprehensive Environmental and Social Impact Assessment nearing completion and the full suite of environmental and social specialist studies completed. Sovereign's established on-the-ground social team of 22 core staff and 90-member Community Liaison Team represent a level of social preparedness rarely achieved at DFS stage.
SOVEREIGN ADDS RARE EARTHS TO RUTILE (TITANIUM) AND GRAPHITE PRODUCT SUITE
Subsequent to the end of the period, Sovereign completed a Scoping Study to assess the operational, commercial and economic viability of adding a third product stream to the Kasiya Project. The Scoping Study shows that ~2,626tpa of monazite REC can be recovered from the rutile tailings stream. Together with the results of the Kasiya DFS, Sovereign is potentially positioned to be a multi-decade supplier of a critical minerals products suite essential to the U.S. and U.S.-allied defence and aerospace, AI infrastructure, robotics, energy and other vital industries.
Kasiya - One Project to Feed the West's Critical Supply Complex
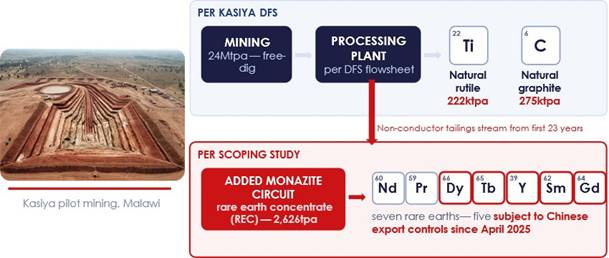
Figure 2: Kasiya Circuit Schematic and Product Suite
TABLE 2: SIDE-BY-SIDE KASIYA STUDY RESULTS
|
Metric |
Unit |
Kasiya DFS (Rutile & Graphite) |
Scoping Study Base Case ±30% (Rare Earths) |
|
Total Revenue |
US$M |
16,210 |
~2,134 |
|
EBITDA |
US$M pa |
476 |
~84 |
|
Free Cash Flow (pre-tax) |
US$M pa |
452 |
~82 |
|
NPV8 (pre-tax) |
US$M |
2,204 |
~722 |
|
Capex to 1st production |
US$M |
727 |
~29 |
MONAZITE BY-PRODUCT CONFIRMED WITH MAIDEN MINERAL RESOURCE ESTIMATE
A maiden by-product Mineral Resource Estimate (MRE), estimated for the REC Scoping Study, constrained to the DFS open pits, was estimated at 69kt monazite contained in 524.4Mt at 0.0132% monazite and classified 74% Indicated and 26% Inferred. The grade reflects monazite's status as a by-product. Since the monazite MRE sits within pits the DFS has already designed, no additional mining is required to access it.
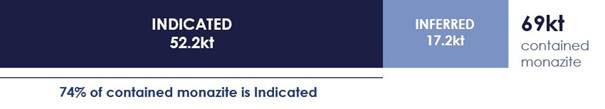
Figure 3: Monazite contained within the Kasiya 2026 MRE
In January 2026, Sovereign announced that it had successfully recovered a monazite product containing high-value heavy rare earth elements (REE) alongside common light REEs from the tailings stream generated during rutile processing at its Lilongwe laboratory facilities in Malawi. The concentrate was recovered from material that would otherwise be discarded, i.e. the non-conductor tailings stream from electrostatic separation of a heavy mineral gravity concentrate of Kasiya ore. Independent preliminary chemical analysis of magnetic concentrates from processed resource drilling samples confirmed the favourable rare earth oxide distributions within the monazite concentrate
NEAR-ZERO INCREMENTAL OPERATING COSTS
Kasiya's REC will be recovered from mineral streams the DFS flowsheet already produces. Upstream steps including free-dig mining, ore transport to the plant, the scrubber, wet concentration and electrostatic separation have been defined and costed in the DFS and accordingly attributed to rutile and graphite production. The only incremental processing is the added monazite concentrate circuit which involves spiral gravity separation and flotation treating the non-conductor stream from the Mineral Separation Plant, together with product packaging and storage. There is no additional mining, no early-stage processing and no change to the DFS mining method, wet concentration or graphite recovery strategy.
Incremental operating costs are accordingly low. The incremental site operating cost is ~US$0.90/kg REC at the mine gate. Including transport and port charges, the cost is ~US$1.39/kg REC free-on-board FOB Dar es Salaam. Including ocean freight and insurance, the total cost is ~US$3.68/kg REC delivered CIF Houston, Texas. The Study deliberately costs Kasiya's REC delivered into the United States. On that basis, the operating margin is approximately 90%. Due to its by-product nature, this cost structure holds across rare earth price cycles. Including all other regulatory fees, Sovereign can land REC in America for US$3.85/kg in any market.
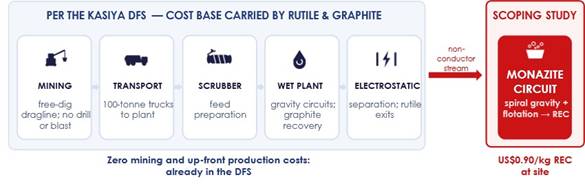
Figure 4: Kasiya's circuit to produce REC is added onto the DFS operation
PROFITABLE EVEN AT U.S. GOVERNMENT FLOOR PRICES
Since Sovereign's REC may be a by-product of the titanium and graphite operation defined in the DFS, Kasiya REC supply does not depend on rare earth prices to remain in production. This is reflected in the Study's two main price cases: the Base Case (using Argus Media price forecasts) delivers the potential for an incremental pre-tax NPV₈ of US$722 million at a 151% IRR, and the Western Supply Case (reflecting higher demand for ex-China supply of monazite concentrate) US$883 million at 172%.
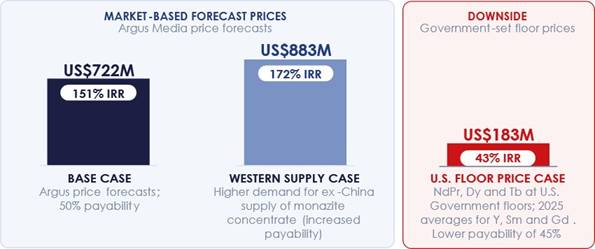
Figure 6: Kasiya pre-tax NPV and IRR in various market and geopolitical scenarios
A third case tests the bottom of the market as the U.S. Government itself has defined it. Since July 2025, guaranteed minimum prices have become a standard feature of U.S. rare earth supply arrangements:
· a US$110/kg floor for NdPr established with MP Materials and repeated with Lynas; and
· the first Western floor prices for heavy rare earths, at US$575/kg for Dy and US$2,050/kg for Tb
The U.S. Floor Price Case applies these floors, with 2025 average prices for yttrium, samarium and gadolinium which do not currently have floor prices but are deemed critical. Even in this scenario, the circuit generates US$183 million of incremental pre-tax NPV₈ and a 43% IRR. These floor prices arise under U.S. Government arrangements with third parties and are applied as a downside assumption only; Kasiya is not party to any such arrangement.
SOVEREIGN TO ADVANCE KASIYA WITH US-FOCUSED CRITICAL MINERALS STRATEGY
With full responsibility for commercial, offtake and financing workstreams now with Sovereign, the Company is prioritising a US-focused critical minerals strategy. Kasiya is well placed to supply natural rutile and natural graphite to supply chains serving the US and allied economies, addressing acute gaps in secure, non-Chinese sources of critical minerals feedstock, alongside the potential heavy rare earth by-product opportunity.
Sovereign intends to progress existing rutile and graphite offtake arrangements, including those with Mitsui & Co., Ltd and Traxys North America LLC, from non-binding arrangements toward binding agreements, subject to negotiation. The Company will deepen engagement with the US Government, major US companies, industry stakeholders and development-finance institutions, and intends to pursue partnerships and financing arrangements with institutions across the US-allied economies, consistent with Kasiya's role in securing critical minerals supply. The Company's Collaboration Agreement with the IFC remains central to the Project's financing strategy.
SUCCESSFUL REHABILITATION TRIALS AND COMMUNITY PARTNERSHIPS
In April 2026, the Company announced that its second year of rehabilitation trials, as part of the Pilot Mining at Kasiya, was nearing completion for the upcoming harvest season in Malawi. The rehabilitation trials provide practical, multi-year evidence demonstrating Sovereign's alignment with international rehabilitation, environmental, and community good-practice standards. Empirical data from the trials were used to prepare the Mine Closure and Mine Rehabilitation Plans, which are now integrated into the mining, backfilling and post-mining closure planning - critical components for project bankability and alignment with the standards required by development finance institutions.
The second year of trials builds on the success of the first year, which delivered maize yields of 5.2 tonnes per hectare versus the regional average of 1 tonne per hectare - a fivefold increase that confirmed post-mining land can achieve superior agricultural productivity compared to pre-mining land. Second-year crop yields are expected to reach the first-year benchmark when harvested in mid-2026. The second year expanded the rehabilitation approach into a diversified multi-cropping system, combining maize with Giant Bamboo, winter beans, grass fodder and groundnuts, providing participating communities with a wider range of food, cash and fodder crops.
After two years of close collaboration, the 28 local farmers involved in the trials formally requested that Sovereign remain at the trial site and support them in establishing a farming co-operative. This represents a strong community endorsement of the program's value and is a central pillar of Kasiya's post-closure social transition strategy, demonstrating that the Project can deliver lasting economic benefits to local communities well beyond the mine life. The outcomes directly complement the collaboration with the IFC, which is supporting integration of IFC Performance Standards into the Project's Environmental and Social Impact Assessment, and strengthening Kasiya's pathway to bankable development and international project financing.
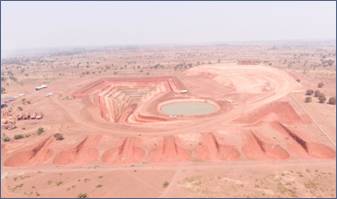
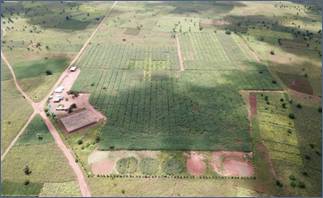
Figures 7 & 8: Pilot mining site post-mining and following rehabilitation.
RESULTS OF OPERATIONS
The net loss of the Group for the year ended 30 June 2026 was $25,632,938 (2025: $40,440,339). Significant items included in the year end loss are the following:
(i) Interest income of $1,524,771 (2025: $2,043,809) earned on term deposits held by the Group;
(ii) Exploration and evaluation expenses of $23,379,720 (2025: $33,897,375) in relation to the Kasiya project. This is attributable to the Group's accounting policy of expensing exploration and evaluation expenditure incurred by the Group subsequent to acquisition of the rights to explore and up to the completion of feasibility studies and the commercial viability of extracting the mineral resource is demonstrable;
(iii) Non-cash share-based payments benefit totalling $368,714 (2025: expense $4,309,932) relating to performance rights on issue. The fair value of rights are measured at grant date and recognised over the period during which the rights holders become unconditionally entitled to the incentive securities. During the period, 4,992,500 and 6,190,000 unvested performance rights expired on 31 March 2026 and 30 June 2026, respectively, resulting in a reduction in the share-based payment expense recognised. This reduction was offset by the expense recognised on the grant of 9,022,500 Bankable DFS performance rights and 13,262,500 Construction and Finance performance rights; and
(iv) Business development expenses of $2,126,209 (2025: $2,247,815) which includes the Group's investor and shareholder relations activities including but not limited to public relations costs, marketing and digital marketing, broker and advisor fees, business development consultant fees and costs of the Group's ASX and AIM listings.
FINANCIAL POSITION
As at 30 June 2026, the Group had cash and cash equivalents of $25,124,630 (2025: $54,538,435) and no debt (2025: nil). The Group had net assets of $29,356,679 at 30 June 2026 (2025: $55,387,701), a decrease of $26,031,022 or approximately 89% compared with the previous year. This is largely attributable to the decrease in cash reserves relating to exploration and evaluation spend on the Project to complete the DFS.
Business Strategies and Prospects for Future Financial Years
The objective of the Group is to create long-term shareholder value through the development of technically and economically viable mineral deposits at Kasiya.
To date, the Group has not commenced production of any minerals at Kasiya. To achieve its objective, the Group intends, over the medium term to conduct further development and permitting activities at Kasiya and to continue with ongoing discussions with potential offtake partners.
These activities are inherently risky and the Board is unable to provide certainty that any or all of these developments will be achieved. The material business risks faced by the Group that are likely to have an effect on the Group's future prospects, and how the Group manages these risks, include:
· Development Risk - During the period, the Company completed a DFS for the Project, which demonstrated the potential economic viability of the Project based on the assumptions, estimates and inputs used in the DFS. However, the Project remains subject to a number of development risks before a decision to mine can be made and commercial production is achieved. The next phase of technical work is expected to include Front-End Engineering Design (FEED), which will further develop and refine the engineering design, capital and operating cost estimates, execution strategy and development schedule for the Project. There can be no assurance that FEED or subsequent engineering, optimisation or development activities will confirm the assumptions or outcomes of the DFS, or that they will not identify additional technical requirements, increased capital or operating costs, delays or other matters that adversely affect the Project's economics. The development of the Project will also depend on, among other things, obtaining all required approvals and licences, securing appropriate financing and offtake arrangements, finalising suitable commercial and fiscal arrangements and successfully constructing, commissioning and ramping up the Project, as discussed in further detail below. There can be no assurance that the Project will ultimately be developed or brought into production on the timing, cost or operating assumptions contemplated by the DFS, or at all. Any material deterioration in the Project's economics, delay in development or inability to successfully develop the Project may have a material adverse effect on the Company's operations, financial performance and the value of its securities;
· Sovereign Risk - The Group's operations in the Republic of Malawi are exposed to various levels of political, economic and other risks and uncertainties. The Republic of Malawi is a developing country and economy which does not have an established mining industry. There can be no assurances that the future political developments in Malawi will not directly impact the Group's operations. Further, the Company has submitted an application for a large-scale mining licence (ML) to secure the mineral deposits required for mining, including the licence areas covered by the DFS and the Scoping Study. As at the date of this report, the ML application remains pending. There is no certainty that the ML will be granted or, if granted, that it will be granted on terms favourable to the Company.
· Failure to obtain the ML, or the grant of the ML on terms or conditions that are unfavourable to the Company, could materially adversely affect the viability of the Project and the value of the Company's securities.
Under the Malawi Mines and Minerals Act, 2023 (Mines Act), the Government of Malawi has a right to equity ownership in respect of large-scale mining licences (>5Mt mined per annum or >US$250 million in capital expenditure), with the extent and terms of such ownership subject to negotiation, likely as part of any future Mine Development Agreement (MDA). An MDA may also provide an opportunity to agree and clarify the fiscal regime applicable to the Project, including the treatment of certain taxes and any potential deviation from applicable Malawian tax laws. In particular, this may include the application of the existing resource rent tax (RRT) or a proposed supernormal profits tax (SPT) that could replace the RRT. Under the proposed SPT regime, profits of up to MWK10 billion (approximately US$6 million as at the date of this report) would be taxed at the standard corporate income tax rate of 30%, with profits exceeding MWK10 billion subject to a higher rate of 40%.
As at the date of this report, the Company has not entered into an MDA. There is no certainty that an MDA will be entered into or, if entered into, that its terms will be favourable to the Company or the Project. Any requirement for unfavourable terms in relation to Government equity participation, or the application of an unfavourable fiscal regime, including application of RRT or SPT, could materially adversely affect the economics and commercial viability of the Project and, consequently, the value of the Company's securities.
· Operational Risk - The potential commissioning, ramp-up and production at Kasiya are subject to operational risks that could adversely affect the quantity and quality of any potential rutile, graphite and REC produced, or increase production costs. The Company is currently progressing the development of the Project on an owner-operated basis. This may result in delays to the proposed development of the Project and could adversely affect the Company's ability to secure future financing, which may have a material adverse effect on the Company's operations, financial performance and the value of its securities. Further, the Company is currently seeking both binding and non-binding offtake arrangements for the suite of products expected to be produced from the Project. There can be no assurance that suitable counterparties will be identified, or that binding offtake agreements for all products will be concluded on commercially favourable terms. Failure to secure appropriate offtake arrangements could adversely affect the financing, development and commercial viability of the Project and may have a material adverse effect on the value of the Company's securities;
· Capital and Funding Risk - The ongoing development of the Group's mineral properties will require substantial additional financing. Failure to obtain sufficient financing may result in delaying or indefinite postponement of further development of the Group's mineral properties or even a loss of property interest. There can be no assurance that additional capital or other types of financing will be available if needed or that, if available, the terms of such financing will be favourable to the Group;
· Commodity Price and Foreign Exchange Risks - The price of rutile, graphite, rare earths and other commodities fluctuates widely and is affected by numerous factors beyond the control of the Group. Future production, if any, from the Group's mineral properties will be dependent upon the price of rutile and graphite and other commodities being adequate to make these properties economic.
Current and planned development activities are predominantly denominated in US dollars and the Group's ability to fund these activities may be adversely affected if the Australian dollar continues to fall against the US Dollar. The Group currently does not engage in any hedging or derivative transactions to manage commodity price or foreign exchange risk. As the Group's operations change, this policy will be reviewed periodically; and
· Global Financial Conditions Risk - Many industries, including the mineral resource industry, are impacted by these market conditions. Some of the key impacts include contraction in credit markets resulting in a widening of credit risk, devaluations and high volatility in global equity, commodity, foreign exchange and precious metal markets, and a lack of market liquidity. Due to the current nature of the Group's activities, a slowdown in the financial markets or other economic conditions may adversely affect the Group's growth and ability to finance its activities.
SIGNIFICANT CHANGES IN THE STATE OF AFFAIRS
(i) On 21 January 2026, Sovereign announced that it had recovered a heavy REC from the Kasiya rutile tailings stream. Preliminary analysis confirmed Kasiya monazite to contain exceptionally elevated levels of heavy rare earth elements DyTb and Y;
(ii) On 17 February 2026, Sovereign announced that it had signed non-binding MOU with Traxys North America for the marketing of graphite from Kasiya which targeted 40,000 tonnes per annum of graphite concentrate for Stage 1 (Years 1-5) and up to 80,000 tonnes per annum thereafter;
(iii) On 16 April 2026, Sovereign announced results of the DFS for of Kasiya which reaffirmed Kasiya's potential to become a large, low-cost producer of strategic minerals; and
(iv) On 17 April 2026, the Company issued 9,022,500 shares on the conversion of the Bankable DFS performance rights.
There are no significant changes in the state of affairs of the Group during the year not otherwise disclosed in this report.
SIGNIFICANT POST BALANCE DATE EVENTS
(i) On 8 July 2026, announced that it was advancing a U.S.-focused strategy following the receipt of a notification from Rio Tinto that it had not exercised its option to elect to become operator of Kasiya. In its notice to the Company, Rio Tinto advised that its decision reflected its change in corporate strategy regarding its titanium business and not a change the fundamentals, economics or strategic importance of Kasiya as highlighted in the Kasiya DFS, which was completed with technical input from Rio Tinto; and
(ii) On 9 September 2026, Sovereign announced results of the Scoping Study for recovery of the heavy REC which confirmed Kasiya's potential as globally significant and strategic source of critical rare earths.
At the date of this report, there are no other matters or circumstances which have arisen since 30 June 2026 that have significantly affected or may significantly affect:
· the operations, in financial years subsequent to 30 June 2026 of the Group;
· the results of those operations, in financial years subsequent to 30 June 2026 of the Group; or
· the state of affairs, in financial years subsequent to 30 June 2026 of the Group.
PRINCIPAL ACTIVITIES
The principal activities of the Group during the year consisted of the development of Kasiya. No significant change in the nature of these activities occurred during the year.
DIVIDENDS
No dividends have been declared, provided for or paid in respect of the financial year ended 30 June 2026 (30 June 2025: nil).
LOSS PER SHARE
|
|
2026 |
2025 |
|
Basic and diluted loss per share |
(3.95) |
(6.62) |
DIRECTORS
The names of Directors in office at any time during or since the end of the financial year are:
Current Directors
Mr Benjamin Stoikovich Chair
Mr Frank Eagar Managing Director and CEO
Mr Ian Middlemas Non-Executive Director
Dr Julian Stephens Non-Executive Director
Mr Mark Pearce Non-Executive Director
Mr Nigel Jones Non-Executive Director
Unless otherwise disclosed, Directors held their office from 1 July 2025 until the date of this report.
CURRENT DIRECTORS AND OFFICERS
Benjamin Stoikovich
Chair (Committee: ESG Member)
Qualifications - B.Eng, M.Eng, M.Sc, CEng, CEnv
Mr Stoikovich is an experienced mining executive and corporate finance professional residing in London. Mr Stoikovich is currently the Chief Executive Officer of GreenX Metals Limited (ASX: GRX) and was formerly a Director of the Mining and Metals Corporate Finance Division of Standard Chartered Bank in London, with extensive experience in financing the development of African mining projects and exposure to the mineral sands sector.
Mr Stoikovich started his career as a mining engineer with BHP Billiton in Australia, gaining broad experience across mine operations management and qualifying as a mine manager. He holds a post graduate degree in Environmental Engineering and UK professional designation as a Chartered Environmentalist (CEnv) with wide ranging experience of managing the environmental, social and sustainability aspects of mining projects across the life-cycle and the ESG requirements of the investment community. Mr Stoikovich was appointed a Director of the Company on 13 October 2020. During the three year period to the end of the financial year, Mr Stoikovich held a directorship in GreenX Metals Limited (June 2013 - present).
Frank Eagar
Managing Director and CEO (Committee: ESG Member)
Qualifications - B.Com, CA
Mr Eagar has over 20 years' experience in the financing, permitting, development and operation of mining projects with a strong focus in southern Africa.
Mr Eagar is a Chartered Accountant who has gained extensive corporate, commercial and technical experience in the mining sector throughout his career. Mr Eagar has previously held a number of senior executive positions in the resources sector, more recently with African mining focused private equity firm AMED Funds which included acting as Chief Financial Officer (CFO) for AMED's controlled company, Central Copper Resources PLC (Central Copper).
Prior to Central Copper, Mr Eagar was the CEO (and prior to that the CFO) of Baobab Steel Limited (Baobab) another AMED controlled company, where he managed the completion of a DFS and a joint venture with the World Bank's IFC to procure strategic investors and raise project finance for Baobab's US$1 Billion, fully permitted, integrated 500ktpa Steel and Vanadium Project in Mozambique.
Mr Eagar joined Sovereign in December 2022 as General Manager in Malawi, where he has already expanded the team with a focus on Malawian nationals, developed strong relationships with Government and demonstrated a clear understanding of the Kasiya Project and its development landscape. Mr Eagar was appointed as Managing Director and CEO of Sovereign Metals Limited on 20 October 2023. During the three year period to the end of the financial year, Mr Eagar did not hold any other directorships in publicly listed companies.
Ian Middlemas
Non-Executive Director (Committee: Audit Member)
Qualifications - B.Com, CA
Mr Middlemas is a Chartered Accountant and holds a Bachelor of Commerce degree. He worked for a large international Chartered Accounting firm before joining the Normandy Mining Group where he was a senior group executive for approximately 10 years. He has had extensive corporate and management experience, and is currently a director of a number of publicly listed companies in the resources sector.
Mr Middlemas was appointed a Director of Sovereign Metals Limited on 20 July 2006. During the three year period to the end of the financial year, Mr Middlemas has held directorships in GBM Resources Limited (June 2025 - present), NGX Limited (April 2021 - present), Constellation Resources Limited (November 2017 - present), Apollo Minerals Limited (July 2016 - present), Berkeley Energia Limited (April 2012 - present), GreenX Metals Limited (August 2011 - present), Salt Lake Potash Limited (Receivers and Managers Appointed) (January 2010 - present), Equatorial Resources Limited (November 2009 - present), Odyssey Gold Limited (September 2005 - present) and Terra Metals Limited (October 2013 - June 2026).
Julian Stephens
Non-Executive Director
Qualifications - B.Sc (Hons), PhD, MAIG
Dr Stephens originally identified and secured the Malawi properties acquired by Sovereign in 2012. He has since been closely involved with the subsequent exploration and development of these projects, including the discovery of the Kasiya rutile deposit.
Dr Stephens has extensive experience in the resources sector having spent in excess of 25 years in board, executive management, senior operational and economic geology research roles for a number of companies. He has spent over a decade working on African projects, particularly projects in Malawi. Dr Stephens holds a PhD from James Cook University, Queensland and is a member of the Australian Institute of Geoscientists.
Dr Stephens was appointed a Director of Sovereign Metals Limited on 22 January 2016. On 27 June 2016 Dr Stephens was appointed Managing Director of the Company and on 20 October 2023 he was appointed as a Non-Executive Director. During the three year period to the end of the financial year, Dr Stephens held a directorship in Viking Mines Limited (March 2025 - present).
Mark Pearce
Non-Executive Director (Committee: Audit Chair)
Qualifications - B.Bus, CA, FCIS, FFin
Mr Pearce is a Chartered Accountant and is currently a director of several listed companies that operate in the resources sector. He has had considerable experience in the formation and development of listed resource companies. Mr Pearce is also a Fellow of the Institute of Chartered Secretaries and a member of the Financial Services Institute of Australasia.
Mr Pearce was appointed a Director of Sovereign Metals Limited on 20 July 2006. During the three year period to the end of the financial year, Mr Pearce has held directorships in Zinc of Ireland Limited (April 2026 - present), NGX Limited (April 2021 - present), Constellation Resources Limited (July 2016 - present), GreenX Metals Limited (August 2011 - present), Equatorial Resources Limited (November 2009 - present) and Terra Metals Limited (Alternate Director) (June 2022 - January 2026).
Nigel Jones
Non-Executive Director (Committees: ESG Chair, Audit Member)
Qualifications - MA (Oxon); alumnus of London Business School (corporate finance programme)
Mr Jones has over 30 years of mining industry experience with 22 years in a number of senior roles at Rio Tinto Group, where most recently, Mr Jones was Managing Director of Rio Tinto's Simandou iron ore project, one of the world's largest proposed mining developments.
In this role, he was accountable for all aspects of the project's development, including its complex ESG strategy. Such aspects included impacts on natural ecosystems, biodiversity, and community and government relations.
Mr Jones was also a member of the senior leadership team of the Energy and Minerals product group, which incorporated Rio Tinto's titanium dioxide feedstock businesses in Canada and southern Africa. Prior roles in Rio Tinto included Head of Business Development, Head of Business Evaluation and Managing Director of the group's Marine operations.
Mr Jones was appointed a Director of Sovereign Metals Limited on 10 February 2022. During the three year period to the end of the financial year, Mr Jones did not hold any other directorships in publicly listed companies.
Mr Dylan Browne
Chief Financial Officer) and Company Secretary
Qualifications - B.Com, CA, AGIA ACG
Mr Browne is a Chartered Accountant and an Associate Member of the Governance Institute of Australia (Chartered Secretary). He currently serves as Company Secretary for a number of ASX, London and European-listed companies operating in the resources sector. He commenced his career with a large international accounting firm and has since held senior corporate and company secretarial roles with a number of exploration and development companies in the resources sector, based in London and Perth, including GreenX Metals Limited, Berkeley Energia Limited, Apollo Minerals Limited and Papillon Resources Limited.
Mr Browne successfully managed the listing of Prairie Mining Limited (now GreenX Metals Limited) on the Main Market of the London Stock Exchange (LSE) and the Warsaw Stock Exchange, and oversaw Berkeley Energia Limited's listings on the Main Market of the LSE and the Spanish Stock Exchanges. Mr Browne was appointed Company Secretary of the Company on 29 April 2021.
INFORMATION ON DIRECTORS' INTERESTS IN SECURITIES OF SOVEREIGN
As at the date of this report, the Directors' interests in the securities of the Company are as follows:
|
|
Interest in Securities at the Date of this Report |
|
|
Current Directors |
Ordinary Shares(1) |
Performance Rights(2) |
|
Benjamin Stoikovich |
5,090,000 |
1,550,000 |
|
Frank Eagar |
2,000,000 |
2,000,000 |
|
Ian Middlemas |
16,500,000 |
- |
|
Julian Stephens |
13,157,518 |
600,000 |
|
Mark Pearce |
4,461,151 |
650,000 |
|
Nigel Jones |
525,000 |
250,000 |
Notes:
(1) "Ordinary Shares" means fully paid ordinary shares in the capital of the Company; and
(2) "Performance Rights -means an unlisted performance right that converts to one Share in the capital of the Company upon satisfaction of the relevant milestone.
CONVERTIBLE SECURITIES
At the date of this report 13,262,500 Performance Rights subject to the Construction and Finance Milestone that expire on 30 June 2028 have been issued by the Company over unissued capital.
During the year ended 30 June 2026 and up to the date of this report, 9,022,500 (2025: nil) ordinary shares have been issued as a result of the conversion of performance rights.
MEETINGS OF DIRECTORS
The following table sets out the number of meetings of the Company's Directors held during the year ended 30 June 2026, and the number of meetings attended by each Director.
|
|
Board Meetings |
ESG Committee |
Audit Committee |
|||
|
Current Directors |
Eligible to Attend |
Number |
Eligible to Attend |
Number |
Eligible to Attend |
Number |
|
Benjamin Stoikovich |
2 |
2 |
1 |
1 |
- |
- |
|
Frank Eagar |
2 |
2 |
1 |
1 |
- |
- |
|
Ian Middlemas |
2 |
2 |
- |
- |
2 |
2 |
|
Julian Stephens |
2 |
2 |
- |
- |
- |
- |
|
Mark Pearce |
2 |
2 |
- |
- |
2 |
2 |
|
Nigel Jones |
2 |
2 |
1 |
1 |
2 |
2 |
The Board as a whole currently performs the functions of a Risk Committee, Nomination Committee and Remuneration Committee. However this will be reviewed should the size and nature of the Company's activities change.
COMMITTEE MEMBERSHIPS
As at the date of this report, the Company has an Audit Committee and an ESG Committee of the board of directors.
An Audit Committee has been established to oversee the Company's financial reporting and quality of the audit conducted by the external auditors.
The ESG Committee was established to support the Company's ongoing commitment to environmental, health and safety, corporate social responsibility, corporate governance, sustainability and other public policy matters relevant to the Company.
Please refer to the Corporate Governance section on page 64 for further discussion on the Company's Corporate Governance Statement and policies.
REMUNERATION REPORT (AUDITED)
This Remuneration Report, which forms part of the Directors' Report, sets out information about the remuneration of Key Management Personnel (KMP) of the Group.
Details of KMP
The KMP of the Group during or since the end of the financial year is as follows:
Executives
Mr Benjamin Stoikovich Chair
Mr Frank Eagar Managing Director and CEO
Mr Robert Slater Chief Operating Officer
Mr Sapan Ghai Chief Commercial Officer
Mr Dylan Browne CFO and Company Secretary
Mr Paul Marcos Head of Project Development
Directors
Mr Ian Middlemas Non-Executive Director
Dr Julian Stephens Non-Executive Director
Mr Mark Pearce Non-Executive Director
Mr Nigel Jones Non-Executive Director
Unless otherwise disclosed, the KMP held their position from 1 July 2025 until the date of this report.
Remuneration Policy
The Group's remuneration policy for its KMP has been developed by the Board taking into account the size of the Group, the size of the management team for the Group, the nature and stage of development of the Group's current operations, and market conditions and comparable salary levels for companies of a similar size and operating in similar sectors.
In addition to considering the above general factors, the Board has also placed emphasis on the following specific issues in determining the remuneration policy for KMP: (a) the Group is currently focused on undertaking development and exploration activities at Kasiya; (b) risks associated with small cap resource companies whilst in the development and exploration phase; (c) other than profit which may be generated from asset sales, the Company does not expect to be undertaking profitable operations until sometime after the commencement of commercial production at Kasiya.
The objective of the Group's remuneration structure reward framework is to ensure that reward for performance is competitive and appropriate for the results delivered. The remuneration framework provides a mix of fixed and variable remuneration, which incorporates a blend of short and long-term incentives. There is a deliberate emphasis on lower fixed base and higher variable results-based remuneration to ensure that management focus is aligned with that of shareholders. This has been achieved by ensuring that a significant proportion of executive's remuneration is 'at risk'. Long-term incentives are based on Company milestones linked to long term value drivers.
Executive Remuneration
The Group's remuneration policy is to provide a fixed remuneration component and a performance-based component (short-term incentive and long-term incentive). The Board believes that this remuneration policy is appropriate given the considerations discussed in the section above and is appropriate in aligning executives' objectives with shareholder and business objectives.
Fixed Remuneration
Fixed remuneration consists of base salaries, as well as employer contributions to superannuation funds and other non-cash benefits. Fixed remuneration is reviewed annually by the Board. The process consists of a review of company and individual performance, relevant comparative remuneration externally and internally and, where appropriate, external advice on policies and practices.
Performance Based Remuneration - Short Term Incentive
Some executives are entitled to an annual cash bonus upon achieving various key performance indicators (KPI's), as set by the Board. Having regard to the current size, nature and opportunities of the Company, the Board has determined that these KPI's will include measures such as the successful completion of development activities (e.g. completion of feasibility studies), environmental and social activities (e.g. sustainability and conservation), exploration and technical activities (e.g. completion of exploration programs within budgeted timeframes and costs), corporate activities (e.g. recruitment of key personnel) and business development activities (e.g. project acquisition and capital raisings). The Board assesses performance against these criteria annually.
During the 2026 financial year, a total bonus sum of $284,292 (2025: $622,020), representing 50% of KMP entitlement accrued but not yet paid to executives. Specific KPIs are set for each KMP and are designed to drive successful business outcomes.
Performance Based Remuneration - Long Term Incentive
The Group has a long-term equity incentive plan (LTIP) comprising the "Sovereign Employee Equity Incentive Plan" (Incentive Plan) to reward KMP and other key employees and contractors for long-term performance of the Group. The Incentive Plan provides for the issuance of unlisted performance rights (Performance Rights) and unlisted incentive options (Incentive Options) to eligible employees and contractors as part of their remuneration and incentive arrangements in order to attract and retain their services and to provide an incentive linked to the performance of the Group.
To achieve its corporate objectives, the Group needs to attract, incentivise, and retain its KMP and other key employees and contractors. The Board believes that grants made to eligible participants under the Incentive Plan is a useful tool to underpin the Group's employment and engagement strategy, and enables the Group to: (a) recruit, incentivise and retain KMP and other key employees and contractors needed to achieve the Group's business objectives; (b) link the reward of key staff with the achievement of strategic goals and the long-term performance of the Group; (c) align the financial interest of participants of the Incentive Plan with those of Shareholders; and (d) provide incentives to participants of the Incentive Plan to focus on superior performance that creates Shareholder value.
(i) Performance Rights
The Incentive Plan provides for the issuance of Performance Rights to eligible participants which, upon satisfaction of the relevant performance conditions attached to the Performance Rights, will result in the issue of an Ordinary Share for each Performance Right. Performance Rights are issued for no consideration and no amount is payable upon conversion thereof.
Performance Rights granted under the Incentive Plan to eligible participants will be linked to the achievement by the Group of certain performance conditions as determined by the Board from time to time. These performance conditions must be satisfied in order for the Performance Rights to vest. Upon Performance Rights vesting, Ordinary Shares are automatically issued for no consideration. If a performance condition of a Performance Right is not achieved by the expiry date then the Performance Right will lapse.
During the financial year, 14,455,000 (2025: 3,625,000) Performance Rights were granted to KMP. A total of 5,942,500 (2025: nil) Performance Rights held by KMP vested and converted in Ordinary Shares during the year. A further 13,905,000 (2025: nil) Performance Rights held by KMP lapsed during the financial year. The Performance Rights granted to KMP during the year included the following:
· 5,942,500 Performance Rights subject to the Bankable DFS that expire on 30 June 2026 ( converted into Ordinary Shares during the year); and
· 8,512,500 Performance Rights subject to the Construction and Finance Milestone that expire on 30 June 2028.
(ii) Incentive Options
The Incentive Plan also provides for the issuance of Incentive Options to eligible participants. The Board's policy is to grant Incentive Options to KMP with exercise prices at or above market share price (at the time of agreement). As such, the Incentive Options granted to KMP are generally only of benefit if the KMP performs to the level whereby the value of the Group increases sufficiently to warrant exercising the Incentive Options granted.
Other than service-based vesting conditions (if any) and the exercise price required to exercise the Incentive Options, there are generally no additional performance criteria on the Incentive Options granted to KMP, as given the speculative nature of the Group's activities and the small management team responsible for its running, it is considered that the performance of the KMP and the performance and value of the Group are closely related. The Group prohibits executives from entering into arrangements to limit their exposure to Incentive Options granted as part of their remuneration package.
During the financial year, no (2025: nil) Incentive Options were granted, exercised or lapsed to KMP.
Non-Executive Director Remuneration
The Board policy is to remunerate Non-Executive Directors at market rates for comparable companies for time, commitment and responsibilities. Given the current size, nature and risks of the Company, Performance Rights Incentive Options have been used to attract and retain Non-Executive Directors, where deemed appropriate. The Board determines payments to the Non-Executive Directors and reviews their remuneration annually, based on market practice, duties and accountability. Independent external advice is sought when required.
The maximum aggregate amount of fees that can be paid to Non-Executive Directors is subject to approval by shareholders at a General Meeting and is currently $500,000. Director's fees paid to Non-Executive Directors accrue on a daily basis. Fees for Non-Executive Directors are not linked to the performance of the Group. However, to align Directors' interests with shareholder interests, the Directors are encouraged to hold shares in the Company and Non-Executive Directors have received Performance Rights and Incentive Options in order to secure their services and as a key component of their remuneration. The Company prohibits Non-Executive Directors from entering into arrangements to limit their exposure to convertible securities granted as part of their remuneration package.
Fees for the Chair are presently £50,000 ($95,000) per annum (2025: £50,000 ($95,000)) and fees for Non-Executive Directors' are $50,000 to £40,000 ($82,000) per annum (2025: $50,000 to £40,000 ($76,000) per annum). Non-Executive Directors may receive additional remuneration for other services provided to the Company, including but not limited to, membership of committees including the Audit and ESG Committees. The Chair of the ESG Committee currently receives £10,000 ($20,000) (2025: £10,000 ($20,000)) for chairing the ESG Committee.
Relationship between Remuneration of KMP and Shareholder Wealth
During the Company's exploration and development phases of its business, the Board anticipates that the Company will retain earnings (if any) and other cash resources for the ongoing development and exploration and of the Kasiya project. Accordingly, the Company does not currently have a policy with respect to the payment of dividends and returns of capital. Therefore, there was no relationship between the Board's policy for determining, or in relation to, the nature and amount of remuneration of KMP and dividends paid and returns of capital by the Company during the current and previous four financial years.
The Board did not determine the nature and amount of remuneration of KMP by reference to changes in the price at which shares in the Company traded between the beginning and end of the current and the previous four financial years. Discretionary annual cash bonuses are based upon achieving various non-financial KPI's that are not based on share price or earnings, as discussed above. However, as noted above, a number of KMP have received Performance Rights and/or Incentive Options which generally will be of greater value to KMP if the value of the Group's shares increases (subject to vesting conditions being met).
Relationship between Remuneration of KMP and Earnings
As discussed above, the Company is currently undertaking development and exploration activities and does not expect to be undertaking profitable operations (other than by way of material asset sales, none of which is currently planned) until sometime after the successful commercialisation, production and sales of commodities from one or more of its projects. Accordingly the Board does not consider earnings during the current and previous four financial years when determining, and in relation to, the nature and amount of remuneration of KMP.
Remuneration of KMP
Details of the nature and amount of each element of the remuneration of each KMP of the Company for the year ended 30 June 2026 and 30 June 2025 are as follows:
|
2026 |
Short-Term Benefits |
Post Employ-ment Super-annuation |
Non-Cash Share-based payments (Rights) |
Other Non-Cash Benefits $ |
Total |
Percentage Performance Related % |
|
|
Salary & Fees |
Cash Bonus |
||||||
|
Executives |
|||||||
|
Benjamin Stoikovich(1) |
241,272 |
- |
- |
90,315 |
- |
331,587 |
27 |
|
Frank Eagar |
436,079 |
110,911 |
- |
359,402 |
- |
906,392 |
52 |
|
Robert Slater |
581,234 |
148,381 |
- |
(51,467) |
- |
678,148 |
14 |
|
Sapan Ghai |
443,590 |
- |
- |
(111,346) |
- |
332,244 |
- |
|
Dylan Browne(2) |
- |
- |
- |
(184,276) |
- |
(184,276) |
- |
|
Paul Marcos |
300,000 |
25,000 |
30,000 |
(120,520) |
- |
234,480 |
- |
|
Non-Executive Directors |
|
|
|
|
|
|
|
|
Ian Middlemas |
50,000 |
- |
6,000 |
- |
- |
56,000 |
- |
|
Julian Stephens(3) |
110,750 |
- |
6,000 |
140,337 |
- |
257,087 |
55 |
|
Mark Pearce |
50,000 |
- |
6,000 |
(36,014) |
- |
19,986 |
- |
|
Nigel Jones |
96,100 |
- |
- |
65,611 |
- |
161,711 |
41 |
|
2,309,025 |
284,292 |
48,000 |
152,042 |
- |
2,793,359 |
|
|
|
2025 |
Short-Term Benefits |
Post Employ-ment Super-annuation |
Non-Cash Share-based payments (Rights) |
Other Non-Cash Benefits $ |
Total |
Percentage Performance Related % |
|
|
Salary & Fees |
Cash Bonus |
||||||
|
Executives |
|||||||
|
Benjamin Stoikovich(1) |
246,079 |
- |
- |
567,628 |
- |
813,707 |
70 |
|
Frank Eagar |
458,308 |
195,993 |
- |
731,594 |
- |
1,385,895 |
67 |
|
Robert Slater |
614,089 |
261,854 |
- |
435,597 |
- |
1,311,540 |
53 |
|
Sapan Ghai |
354,834 |
59,745 |
- |
338,091 |
- |
752,670 |
53 |
|
Dylan Browne(2) |
- |
54,428 |
- |
287,783 |
- |
342,211 |
100 |
|
Paul Marcos |
300,000 |
50,000 |
27,125 |
141,311 |
- |
518,436 |
37 |
|
Non-Executive Directors |
|||||||
|
Ian Middlemas |
50,000 |
- |
5,750 |
- |
- |
55,750 |
- |
|
Julian Stephens |
50,000 |
- |
5,750 |
87,551 |
- |
143,301 |
61 |
|
Mark Pearce |
50,000 |
- |
5,750 |
149,343 |
- |
205,093 |
73 |
|
Nigel Jones |
104,611 |
- |
- |
78,586 |
- |
183,197 |
43 |
|
2,227,921 |
622,020 |
44,375 |
2,817,484 |
- |
5,711,800 |
||
Notes:
(1) In addition to Directors fees, Selwyn Capital Limited (Selwyn), an company of which Mr Stoikovich is a director and beneficial shareholder, was paid, or is payable, $143,303 (2025: $144,846) for additional services provided in respect of corporate and business development activities which is included in Mr Stoikovich's salary and fee amount.
(2) Mr Browne provided services through a services agreement with Apollo Group Pty Ltd (Apollo Group) a company of which Mr Mark Pearce is a Director and beneficial shareholder of. Mr Browne is an employee of Apollo Group. During the year, Apollo Group was paid or is payable $390,000 (2025: $390,000) for the provision of administrative, secretarial and corporate services to the Group.
(3) In addition to Directors fees, JRS Geology Pty Ltd (JRS Geology), a company of which Dr Stephens is a director and beneficial shareholder, was paid, or is payable, $60,750 in 2026 for additional services provided in respect of geological activities which is included in Dr Stephen's salary and fee amount.
Loans with KMP
No loans were provided to or received from KMP during the year ended 30 June 2026 (2025: Nil).
Other Transactions with KMP
Selwyn, a company of which Mr Stoikovich is a director and beneficial shareholder, is engaged under an agreement to provide consulting services to the Company, on a rolling 12-month term that either party may terminate with one month written notice. Selwyn receives a daily rate of £1,000 under the consulting agreement. These services provided during the financial year amounted to $143,303 (2025: $144,846).
JRS Geology, a company of which Dr Stephens is a director and beneficial shareholder, is also engaged under an agreement to provide geological consulting services to the Company that either party may terminate with one month written notice. JRS Geology receives a hourly rate of $2,000 under the consulting agreement. These services provided during the financial year amounted to $60,750.
Apollo Group, a company of which Mr Mark Pearce is a director and beneficial shareholder, was paid, or is payable, $390,000 (2025: $390,000) for the provision of provision of administrative, secretarial and corporate services provided during the year. This item has been recognised as an expense in profit and loss. The amount is based on a current monthly retainer of $32,500 (2025: $32,500) due and payable in advance, with no fixed term, and is able to be terminated by either party with one month's notice.
Performance Rights Granted to KMP
Details of the value of Performance rights granted, vested, converted or lapsed for each KMP of the Group during the 2026 financial year are as follows:
|
|
|
|
|
Value of rights granted during the year(1) |
Value of rights converted during the year(2) |
Value of rights included in remuneration for the year |
|
2026 |
No. of rights granted |
No. of rights vested |
No. of rights lapsed |
|||
|
Executives |
||||||
|
Benjamin Stoikovich |
2,450,000 |
900,000 |
(2,450,000) |
1,837,500 |
675,000 |
90,315 |
|
Frank Eagar |
3,500,000 |
1,500,000 |
(3,200,000) |
2,625,000 |
1,125,000 |
359,402 |
|
Robert Slater |
1,900,000 |
600,000 |
(1,650,000) |
1,339,500 |
423,000 |
(51,467) |
|
Sapan Ghai |
1,580,000 |
630,000 |
(1,580,000) |
1,113,900 |
444,150 |
(111,346) |
|
Dylan Browne |
1,450,000 |
675,000 |
(1,450,000) |
1,022,250 |
475,875 |
(184,276) |
|
Paul Marcos |
875,000 |
437,500 |
(875,000) |
616,875 |
308,438 |
(120,520) |
|
Non-Executive Directors |
||||||
|
Julian Stephens |
1,200,000 |
600,000 |
(1,200,000) |
900,000 |
450,000 |
140,337 |
|
Mark Pearce |
950,000 |
300,000 |
(950,000) |
712,500 |
225,000 |
(36,014) |
|
Nigel Jones |
550,000 |
300,000 |
(550,000) |
412,500 |
225,000 |
65,611 |
Notes:
(1) Determined at the time of grant per AASB 2.
(2) Determined at the time of conversion at the intrinsic value.
Details of Performance Rights granted by the Company to each KMP of the Group during the 2026 financial year are as follows:
|
Grant |
Expiry |
Exercise Price |
Grant Date Fair Value(1) |
No. Granted |
|
|
Executives |
|
|
|
|
|
|
Benjamin Stoikovich |
18 Feb 26 |
30 Jun 26 |
- |
0.750 |
900,000 |
|
18 Feb 26 |
30 Jun 28 |
- |
0.750 |
1,550,000 |
|
|
Frank Eagar |
18 Feb 26 |
30 Jun 26 |
- |
0.750 |
1,500,000 |
|
18 Feb 26 |
30 Jun 28 |
- |
0.750 |
2,000,000 |
|
|
Robert Slater |
14 Jan 26 |
30 Jun 26 |
- |
0.585 |
600,000 |
|
14 Jan 26 |
30 Jun 28 |
- |
0.585 |
1,300,000 |
|
|
Sapan Ghai |
14 Jan 26 |
30 Jun 26 |
- |
0.585 |
630,000 |
|
14 Jan 26 |
30 Jun 28 |
- |
0.585 |
950,000 |
|
|
Dylan Browne |
14 Jan 26 |
30 Jun 26 |
- |
0.585 |
675,000 |
|
14 Jan 26 |
30 Jun 28 |
- |
0.585 |
775,000 |
|
|
Paul Marcos |
14 Jan 26 |
30 Jun 26 |
- |
0.585 |
437,500 |
|
14 Jan 26 |
30 Jun 28 |
- |
0.585 |
437,500 |
|
|
Non-Executive |
|||||
|
Julian Stephens |
18 Feb 26 |
30 Jun 26 |
- |
0.750 |
600,000 |
|
18 Feb 26 |
30 Jun 28 |
- |
0.750 |
600,000 |
|
|
Mark Pearce |
18 Feb 26 |
30 Jun 26 |
- |
0.750 |
300,000 |
|
18 Feb 26 |
30 Jun 28 |
- |
0.750 |
650,000 |
|
|
Nigel Jones |
18 Feb 26 |
30 Jun 26 |
- |
0.750 |
300,000 |
|
18 Feb 26 |
30 Jun 28 |
- |
0.750 |
250,000 |
Notes:
(1) For details on the valuation of Unlisted Options and Performance Rights, including models and assumptions used, please refer to Note 16 of the financial statements.
Performance Rights Held by KMP
|
2026 |
Held at 1 July 2025 |
Granted as remuneration |
Rights Converted |
Lapsed and Expired |
Held at |
Vested and exercisable at 30 June 2026 |
|
Executives |
|
|
|
|
|
|
|
Benjamin Stoikovich |
2,450,000 |
2,450,0001 |
(900,000) |
(2,450,000) |
1,550,000 |
- |
|
Frank Eagar |
3,200,000 |
3,500,0001 |
(1,500,000) |
(3,200,000) |
2,000,000 |
- |
|
Robert Slater |
1,650,000 |
1,900,000 |
(600,000) |
(1,650,000) |
1,300,000 |
- |
|
Sapan Ghai |
1,580,000 |
1,580,000 |
(630,000) |
(1,580,000) |
950,000 |
- |
|
Dylan Browne |
1,450,000 |
1,450,000 |
(675,000) |
(1,450,000) |
775,000 |
- |
|
Paul Marcos |
875,000 |
875,000 |
(437,500) |
(875,000) |
437,500 |
- |
|
Non-Executive |
||||||
|
Julian Stephens |
1,200,000 |
1,200,000 |
(600,000) |
(1,200,000) |
600,000 |
- |
|
Mark Pearce |
950,000 |
950,000 |
(300,000) |
(950,000) |
650,000 |
- |
|
Nigel Jones |
550,000 |
550,000 |
(300,000) |
(550,000) |
250,000 |
- |
Shareholdings of KMP
|
2026 |
Held at 1 July 2025 |
Granted as remuneration |
Conversion of rights |
Net Other Change |
Held at 30 June 2026 |
|
Executives |
|
|
|
|
|
|
Benjamin Stoikovich |
4,190,000 |
- |
900,000 |
- |
5,090,000 |
|
Frank Eagar |
500,000 |
- |
1,500,000 |
- |
2,000,000 |
|
Robert Slater |
- |
- |
600,000 |
(300,000) |
300,000 |
|
Sapan Ghai |
1,714,000 |
- |
630,000 |
- |
2,344,000 |
|
Dylan Browne |
952,000 |
- |
675,000 |
- |
1,627,000 |
|
Paul Marcos |
750,000 |
- |
437,500 |
- |
1,187,500 |
|
Non-Executive |
|||||
|
Ian Middlemas |
16,500,000 |
- |
- |
- |
16,500,000 |
|
Julian Stephens |
13,557,518 |
- |
600,000 |
(1,000,000) |
13,157,518 |
|
Mark Pearce |
4,520,842 |
- |
300,000 |
(359,691) |
4,461,151 |
|
Nigel Jones |
225,000 |
- |
300,000 |
- |
525,000 |
Employment Contracts with KMP
Mr Frank Eagar, Managing Director and CEO, has a letter of employment with the Group which may be terminated by either party upon giving six months' advance notice, or payment of lieu thereof. Mr Eagar receives a fixed remuneration component of US$296,000 (2025: US$296,000) per annum and a discretionary annual bonus of up to US$74,000 (2025: US$74,000) to be paid upon successful completion of KPIs as determined by the Board.
Mr Robert Slater, Chief Commercial Officer, has a consulting agreement with the Group which may be terminated by either party upon giving six months' advance notice. Mr Slater receives a fixed remuneration component of US$33,000 (2025: US$33,000) per month and a discretionary annual bonus of up to 25% (2025: 25%)of the annual fixed remuneration component, to be paid upon successful completion of KPIs as determined by the Board.
Mr Sapan Ghai, Chief Commercial Officer, has a consulting agreement with the Group which may be terminated by either party upon giving one month advance notice. Mr Ghai receives a fixed remuneration component of £18,750 (2025; £18,750) per month.
Mr Paul Marcos, Head of Project Development, has a letter of employment with the Group which may be terminated by either party by giving three months' advance notice. Mr Marcos receives a fixed remuneration component of $300,000 (2025: $300,000) per annum plus superannuation with an annual bonus of up to $50,000 (2025: $50,000) payable upon successful completion of KPIs as determined by the Board.
All Directors have a letter of appointment confirming the terms and conditions of their appointment as a Director.
End of Remuneration Report
PROCEEDINGS ON BEHALF OF COMPANY
No person has applied for leave of court to bring proceedings on behalf of the Company or intervene in any proceedings to which the Company is a part for the purpose of taking responsibility on behalf of the Company for all or any part of those proceedings. The Company was not a party to any such proceedings during the year.
ENVIRONMENTAL REGULATION AND PERFORMANCE
The Group's operations are subject to various environmental laws and regulations under the relevant government's legislation. Full compliance with these laws and regulations is regarded as a minimum standard for all operations to achieve. Instances of environmental non-compliance by an operation are identified either by external compliance audits or inspections by relevant government authorities. There have been no significant known breaches by the Group during the financial year.
INDEMNIFICATION AND INSURANCE OF OFFICERS
The Company has entered into Deeds of Indemnity with the Directors indemnifying them against certain liabilities and costs to the extent permitted by law.
The Group has paid, or agreed to pay, a premium in respect of Directors' and Officers' Liability Insurance and Company Reimbursement policies for the 12 months ended 30 June 2026 and 2025, which cover all Directors and officers of the Group against liabilities to the extent permitted by the Corporations Act 2001. The policy conditions preclude the Group from any detailed disclosures including the premium amount paid.
NON-AUDIT SERVICES
During the financial year, the Company's current auditor, Ernst & Young provided non-audit services relating to income tax preparation and advice, totalling $25,000 (2025: $11,500). The Directors are satisfied that the provision of non-audit services is compatible with the general standard of independence for auditors imposed by the Corporations Act. The nature and scope of the non-audit services provided means that auditor independence was not compromised.
AUDITOR'S INDEPENDENCE DECLARATION
The lead auditor's independence declaration for the year ended 30 June 2026 has been received and can be found on page 25 of the Directors' Report.
This report is made in accordance with a resolution of the Directors made pursuant to section 298(2) of the Corporations Act 2001.
For and on behalf of the Directors
Frank Eagar
Managing Director and CEO
25 September 2026
CONSOLIDATED STATEMENT OF PROFIT OR LOSS AND OTHER COMPREHENSIVE INCOME
FOR THE YEAR ENDED 30 JUNE 2026
|
|
Notes |
2026 |
2025 |
|||||||
|
Continuing Operations |
|
|||||||||
|
Interest Income |
1,524,771 |
2,043,809 |
||||||||
|
Other expenses |
2(a) |
(170,922) |
(479,574) |
|||||||
|
Exploration and evaluation expenses |
(23,379,720) |
(33,897,375) |
||||||||
|
Corporate and administrative expenses |
(1,849,572) |
(1,549,452) |
||||||||
|
Share-based payment benefit/(expense) |
16 |
368,714 |
(4,309,932) |
|||||||
|
Business development expenses |
(2,126,209) |
(2,247,815) |
||||||||
|
Loss before income tax |
(25,632,938) |
(40,440,339) |
||||||||
|
Income tax expense |
3 |
- |
- |
|||||||
|
Loss for the year |
(25,632,938) |
(40,440,339) |
||||||||
|
Loss attributable to members of the parent |
(25,632,938) |
(40,440,339) |
||||||||
|
Other Comprehensive income, net of income tax: |
|
|||||||||
|
Items that may be reclassified subsequently to profit or loss |
|
|||||||||
|
Exchange differences on foreign entities |
(8,653) |
194,119 |
||||||||
|
Other comprehensive (loss)/income for the year, net of income tax |
(8,653) |
194,119 |
||||||||
|
Total comprehensive loss for the year |
(25,641,591) |
(40,246,220) |
||||||||
|
Total comprehensive loss attributable to members of Sovereign Metals Limited |
(25,641,591) |
(40,246,220) |
||||||||
|
Basic and diluted loss per share from continuing operations (cents per share) |
13 |
(3.95) |
(6.62) |
|||||||
|
CONSOLIDATED STATEMENT OF FINANCIAL POSITION AS AT 30 JUNE 2026 |
||||||||||
|
Notes |
2026 |
2025 |
||||||||
|
Current Assets |
|
|||||||||
|
Cash and cash equivalents |
12(b) |
25,124,630 |
54,538,435 |
|||||||
|
Other receivables |
4 |
494,956 |
1,771,002 |
|||||||
|
Other financial assets |
70,000 |
105,000 |
||||||||
|
Total Current Assets |
25,689,586 |
56,414,437 |
||||||||
|
|
|
|||||||||
|
Non-current Assets |
|
|||||||||
|
Property, plant and equipment |
5 |
1,700,518 |
1,852,383 |
|||||||
|
Exploration and evaluation assets |
6 |
5,086,129 |
5,086,129 |
|||||||
|
Total Non-current Assets |
6,786,647 |
6,938,512 |
||||||||
|
|
|
|||||||||
|
TOTAL ASSETS |
32,476,233 |
63,352,949 |
||||||||
|
|
||||||||||
|
Current Liabilities |
|
|||||||||
|
Trade and other payables |
7 |
2,894,581 |
7,749,922 |
|||||||
|
Provisions |
8 |
180,568 |
125,582 |
|||||||
|
Other financial liabilities |
9 |
44,405 |
46,621 |
|||||||
|
Total Current Liabilities |
3,119,554 |
7,922,125 |
||||||||
|
|
||||||||||
|
Non-Current Liabilities |
|
|||||||||
|
Other financial liabilities |
9 |
- |
43,123 |
|||||||
|
Total Non-Current Liabilities |
- |
43,123 |
||||||||
|
|
||||||||||
|
TOTAL LIABILITIES |
3,119,554 |
7,965,248 |
||||||||
|
NET ASSETS |
29,356,679 |
55,387,701 |
||||||||
|
|
||||||||||
|
EQUITY |
|
|||||||||
|
Contributed equity |
10 |
180,652,292 |
174,800,846 |
|||||||
|
Reserves |
11 |
(5,105,749) |
1,143,781 |
|||||||
|
Accumulated losses |
(146,189,864) |
(120,556,926) |
||||||||
|
TOTAL EQUITY |
29,356,679 |
55,387,701 |
||||||||
|
CONSOLIDATED STATEMENT OF CASH FLOWS FOR THE YEAR ENDED 30 JUNE 2026 |
||||||||||
|
|
Notes |
2026 |
2025 |
|||||||
|
Cash flows from operating activities |
|
|
|
|||||||
|
Interest received |
1,902,379 |
1,715,164 |
||||||||
|
Payments to suppliers and employees - exploration and evaluation |
(28,319,047) |
(30,042,677) |
||||||||
|
Payments to suppliers and employees - other |
(2,480,961) |
(4,551,699) |
||||||||
|
Net cash used in operating activities |
12(a) |
(28,897,629) |
(32,879,212) |
|||||||
|
|
||||||||||
|
Cash flows from investing activities |
|
|||||||||
|
Payments for purchase of plant and equipment |
(275,421) |
(1,023,642) |
||||||||
|
Net cash used in investing activities |
(275,421) |
(1,023,642) |
||||||||
|
|
||||||||||
|
Cash flows from financing activities |
|
|||||||||
|
Proceeds from issue of shares |
- |
59,174,395 |
||||||||
|
Share issue costs |
(20,717) |
(2,209,180) |
||||||||
|
Payments for finance lease |
(84,117) |
(63,482) |
||||||||
|
Net cash (used in)/from financing activities |
(104,834) |
56,901,733 |
||||||||
|
|
||||||||||
|
Net (decrease)/increase in cash and cash equivalents |
(29,277,884) |
22,998,879 |
||||||||
|
Net foreign exchange differences |
(135,922) |
(24,574) |
||||||||
|
Cash and cash equivalents at the beginning of the financial year |
54,538,436 |
31,564,130 |
||||||||
|
Cash and cash equivalents at the end of the financial year |
12(b) |
25,124,630 |
54,538,435 |
|||||||
CONSOLIDATED STATEMENT OF CHANGES IN EQUITY
FOR THE YEAR ENDED 30 JUNE 2026
|
|
Issued Capital |
Share-based Payments Reserve |
Other Equity Reserve |
Foreign Currency Translation Reserve |
Accumulated Losses |
Total Equity |
|
|
$ |
$ |
$ |
$ |
$ |
$ |
|
Balance at 1 July 2025 |
174,800,846 |
7,915,683 |
(7,336,678) |
564,776 |
(120,556,926) |
55,387,701 |
|
Net loss for the year |
- |
- |
- |
- |
(25,632,938) |
(25,632,938) |
|
Other comprehensive income |
|
|
|
|
|
|
|
Foreign currency translation |
- |
- |
- |
(8,653) |
- |
(8,653) |
|
Total comprehensive loss for the year |
- |
- |
- |
(8,653) |
(25,632,938) |
(25,641,591) |
|
Transactions with owners recorded directly in equity |
|
|
|
|
|
|
|
Share issue costs |
(20,717) |
- |
- |
- |
- |
(20,717) |
|
Expiry of unvested performance rights |
- |
(7,915,681) |
- |
- |
- |
(7,915,681) |
|
Transfer of SBP reserve on conversion of performance rights |
5,872,163 |
(5,872,163) |
- |
- |
- |
- |
|
Share-based payments expense |
- |
7,546,967 |
- |
- |
- |
7,546,967 |
|
Balance at 30 June 2026 |
180,652,292 |
1,674,806 |
(7,336,678) |
556,123 |
(146,189,864) |
29,356,679 |
|
Balance at 1 July 2024 |
117,835,631 |
3,605,751 |
(7,336,678) |
370,657 |
(80,116,587) |
34,358,774 |
|
Net loss for the year |
- |
- |
- |
- |
(40,440,339) |
(40,440,339) |
|
Other comprehensive income |
||||||
|
Foreign currency translation |
- |
- |
- |
194,119 |
- |
194,119 |
|
Total comprehensive loss for the year |
- |
- |
- |
194,119 |
(40,440,339) |
(40,246,220) |
|
|
||||||
|
Transactions with owners recorded directly in equity |
||||||
|
Issue of placement shares |
59,174,395 |
- |
- |
- |
- |
59,174,395 |
|
Share issue costs |
(2,209,180) |
- |
- |
- |
- |
(2,209,180) |
|
Share-based payments expense |
- |
4,309,932 |
- |
- |
- |
4,309,932 |
|
Balance at 30 June 2025 |
174,800,846 |
7,915,683 |
(7,336,678) |
564,776 |
(120,556,926) |
55,387,701 |
To view the full version of the 2026 Annual Report including the notes to the financial statements, please refer to https://api.investi.com.au/api/announcements/svm/4ff1a2bb-c5f.pdf
Competent Person Statements
Monazite Scoping Study
The information in this announcement that relates to the Scoping Study (including Infrastructure, Capital and Operating Costs, Production Target and economic analysis and other financial forecasts) exploration results and metallurgical testwork is extracted from an announcement dated 9 September 2026, which is available to view at www.sovereignmetals.com.au.
Sovereign confirms that a) it is not aware of any new information or data that materially affects the information included in the original announcement; b) all material assumptions included in the original announcement continue to apply and have not materially changed; and c) the form and context in which the relevant Competent Persons' findings are presented in this announcement have not been materially changed from the original announcement.
The information in this announcement that relates to the Mineral Resource Estimate (Monazite) is extracted from Sovereign's announcement dated 9 September 2026, which is available to view at www.sovereignmetals.com.au, and is based on, and fairly represents, information compiled by Mr Jeremy Witley, a Competent Person who is a member of the South African Council for Natural Scientific Professions (SACNASP Pr. Sci. Nat.), a Recognised Professional Organisation (RPO) included in a list promulgated by ASX from time to time. Mr Witley is a principal of MSA Group, an independent consulting company. Sovereign confirms that a) it is not aware of any new information or data that materially affects the information included in the original announcement; b) all material assumptions included in the original announcement continue to apply and have not materially changed; and c) the form and context in which the relevant Competent Persons' findings are presented in original announcement have not been materially changed from the disclosure in the original announcement.
TABLE 3: Kasiya 2026 Monazite Mineral Resource Estimate
|
Class |
Tonnes (Mt) |
Grade (%) |
|
Indicated |
386.9 |
0.0135 |
|
Inferred |
137.5 |
0.0125 |
|
Total |
524.4 |
0.0132 |
Notes:
1) The mineral resource is constrained to the Kasiya rutile and graphite DFS open pits to satisfy RPEEE
2) No cut-off is applied and the total volume within the DFS open pits will be processed with monazite concentrate being produced as a by-product of the Kasiya rutile and graphite production
3) The grade % is the in-situ grade of monazite mineral calculated from the recovered magnetic concentrate fraction of the HMS within the sand fraction (>45um <600um)
Definitive Feasibility Study
The information in this announcement that relates to the DFS (including Mine Engineering, Mine Scheduling, Processing, Infrastructure, Capital and Operating Costs, Production Target and Ore Reserves and other financial forecasts) is extracted from an announcement dated 16 April 2026, which is available to view at www.sovereignmetals.com.au.
Sovereign confirms that a) it is not aware of any new information or data that materially affects the information included in the original announcement; b) all material assumptions included in the original announcement continue to apply and have not materially changed; and c) the form and context in which the relevant Competent Persons' findings are presented in this announcement have not been materially changed from the original announcement.
The information in this announcement that relates to the exploration results (metallurgy) is extracted from announcements dated 28 September 2023, 8 May 2024, 15 May 2024, 4 September 2024, 21 January 2026 and 27 May 2026, which is available to view at www.sovereignmetals.com.au. Sovereign confirms that a) it is not aware of any new information or data that materially affects the information included in the original announcement; b) all material assumptions included in the original announcement continue to apply and have not materially changed; and c) the form and context in which the relevant Competent Persons' findings are presented in this announcement have not been materially changed from the original announcement.
Forward Looking Statement
This report may include forward-looking statements, which may be identified by words such as "expects", "anticipates", "believes", "projects", "plans", and similar expressions. These forward-looking statements are based on Sovereign's expectations and beliefs concerning future events. Forward looking statements are necessarily subject to risks, uncertainties and other factors, many of which are outside the control of Sovereign, which could cause actual results to differ materially from such statements. There can be no assurance that forward-looking statements will prove to be correct. Sovereign makes no undertaking to subsequently update or revise the forward-looking statements made in this release, to reflect the circumstances or events after the date of that release.
The information contained within this announcement is deemed by Sovereign to constitute inside information as stipulated under the Regulation 2014/596/EU which is part of domestic law pursuant to the Market Abuse (Amendment) (EU Exit) Regulations (SI 2019/310) ("UK MAR"). By the publication of this announcement via a Regulatory Information Service, this inside information (as defined in UK MAR) is now considered to be in the public domain.
This information is provided by RNS, the news service of the London Stock Exchange. RNS is approved by the Financial Conduct Authority to act as a Primary Information Provider in the United Kingdom. Terms and conditions relating to the use and distribution of this information may apply. For further information, please contact rns@lseg.com or visit www.rns.com.
RNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.
ENDRNS may use your IP address to confirm compliance with the terms and conditions, to analyse how you engage with the information contained in this communication, and to share such analysis on an anonymised basis with others as part of our commercial services. For further information about how RNS and the London Stock Exchange use the personal data you provide us, please see our Privacy Policy.